Shifting Playbook for Corporate Power Procurement
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s proposed scope 2 revisions would shift many large power buyers from annual renewable energy certificate (REC) accounting to 24/7 hourly matching and reveal a larger emissions gap than most inventories currently report.
- Of all the US grid regions modeled, the emissions gap between annual and 24/7 hourly matching is widest in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the markets where data center load is growing fastest.
- Relae's modeling quantifies the shift from annual to 24/7 hourly matching: serving a 4-gigawatt (GW) data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM, a roughly 800-megawatt premium in PJM that translates directly into cost and siting strategy.
- Closing that gap requires investments in clean, firm generation technologies, like natural gas with carbon capture and storage (CCS), battery storage, and geothermal. The optimal mix varies by market and load profile, which means modeling current and future emissions positions under 24/7 accounting to understand the best procurement options for a specific portfolio.
Annual REC Accounting No Longer Holds at Data Center Scale
For years, large corporate energy buyers have relied on a straightforward approach: purchase renewable energy certificates (RECs) or sign virtual power purchase agreements (VPPAs) to offset market-based scope 2 emissions. Under the current GHG Protocol guidance, these instruments allow companies to claim low or zero emissions regardless of when or where clean energy is actually generated. When corporate clean energy demand was modest, this fueled new renewable project development while aggregate grid emissions were trending down.
That approach worked, until now. Energy demand from data centers and hyperscalers is surging. The Federal Energy Regulatory Commission (FERC) reported more than 50 GW of data center capacity operating in the US at the end of 2025, much of it concentrated in regions where local clean generation cannot keep pace. When corporate clean energy demand was modest, the gap between contractual claims and physical generation was small enough that few questioned this argument. At hyperscaler levels, with load concentrated in a handful of grids, that gap is becoming too large to ignore.
From a climate perspective, well-designed renewable procurement has created real impact by channeling corporate capital into new clean generation, and reducing CO2 emissions anywhere to benefit the climate everywhere. From a grid perspective, power consumption and generation must balance in real time, and the flow of electricity is constrained by the physics of the transmission system. Some regulators, investors, and standard-setters argue that corporate clean energy claims should be grounded in this second, engineering perspective rather than the first. The GHG Protocol's proposed revisions reflect that view, and would force buyers to defend their claims against it.
Relae’s modeling of this 24/7 framework in PJM and ERCOT helps quantify its costs and emissions implications in the markets where the stakes are highest.
What Does 24/7 Hourly Matching Mean for Scope 2 Accounting?
The biggest proposed change to the GHG Protocol’s current Scope 2 Guidance is the move from annual power reporting and matching to a 24/7 approach. Instead of calculating emissions with an annual emissions factor (EF) based on their independent system operator (ISO) or eGRID region for each megawatt-hour (MWh) consumed, companies would need to use hourly-specific EFs.
Companies would still be able to retire RECs to reduce their market-based emissions. However, companies would need to show that these RECs came from clean energy that was generated on the same grid, in the same hour as their facilities consumed power. This makes annual, location-agnostic REC retirement, currently the dominant practice, insufficient for 24/7 market-based accounting.
Both the time restriction (hourly matching) and the location restriction (generation on the same grid as consumption) will make it more difficult for companies to retire RECs. For example, because today's methodology is location-agnostic, a New York-based company can retire RECs from a Texas wind farm (purchased unbundled or via a VPPA) to reduce its reported market-based scope 2 value. This has allowed renewable development to follow the best resource sites rather than the load. Similarly, the time of day that the wind farm generates energy is irrelevant, as long as it is approximately in the same calendar year.
Under the proposed revisions, retiring these RECs would no longer be acceptable for the New York company, since they would fail both location- and hourly-matching requirements. As a result, companies with large REC portfolios today may no longer be able to retire them in order to reduce their market-based scope 2 emissions, if the proposed revisions take effect. These companies may face significant unmatched consumption under 24/7 accounting, especially during evening peaks or grid stress events when fossil-based generation fills the gap.
Annual Matching vs 24/7 Hourly Matching
The figure below illustrates the gap between what a representative large buyer reports under the current annual location- and market-based methodologies, versus what an hourly 24/7 analysis reveals.
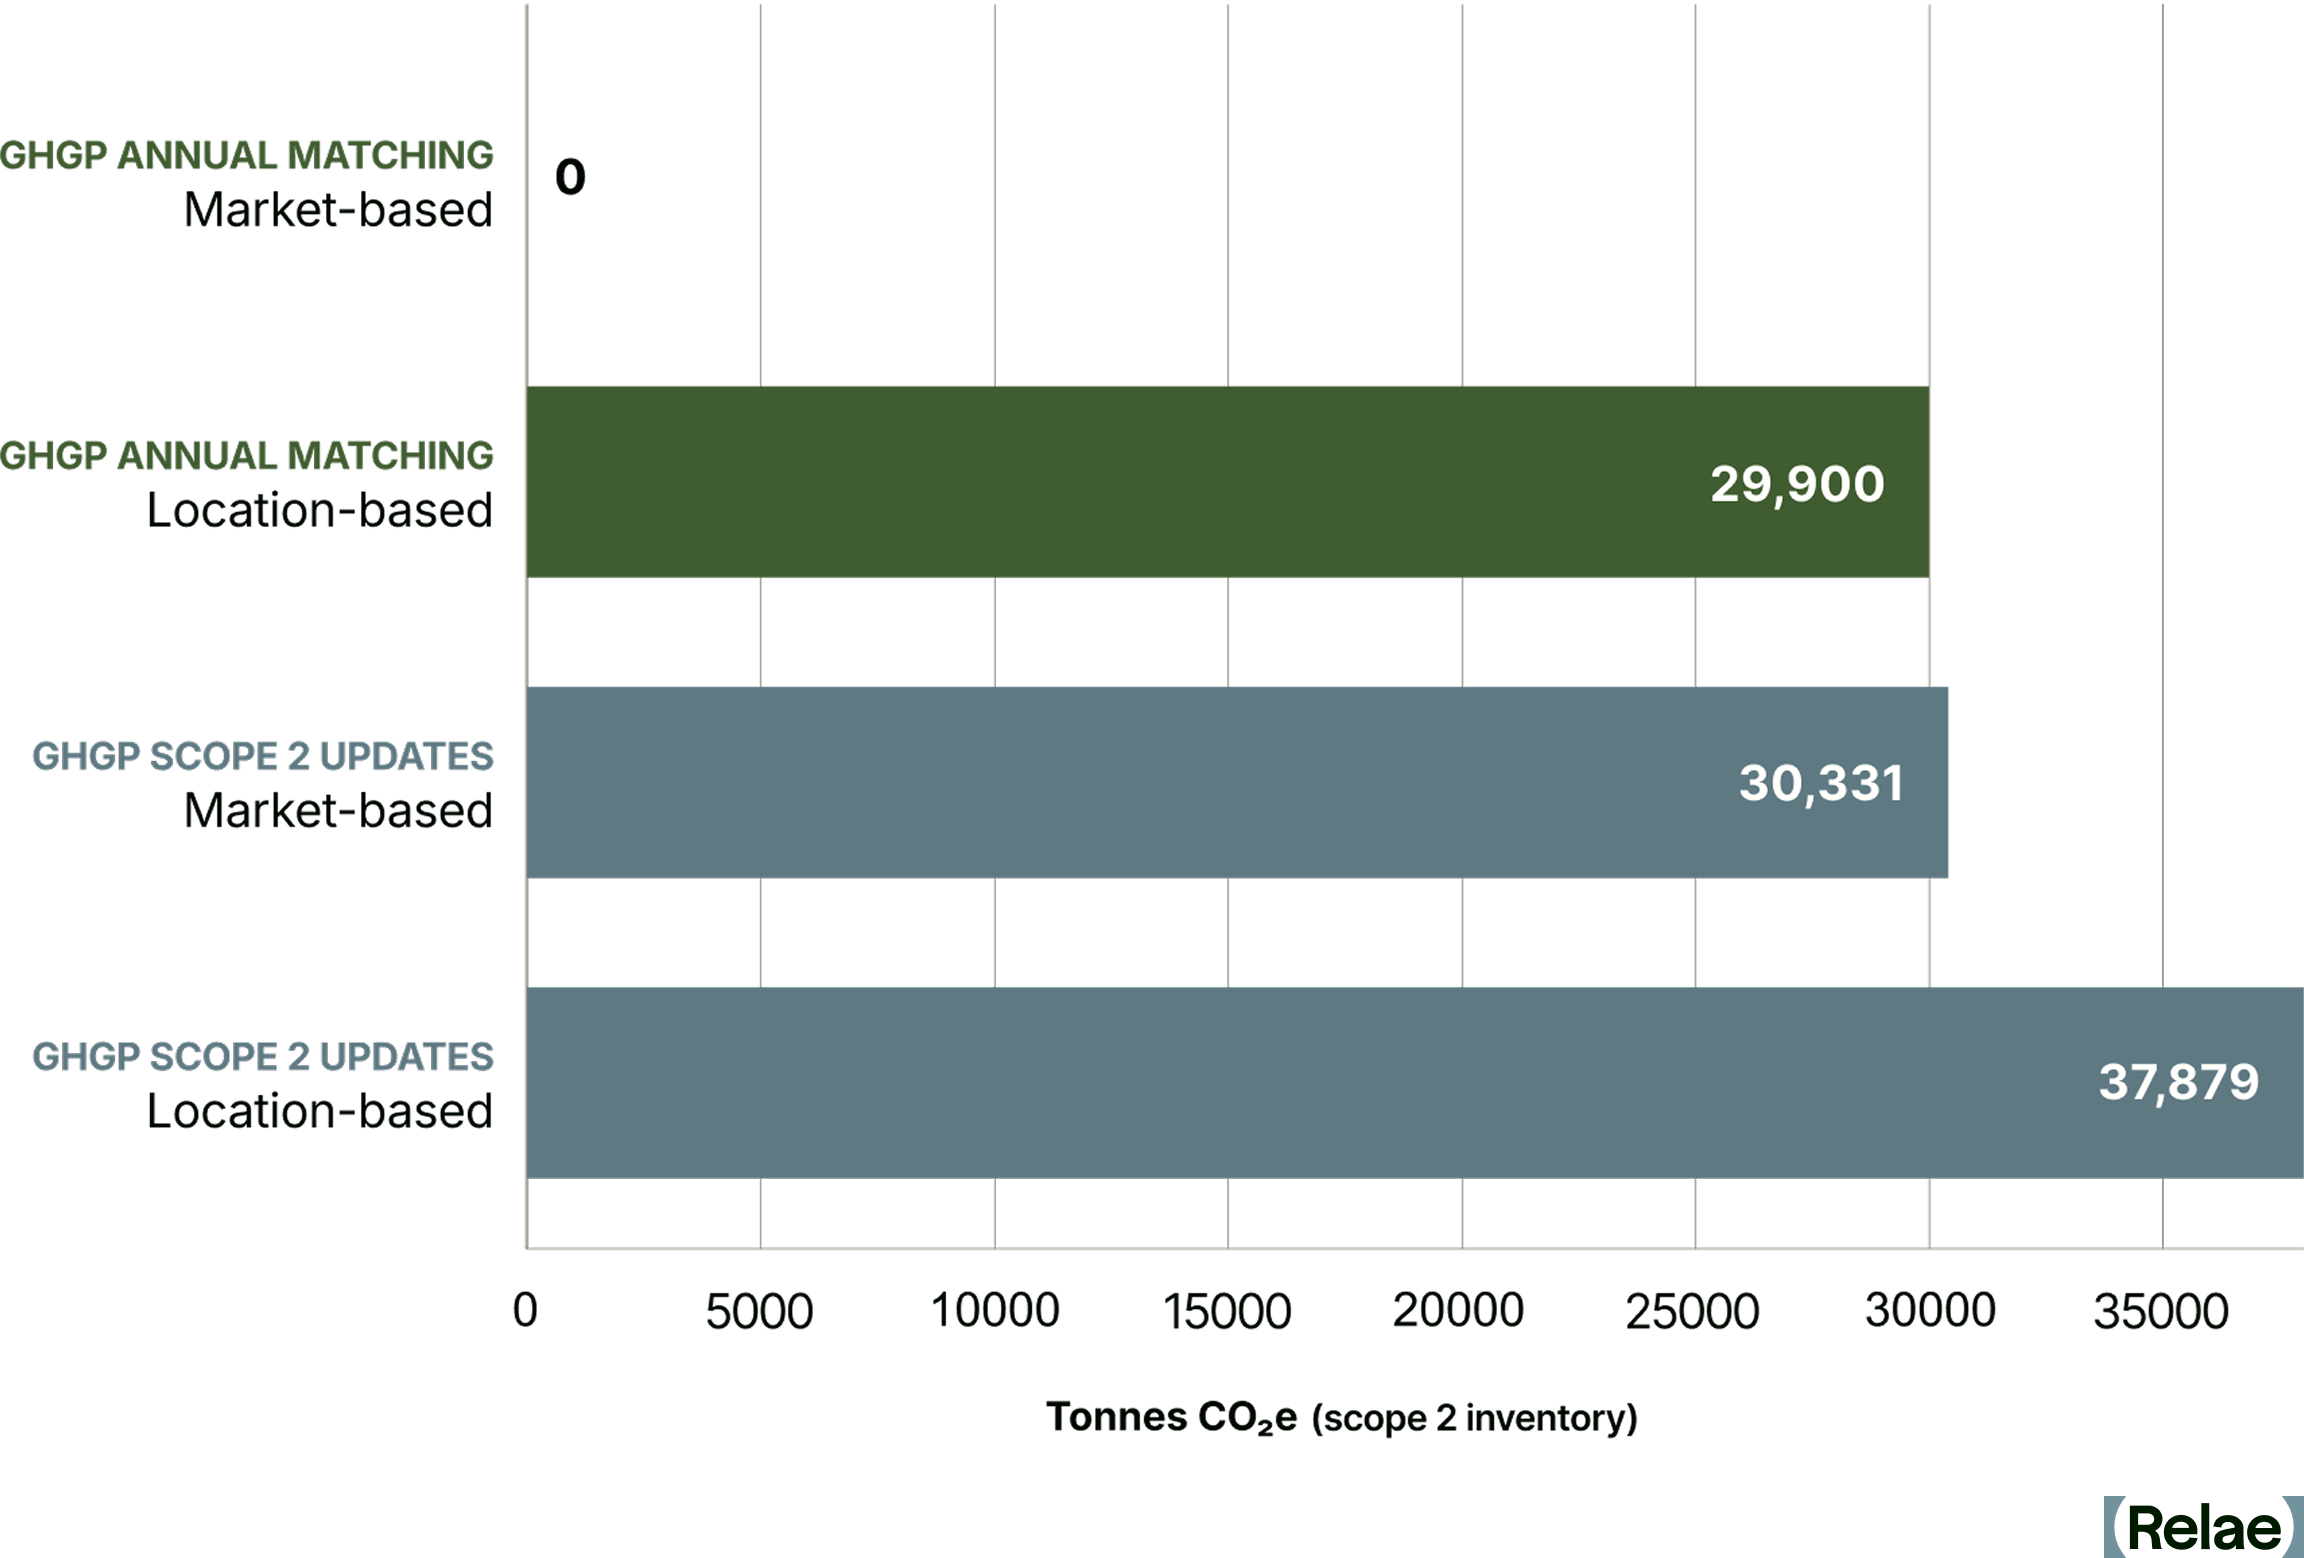
Understanding this emissions gap is the essential first step for buyers to make informed decisions about which instruments to retain, which contracts to renegotiate, and where new investment will matter most. If the proposed scope 2 revisions are enacted, companies procuring clean energy will be disincentivized from buying RECs sourced from variable renewables in distant locations, and instead will find it more favorable to invest in same-grid clean, firm generation, such as geothermal, nuclear, and renewables plus storage. RECs from these projects would qualify to be retired against market-based scope 2 emissions under the proposed revisions, where today's distant-wind or off-peak-solar RECs would not.
Where Pressure Is the Highest: ERCOT and PJM
Two markets stand out for projected hyperscaler load growth: PJM, which covers the extended mid-Atlantic region, and ERCOT in Texas. Both are on track to absorb massive increases in data center demand over the next decade, and both expose the limits of annual REC accounting in ways that will be hard to ignore under the new proposed framework.
PJM: 60% Fossil Generation Means High Marginal Emissions
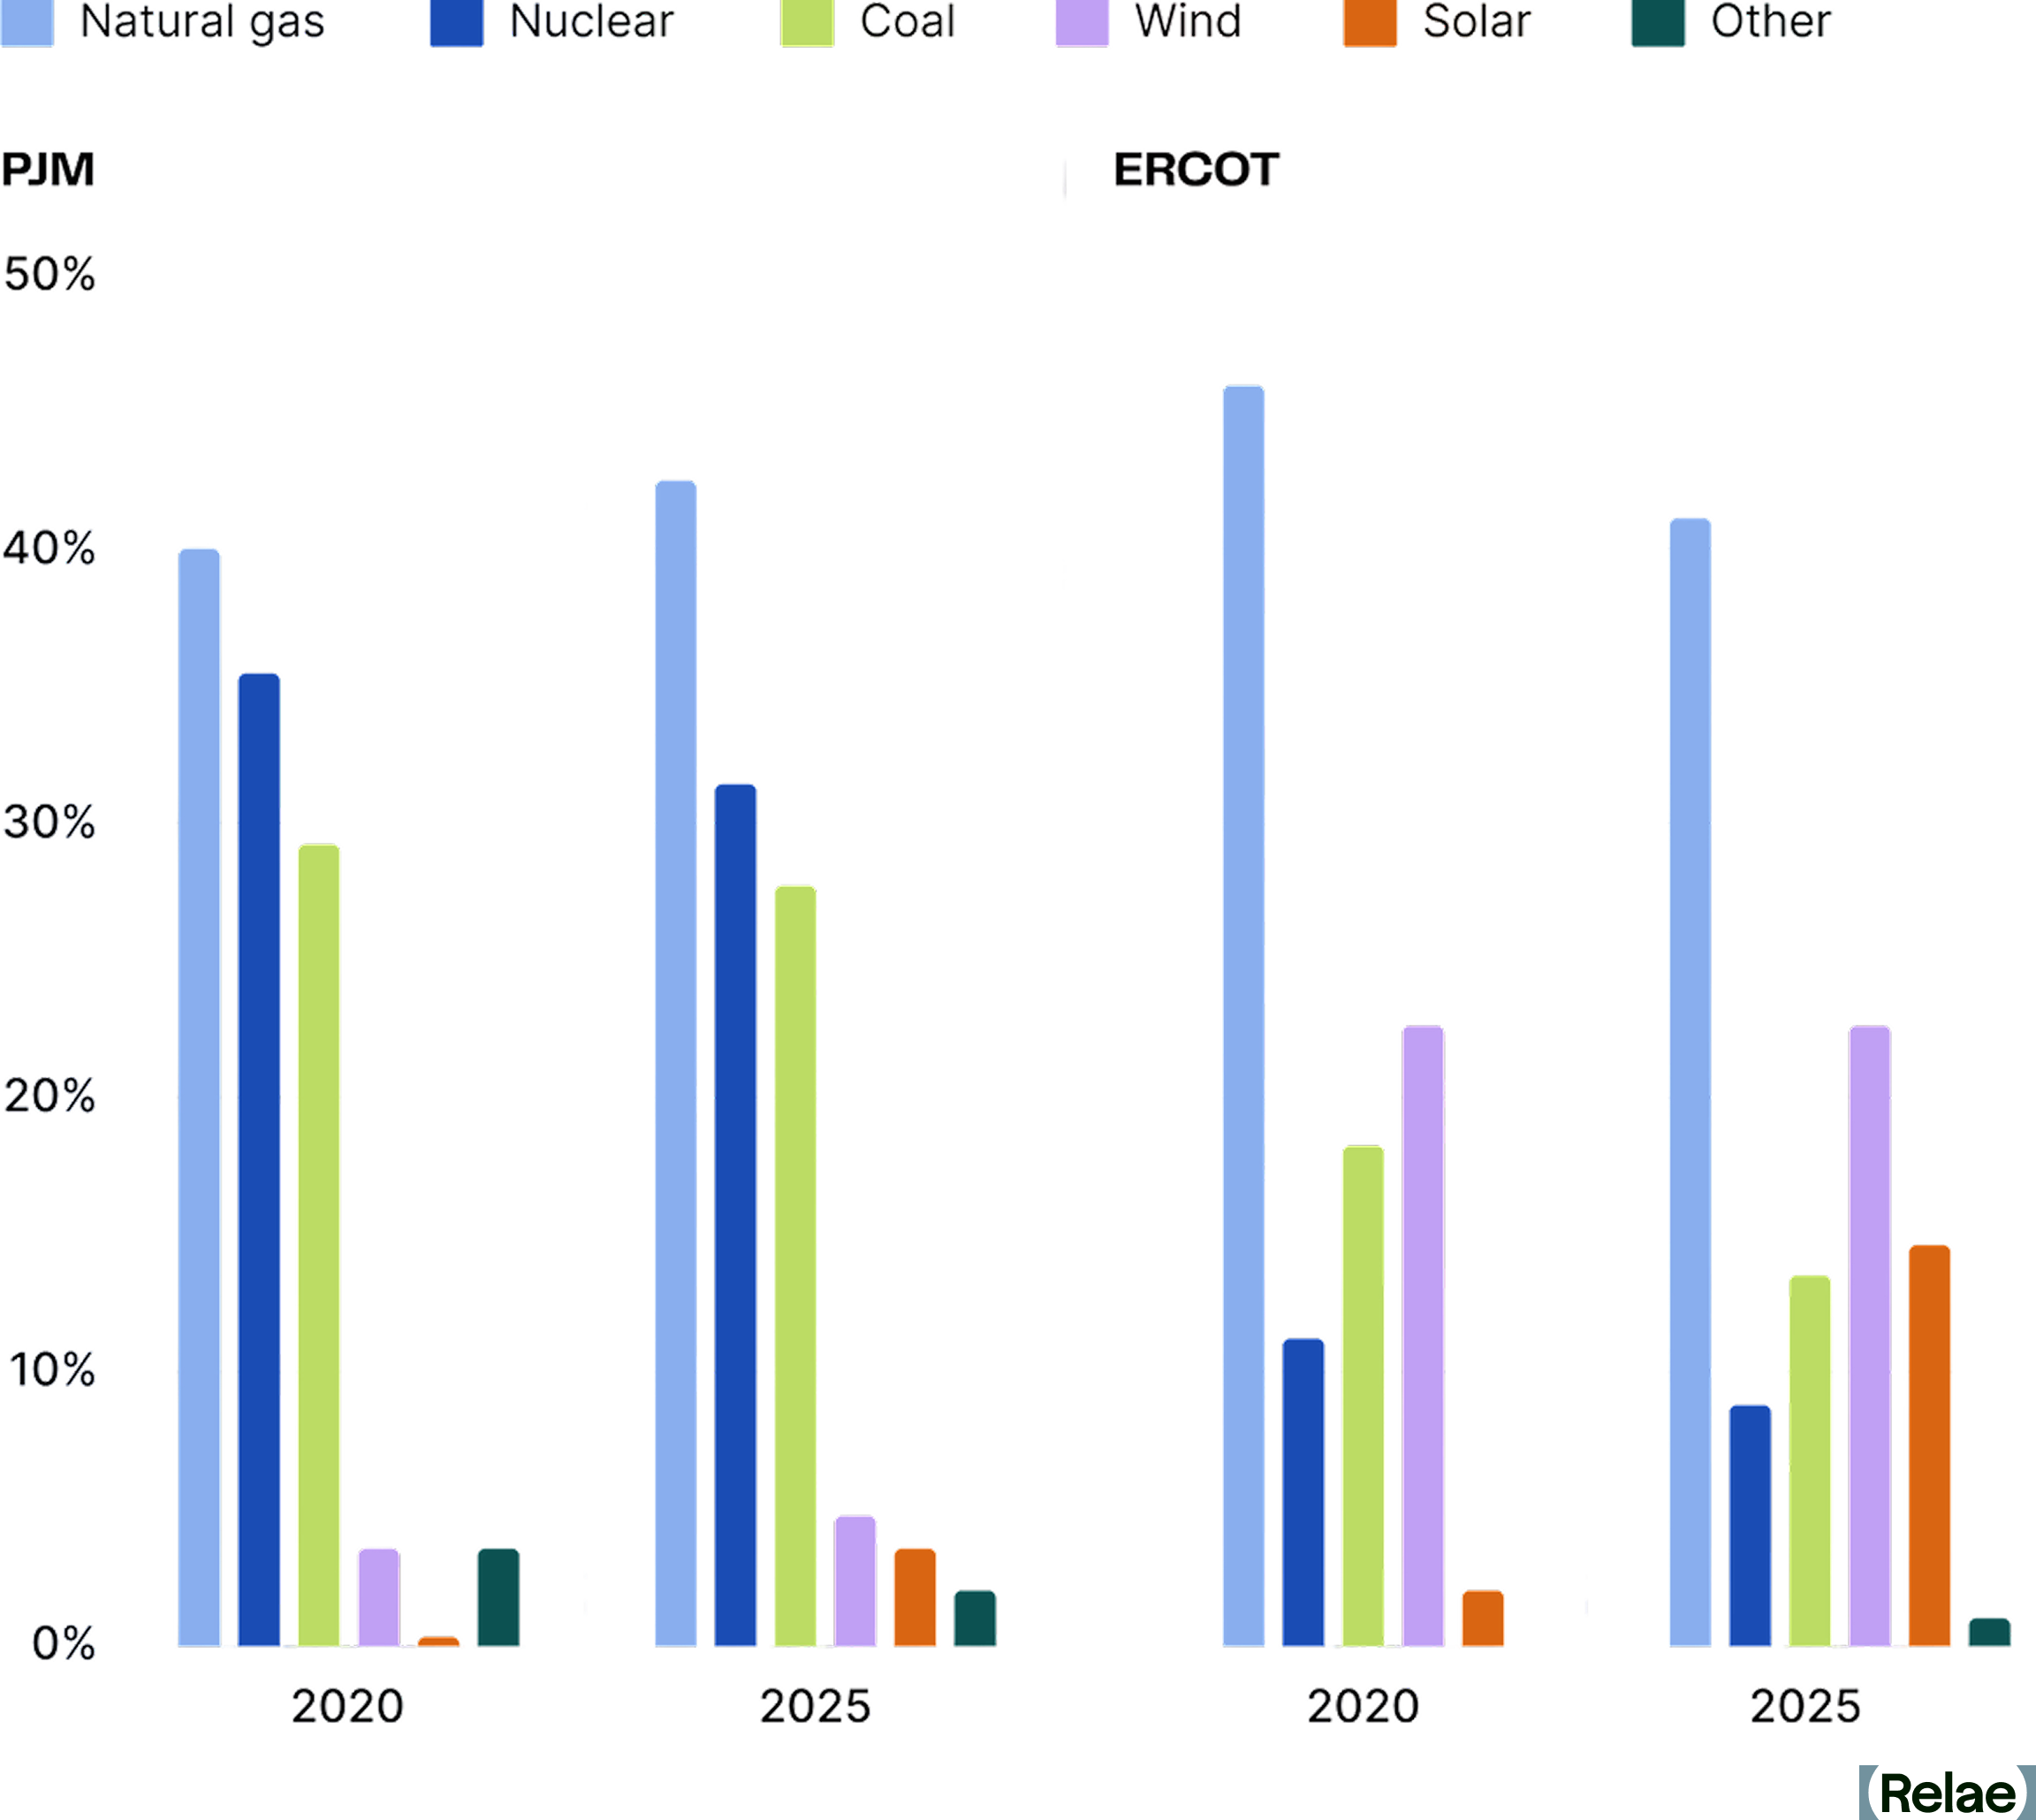
PJM is one of the largest and most complex wholesale electricity markets in the world. Its generation mix still includes 60% coal and natural gas, which means hourly emissions intensity remains high, particularly during evening peaks and grid stress events when fossil generation dominates the dispatch stack.
Buyers relying solely on annual REC retirement may show low market-based scope 2 emissions today, but a 24/7 analysis tells a different story. For PJM-based buyers, this means hourly matching gaps will be largest during evening and overnight hours, when nuclear and storage become disproportionately valuable relative to additional solar.
ERCOT: Solar and Wind Don’t Peak When Demand Does
Texas has abundant wind and solar, with solar generation growing nearly 7x since 2020, but those resources don’t always run when demand peaks. While fossil-based generation has declined since 2020, it still comprises more than half of ERCOT’s generation. Solar dominates midday, wind peaks in the evening, and natural gas fills the gaps, especially during high-demand evenings or extreme weather events.
Buyers with large ERCOT footprints may find that VPPA portfolios, which generate most of their clean energy in off-peak hours, already satisfy the proposed location-based test but fail on hourly matching. Battery storage and demand flexibility could help bridge the gap.
Figure 3 below quantifies that gap in both markets by showcasing the carbon-free energy (CFE) score in ERCOT and PJM, as well as the additional capacity required for a 4 GW load to achieve a 100% CFE target. The CFE score is the share of grid-supplied electricity in a given hour that comes from carbon-free sources, and is the metric the proposed scope 2 revisions would use to evaluate hourly matching. A 100% CFE target means electricity consumption is matched to carbon-free generation in every hour of the year.
In the left panel, a representation1 of each market's 2030 hours are sorted by grid (CFE) score, from the dirtiest hour on the left to the cleanest on the right. Neither grid approaches 100% carbon-free on its own, and the shaded areas represent the unmatched hours a buyer claiming 100% clean energy through annual instruments would actually carry under 24/7 accounting. The gap is the maximum unmatched hours a buyer might be exposed to, as some RECs procured through annual matching may qualify under the new rules, if satisfying the locational and hourly requirements.
The right panel translates that gap into action. The additional co-located clean generation and storage required to serve a representative 4 GW load (roughly 5% of the forecast 2030 C&I load in ERCOT and 4% in PJM) at a 100% hourly CFE target, on top of what the underlying grid already provides.
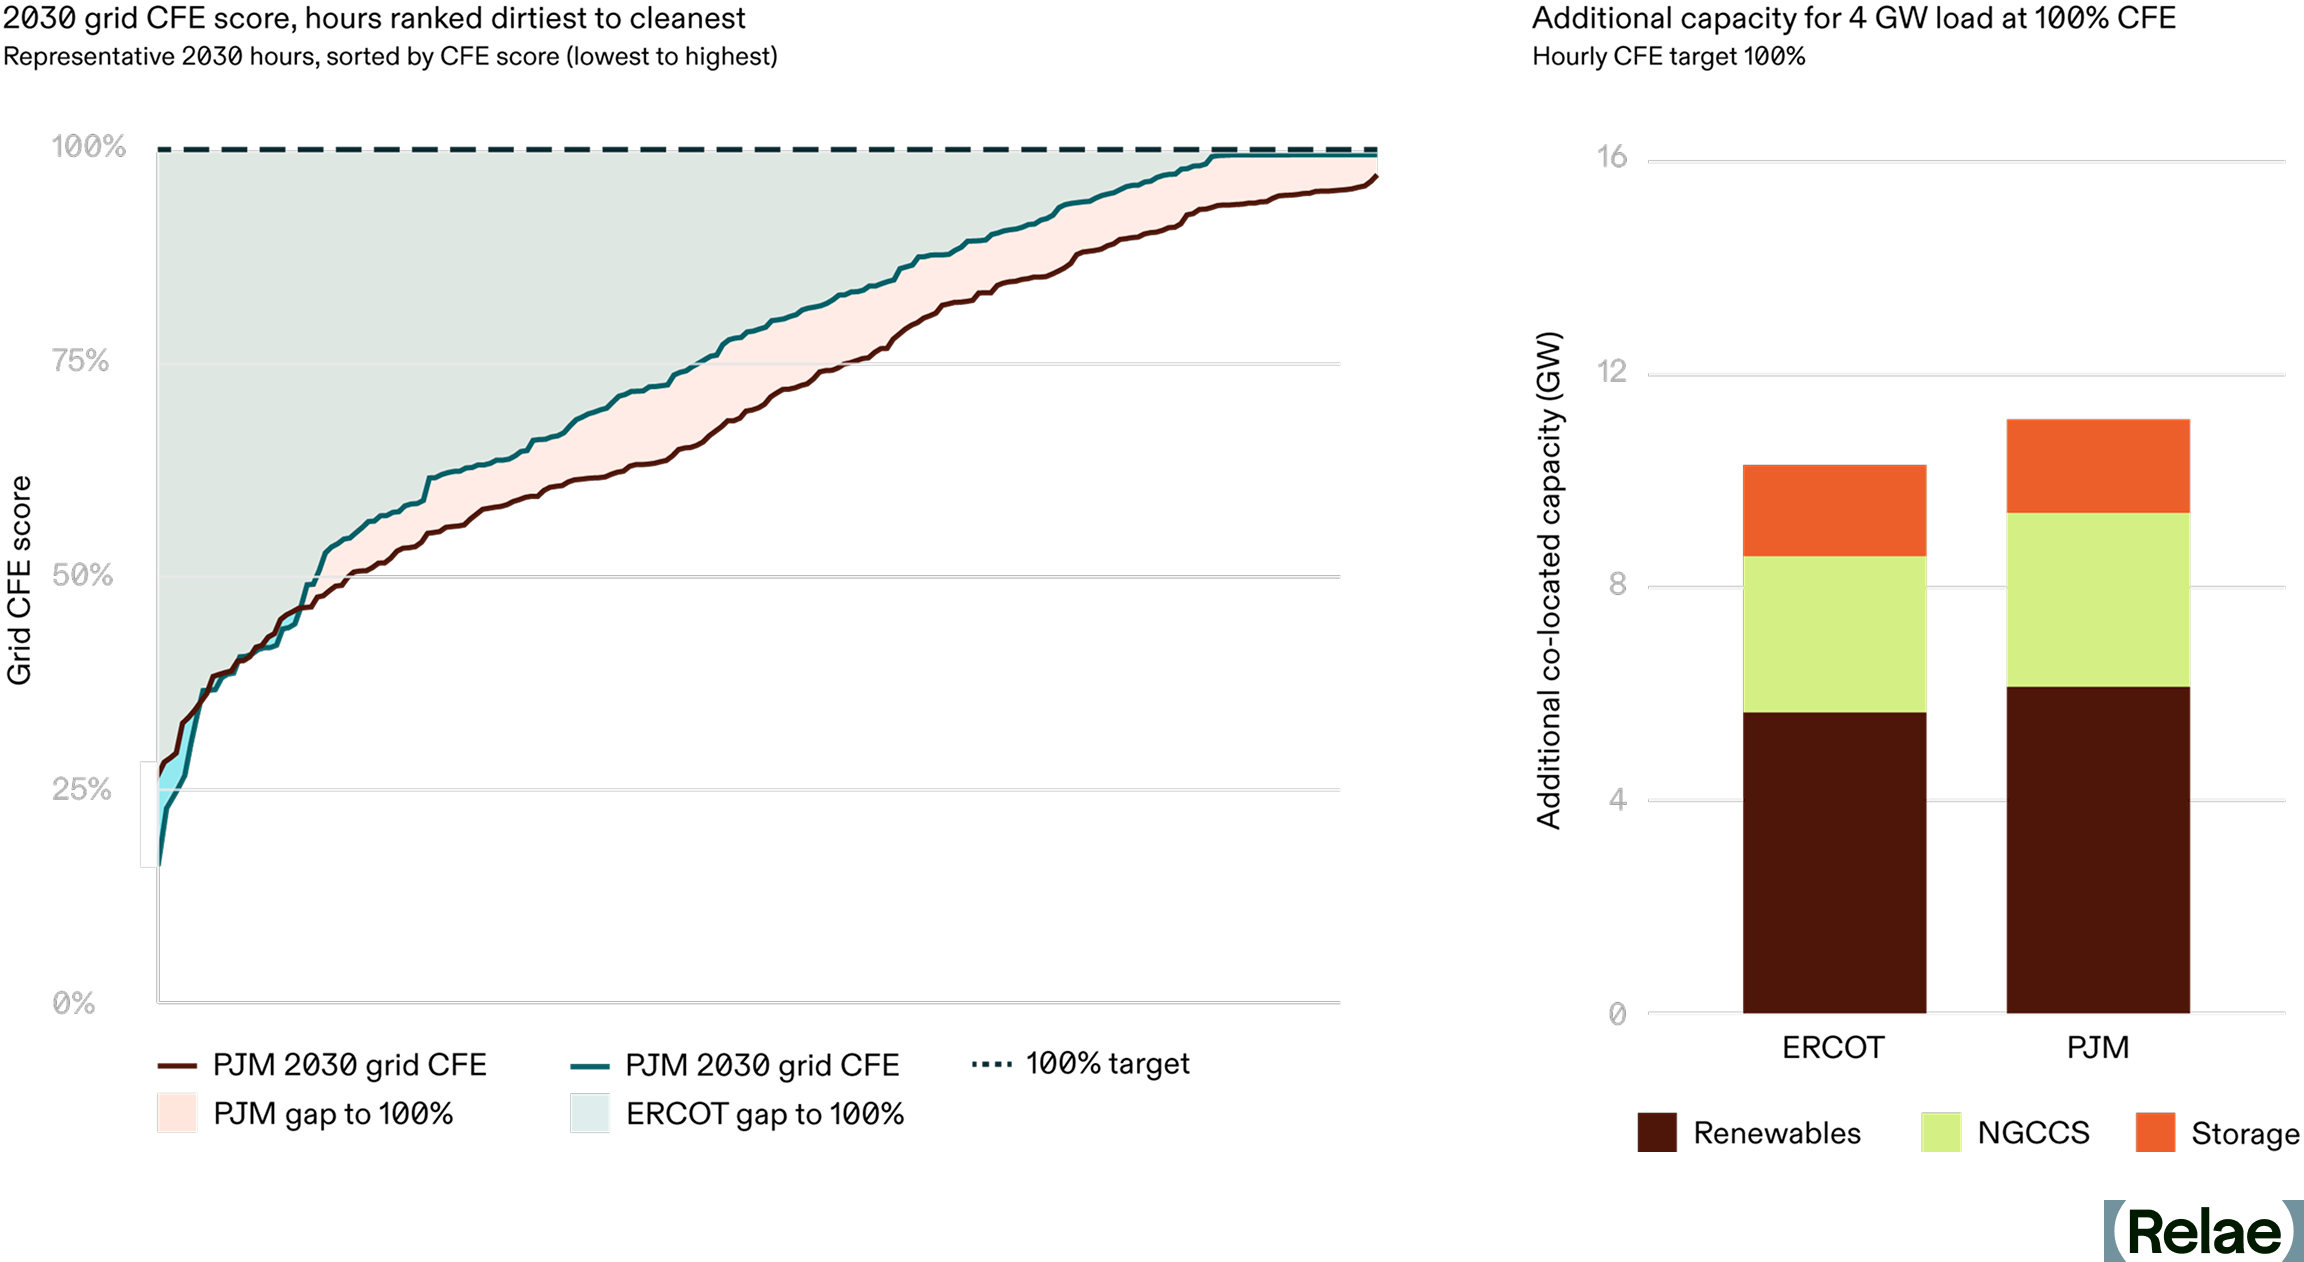
A few patterns are worth highlighting. First, the left panel confirms that PJM’s grid will still spend materially more hours below 100% carbon-free than ERCOT’s in 2030, a direct consequence of the coal- and gas-heavy generation mix described above. Notably, ERCOT's curve reaches 100% in a meaningful share of hours (windows when the grid is running entirely on carbon-free resources), while PJM's never does, meaning some fossil generation is dispatched in every hour.
Second, the ISO a buyer operates in drives a meaningful difference in build-out: hitting 100% hourly CFE for a 4 GW load takes 9.6 GW of additional capacity in ERCOT and closer to 10.5 GW in PJM. This indicates the advantage of achieving hourly and locational matching in already clean grids, which may influence a buyer choosing where to site new workloads.
Renewables have the largest share of the additional capacity in both markets (5-6 GW), paired with significant long-duration energy storage (~2 GW), while natural gas with CCS provides meaningful clean, firm capacity (~3 GW). ERCOT’s storage share of capacity is slightly larger, reflecting the midday-solar/evening-load mismatch, while PJM leans a bit more on natural gas with CCS, where clean, firm generation does more of the heavy lifting due to lower wind speeds and solar irradiance than Texas.
The right panel also illustrates why clean, firm technologies (natural gas with CCS, advanced nuclear, and enhanced geothermal) are likely to be included alongside renewables and batteries in any serious 24/7 portfolio. With only renewables and batteries, hitting the same target requires about double the total generation and storage capacity. In both markets, targets that look achievable today on an annual REC basis will require materially more capital and a different mix of resources, under 24/7 accounting.
Top Questions Large Power Buyers Need to Model Before the Rules Change
The GHG Protocol revisions are not finalized, and the timing of any mandate remains uncertain, which is exactly why modeling cannot wait.
A useful self-test for any large power buyer is: can your team answer the following today with defensible numbers?
- What is your hourly CFE score across your largest load centers, and how far does it sit from your reported market-based emissions?
- Which of your existing VPPAs and REC contracts hold value under 24/7 accounting, and which become effectively stranded?
- What mix of resources delivers the incremental clean, firm capacity that closes your gap in PJM, ERCOT, or wherever your load is concentrated at the lowest cost?
- If your next gigawatt of load were sited in a different ISO, how would your emissions position change?
Clean firm projects do not appear off the shelf. Advanced nuclear, enhanced geothermal, and natural gas with CCS all carry multi-year development timelines, and corporate offtake agreements are often what get these projects financed in the first place. Buyers who engage now help shape the project pipeline that will be available in their target markets in 2030, and can lock in offtake terms before competition for the most valuable sites tightens. Buyers who wait until the methodology is final will be working with shorter lead times, fewer development partners, and less leverage to specify projects that fit their load profiles and hourly matching needs.
Frequently Asked Questions
What is 24/7 hourly matching, and how does it differ from today's REC accounting?
Today's scope 2 accounting lets companies retire renewable energy certificates (RECs) from any grid, at any time of year, to offset their emissions. The GHG Protocol's proposed 24/7 hourly matching would require RECs to come from clean generation on the same grid, in the same hour a facility consumes power, making most of today's location-agnostic RECs ineligible for market-based accounting.
Why are PJM and ERCOT under the most pressure from this shift?
Both markets are absorbing the fastest-growing data center load in the country, and both still lean on fossil generation to meet demand outside peak renewable hours. PJM's generation mix is 60% coal and gas, while ERCOT's solar and wind often don't peak when demand does, so buyers in these markets face the largest gaps between their annual REC claims and their actual hourly carbon-free energy score.
How much additional clean capacity does it take to close the gap?
Relae's modeling finds that serving a 4 GW data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM. That capacity mix leans on renewables and long-duration storage in both markets, with natural gas with CCS playing a larger role in PJM, where wind and solar resources are weaker.
What should power buyers do before the GHG Protocol revisions are finalized?
Start modeling now. Buyers should know their hourly carbon-free energy score, understand which existing VPPAs and REC contracts hold value under 24/7 accounting, and identify the lowest-cost mix of clean, firm resources that closes their gap. Clean firm projects like advanced nuclear, enhanced geothermal, and natural gas with CCS take years to develop, so buyers who engage early have more influence over the project pipeline and better offtake terms.
Modeling the 24/7 Emissions Gap with Relae
For large power buyers assessing what the proposed GHG Protocol revisions mean for their power procurement portfolio, Relae's Advanced Power Emissions Analysis solution models the gap between current market-based reporting and what 24/7 accounting would reveal—by market, load profile, and technology stack.
Power & Energy
Relae provides independent advisory for large corporate buyers, power providers, and infrastructure investors making high-stakes decisions about clean firm power, grid constraints, data center energy optimization, and long-term investment strategy. Our insights help you evaluate solutions that can be deployed reliably, responsibly, and affordably, so you can navigate an evolving energy landscape with confidence.
Advanced Power Emission Accounting Methodologies for Large Electricity Loads


Julia Millot
Julia Millot
,

Julia Millot is a Senior Power Decarbonization Manager at Relae, working directly with clients on measuring and reducing electricity-related GHG emissions and optimizing power portfolios. Julia has over a decade of experience working with clients in the energy, tech, retail, financial, and manufacturing sectors on growth and climate strategies. Prior to Relae, she led US Climate Advisory at Position Green and ran her own consultancy, Green Opal Advisors, focusing on corporate decarbonization.
Douglas Bryan
Douglas Bryan
,
Douglas Bryan is an energy economist with a decade of experience across global energy markets, including the US, Canada, Europe and Australia. He specializes in evaluating the impacts of policy and investment decisions through advanced energy system modeling.
Douglas has led a diverse range of analyses on utility integrated resource planning, electricity decarbonization policy, and market advisory due diligence. He has extensive experience evaluating the business case for power sector investments, including battery and long-duration energy storage, and advising utilities on the greenhouse gas implications of load and resource planning scenarios. He also leads Relae’s battery storage modeling Beyond electricity, he has simulated deployment of Carbon Dioxide Removal technologies, including Direct Air Capture, BECCS and Ocean Alkalinity Enhancement, via energy-economy modeling.
A trusted expert in energy system and economic analysis, Douglas previously served as a Senior Project Manager at Navius Research, where he presented at regulatory tribunals and led technical workshops. At Relae, he leverages this background to help clients navigate complex decarbonization efforts. He provides the rigorous analysis needed to quantify the carbon impact of operations and identifies the most effective strategies for integrating low-carbon energy solutions into power portfolios.
- All 8760 hours in the year were split into 200 contiguous segments; segment splits were determined based on minimizing segment variation across key metrics (e.g. renewables generation, load profile, etc.)
What to Read Next
Carbon Capture for Natural Gas-Fired Power Generation: An Opportunity for Hyperscalers
Key Takeaways
- AI-driven data center demand is outpacing grid capacity, and hyperscalers are bringing more natural gas, which already supplies about 40% of US electricity, online to meet their needs.
- Pairing carbon capture and sequestration (CCS) with natural gas lets data centers source firm power today while cutting plant-level emissions up to 95%—without waiting on multi-year renewable interconnection queues.
- The Google-Broadwing deal demonstrates real progress and commitment toward natural gas with CCS as the first major commercial deployment of this exact pathway
Meeting Electricity Demand and GHG Emission Reduction Targets
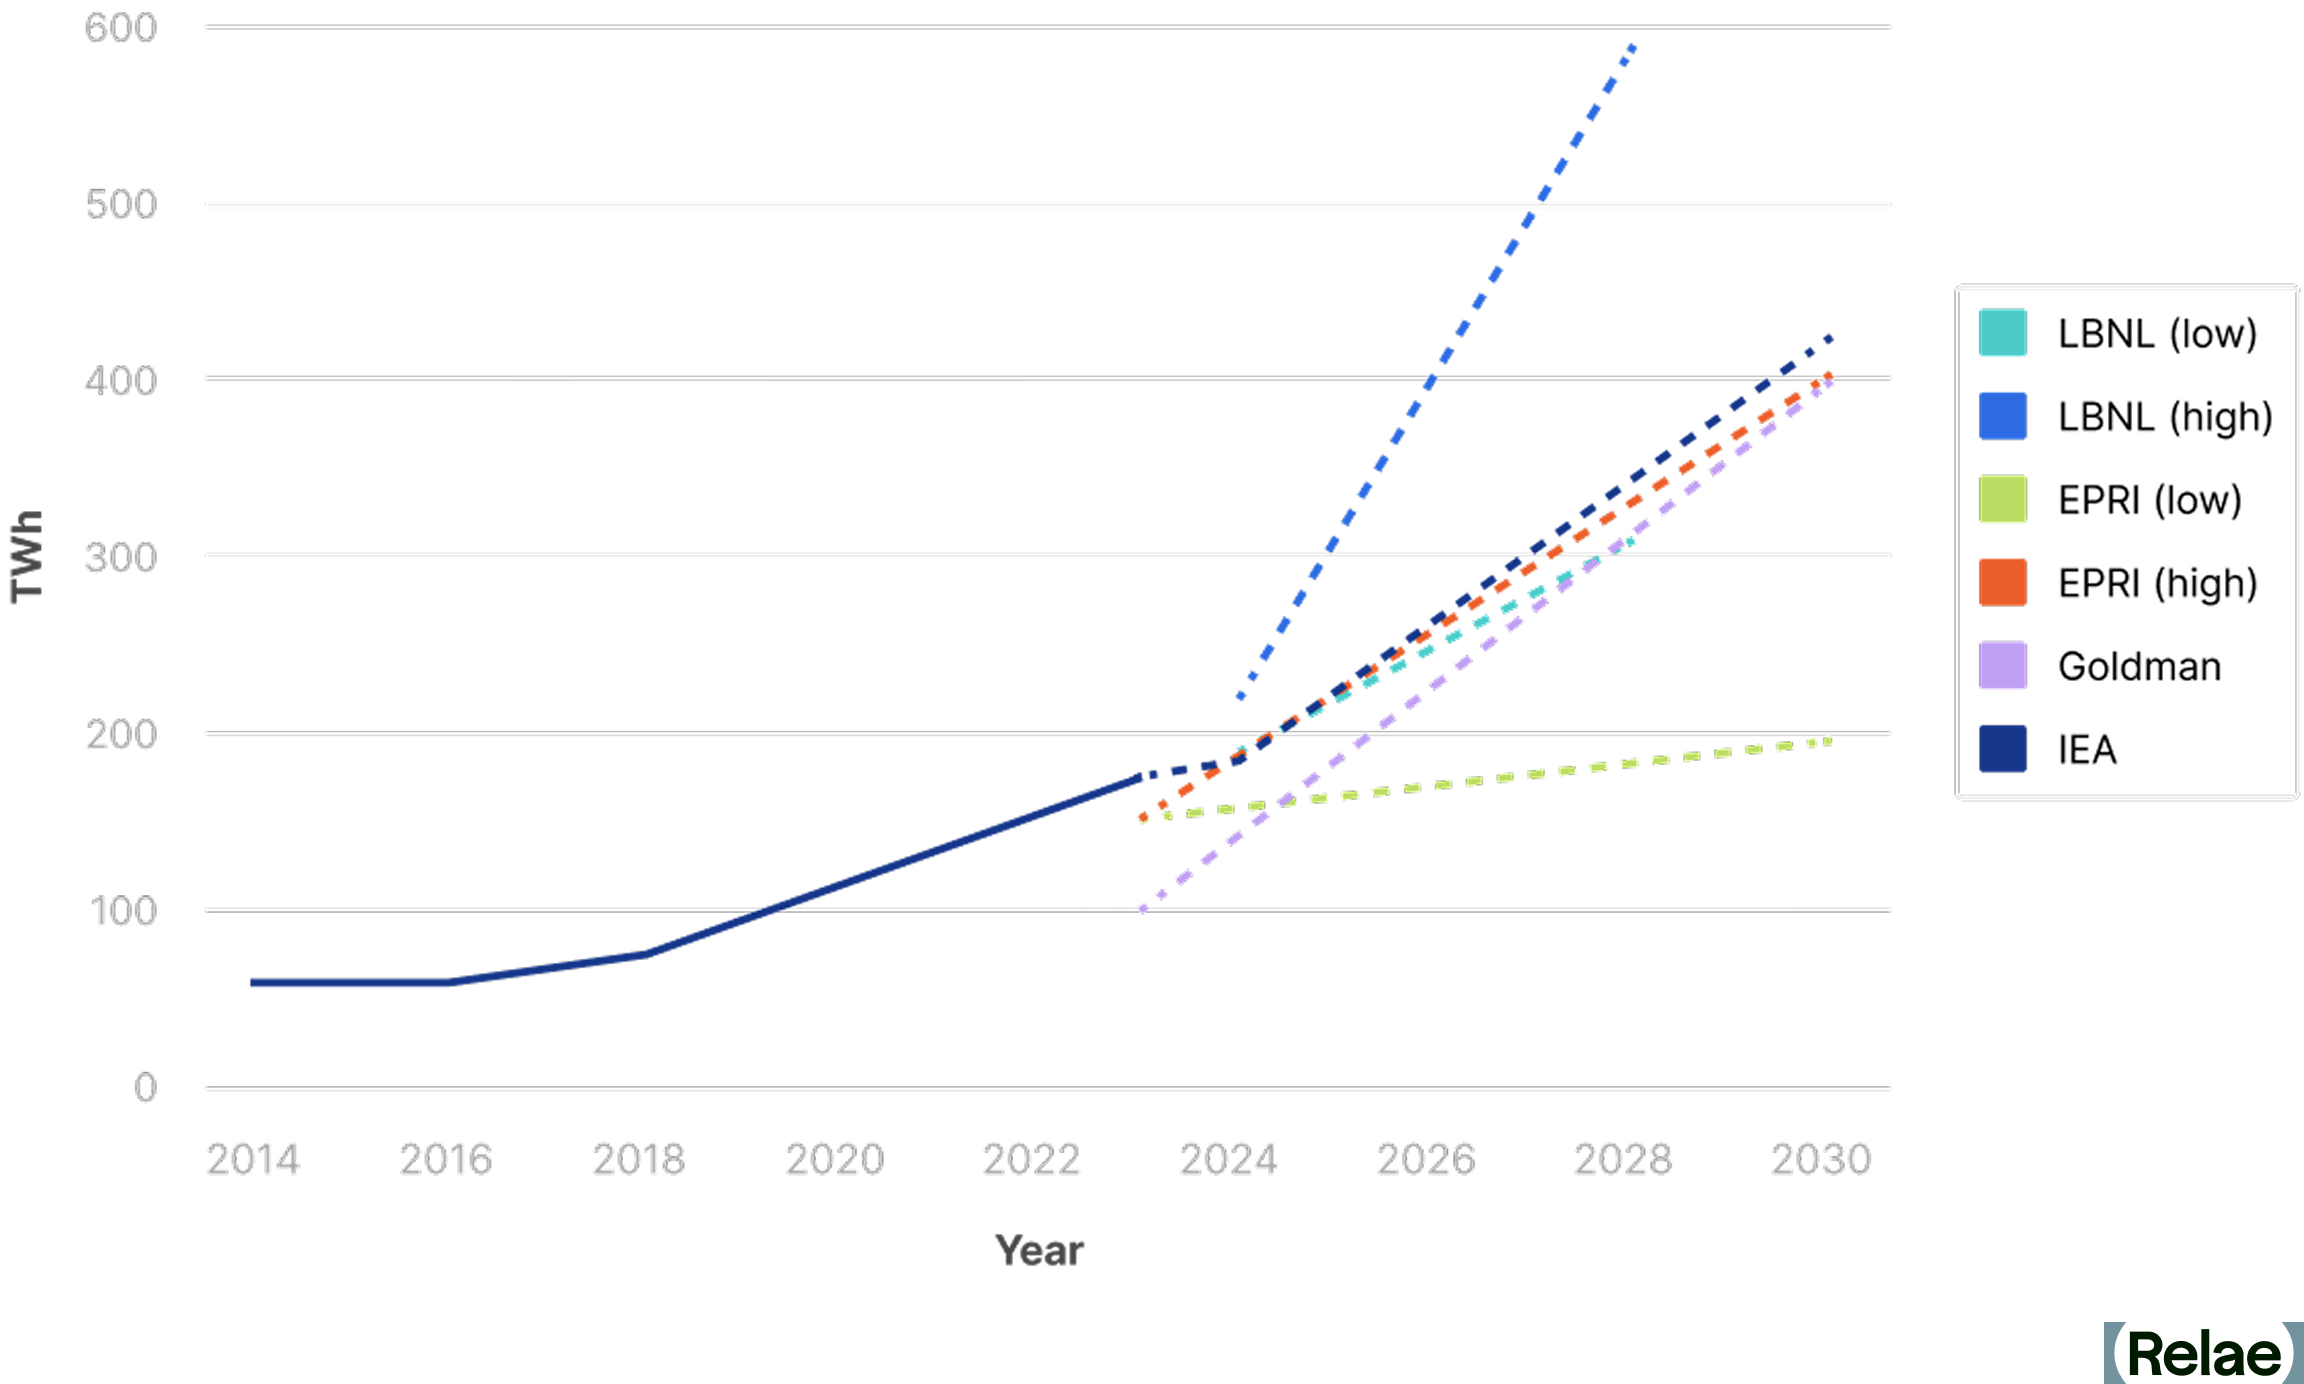
Rapid growth in electricity demand across the US, driven by AI data center expansion and increased industrial electrification, is placing significant pressure on power grids. After decades of stable electricity load, demand has increased significantly since 2022 and is expected to rapidly grow for the foreseeable future. Natural gas currently fuels around 40% of US electricity generation. Its share is expected to grow in the coming years. However, unabated natural gas generation is not compatible with stakeholder targets to reduce greenhouse gas (GHG) emissions. Combining CCS with natural gas-fired generation is one pathway to meet growing electricity demand and achieve GHG emission reduction targets.
[cta]
The Role of Natural Gas in Electricity Supply
Natural Gas Generation Versus Renewable Generation Deployment
Electricity generators can provide multiple products to regional grids, generally providing two services: energy (power production) and reliability (consistent availability). Natural gas-fired plants can provide both, whereas renewable energy sources like wind and solar generate energy but offer less reliability.
As electricity demand rapidly grows, grids will need both energy and reliability to function effectively. However, the interconnection queue for renewable energy assets has a years-long backlog which is delaying their deployment. Grids will need additional reliability assets to support the large amounts of renewables (usually in the form of storage). Some jurisdictions are creating an alternate pathway for natural gas plants to bypass the lengthy interconnection queue which may allow for the rapid development of natural gas generators. Hyperscalers are also pursuing development of large behind-the-meter (BTM) generation of electricity from renewable and fossil sources, but these must also meet high standards for reliability.
The Case for Carbon Capture Deployment
Electric utilities and developers of data center infrastructure are planning to build substantial new natural gas generation assets in addition to maximal deployment of renewable electricity. CCS technology enables natural gas plants to deliver stable, continuous power while significantly reducing emissions by capturing up to 95% of emitted CO₂. Natural gas plants with CCS are viable options to deliver the lower-emission, reliable power needed to respond to rapidly emerging AI data center power demand growth. The 45Q tax credit, a key government incentive for CCS, was preserved and effectively strengthened under 2025's One Big Beautiful Bill Act. The Google-Broadwing deal, the first major commercial deployment of this exact pathway, was signed in October 2025 and serves as a useful proof point.
Benefits of Integrating CCS into Natural Gas Power Generation
Integrating CCS into natural gas-fired power plants provides several advantages for data center stakeholders:
- Reduced carbon emissions: Achieve emission intensities of approximately 80–120 kg of CO₂ equivalent per megawatt-hour (CO₂e/MWh), significantly below the current US grid average of approximately 340–420 kg CO2e/MWh.
- Reliable baseload power: Continuous, predictable electricity delivery.
- Compact infrastructure: Requires less land compared to renewable energy projects, simplifying data center siting near existing infrastructure.
- Cost: CCS integrated with new natural gas-fired generation can deliver low-cost decarbonization. Relae estimates $75-150/MWh, which is competitive in many markets with other firm baseload options such as new nuclear power or wind and solar with battery backup.
Seven Key Considerations for Implementing CCS
Stakeholders considering CCS technology must carefully evaluate seven critical factors:
1. Meeting Rapid Deployment Timelines
Traditional natural gas plants can be operational within roughly 18 months, provided they bypass interconnection queues for reliability purposes and have access to key equipment. Integrating CCS technology extends this by an additional 18–36 months. Designing plants to be "capture-ready" allows for quicker initial deployment and smoother CCS integration in the future. However, deploying a capture-ready plant without a commitment to build the carbon capture portion is inconsistent with serious climate action.
2. Sizing Plants Optimally
CCS is most economically and environmentally optimal at natural gas plants with capacities of 100 MW or greater. It offers significant opportunities for emissions reductions for the forecasted new data center load. CCS is not suitable for smaller or highly variable natural gas plants.
3. Selecting Effective Carbon Capture Technology
CCS technologies such as solvents, sorbents, membranes, and oxyfiring vary significantly in maturity, efficiency, and cost. Choosing the right approach requires thorough evaluations aligned with specific project requirements. These will vary by setting and configuration (e.g., turbine class, reciprocating engines, number of units, water availability, etc.).
4. Navigating CO₂ Transportation Logistics
The safe and efficient transport of captured CO₂ via pipelines, rail, or barges is critical. Aligning infrastructure planning with overall project timelines prevents delays.
5. Ensuring Safe and Effective Sequestration
If there is no CO₂ storage, there is no project. Permanent CO₂ storage in Class VI injection wells requires detailed geological studies and regulatory permitting. Early collaboration with experienced sequestration operators is essential to success.
6. Conducting a Comprehensive Life Cycle Analysis
Full life cycle emissions analyses, including upstream methane leakage, construction impacts, and CO₂ transportation, are critical for accurate environmental assessments and ensuring low-carbon electricity supply. Prioritizing low-leakage, third-party verified natural gas supply enhances positive climate impacts.
7. Performing Siting Feasibility Early
An early and quick feasibility assessment is critical to identifying promising opportunities and key barriers at candidate CCS sites. Important factors include available transmission capacity, the potential to expedite approval of interconnection for thermal resources, regulatory barriers, state and local incentives, the sufficiency of natural gas infrastructure, and water supply.
Frequently Asked Questions
How much longer does adding carbon capture take compared to building a natural gas plant alone? Traditional natural gas plants can be operational within roughly 18 months, provided they bypass interconnection queues for reliability purposes and have access to key equipment. Integrating CCS technology extends this by an additional 18–36 months.
Is a "capture-ready" natural gas plant a legitimate climate strategy if the capture portion isn't committed yet? Designing plants to be "capture-ready" allows for quicker initial deployment and smoother CCS integration in the future. However, deploying a capture-ready plant without a commitment to build the carbon capture portion is inconsistent with serious climate action. “Capture committed” is a better stance than “capture ready”.
How does the cost of natural gas-fired power with CCS compare to nuclear or renewables with battery storage? CCS integrated with new natural gas-fired generation can deliver low-cost decarbonization. Relae estimates $75-150/MWh, which is competitive in many markets with other firm baseload options such as new nuclear power or wind and solar with battery backup.
Has any hyperscaler actually deployed natural gas-fired power with CCS at scale yet? The Google-Broadwing deal, the first major commercial commitment of this exact pathway, was signed in October 2025 and serves as a useful proof point. Others are in development.
[cta]
How Relae Supports Data Center Decarbonization
Natural gas-fired generation combined with CCS is a proven solution for meeting the urgent electricity demands of data centers while significantly reducing emissions. Relae helps stakeholders navigate the complexities of CCS deployment through deep, science-backed expertise and strategic advisory services. Our experienced team provides comprehensive support throughout CCS project planning and execution, including technology selection, life cycle emissions analysis, infrastructure assessment, project viability, regulatory compliance, and risk management.
CORSIA Phase 1: Credits, Compliance, and What Comes Next
Key Takeaways
- CORSIA, the program intended to address international aviation emissions, is currently the world’s largest international compliance carbon market, with approximately 200 million tonnes of eligible emissions units (EEUs) expected to be retired for Phase 1 (2024-2026) compliance.
- Airlines have already begun retiring significant volumes of credits (clean cookstoves and jurisdictional REDD+) toward their Phase 1 obligations ahead of the January 2028 compliance deadline, signaling that the industry is treating CORSIA as a binding policy mandate.
- In addition to the four already approved, a record 25 carbon standards have applied for eligibility to supply credits under Phase 2 (2027–2035), pointing to a diversifying pipeline of credits.
- Legal enforcement of CORSIA at the national level remains uneven. A handful of jurisdictions, including the EU, Japan, Brazil, New Zealand, and Canada, have established compliance regimes, but it is unclear whether other major aviation markets will implement domestic enforcement requirements by 2027.
- As CORSIA matures alongside other compliance and voluntary frameworks, strategic engagement increasingly depends on understanding where eligibility overlaps and where the most value can be found.
Introduction to CORSIA
The Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA) was established and is managed by the International Civil Aviation Organization (ICAO)—a specialized agency of the UN—and provides a compliance mechanism to reduce emissions from international aviation that do not fall within a single country’s contributions to the Paris Agreement. For years, CORSIA generated more commentary than activity—airlines weren’t required to offset a single tonne of CO2 emissions (tCO2) during the pilot phase (2021–2023). That is changing; in early 2026, Singapore Airlines and Japan Airlines retired significant volumes of carbon credits against their Phase 1 (2024–2026) obligations. Increasing authorization announcements showcase the eligible supply steadily entering the market, and 25 carbon standards have applied for Phase 2 (2027–2035) eligibility. As CORSIA becomes an active compliance market, this article explains how the program works, what is driving the current trends, and what to watch as Phase 1 draws to a close.
Who is Covered by CORSIA Phase 1 and Phase 2?
Because emissions from international aviation are not tied to any individual nation, the International Civil Aviation Organization (ICAO) adopted CORSIA in 2016 to complement the Paris Agreement framework and address these emissions. CORSIA applies to international airlines operating flights registered between participating countries.
- During Phase 1, offsetting obligations apply only to routes between the 130 countries that have voluntarily opted in.
- From Phase 2, participation becomes mandatory for all 193 ICAO member states, except for those below the aviation activity threshold or classified as Least Developed Countries, Small Island Developing States, or Landlocked Developing Countries—although they can voluntarily participate.
Several major aviation markets, including China, that are not participating in Phase 1 will be required to do so from 2027.
Offsetting Obligations
Airlines are required to offset the portion of their emissions that exceeds the program’s baseline on routes subject to offsetting. The key input is the annual Sectoral Growth Factor (SGF), which reflects how much annual emissions on covered routes have grown above the baseline (set at 85% of 2019 emissions). In simple terms, each airline's offsetting obligation is calculated by multiplying its CORSIA-regulated emissions by the SGF.
For example, an airline that emits 1 million tCO2 on covered routes in a year when the SGF is 10%, would have an offsetting obligation of 100,000 tCO2. An airline that emits 500,000 tCO2 in the same year would have an obligation of 50,000 tCO2. The actual 2024 SGF was 15.4%, exceeding the baseline and triggering offsetting obligations for the first time since the COVID-induced reduction in international aviation activity.
Beginning in 2033, CORSIA’s offsetting formula combined the SGF with an individual component that accounts for each airline's own emissions growth. The individual weighting starts at 15% in 2033 (with an SGF weighting of 85%) and rises to 45% by 2035 (SGF 55%). This progressively ties each airline’s obligations to its own emissions trajectory rather than sector-wide trends alone.
Airlines can also reduce their obligations by reporting the use of CORSIA Eligible Fuel (CEF). In order to qualify as CEF, Sustainable Aviation Fuel (SAF) must meet ICAO’s certification criteria. Offsetting remains a lower-cost option than sustainable fuel procurement, and CORSIA obligations are currently not influential drivers of CEF/SAF uptake compared to supply mandates, such as ReFuelEU Aviation. However, these dynamics will evolve as CORSIA matures and SAF prices continue to fall.
CORSIA Eligible Carbon Credits: Phase 1 and Phase 2
To determine the eligibility of carbon crediting standards and credits issued under those standards, ICAO's Technical Advisory Body (TAB) reviews applications and recommends approval to the ICAO Council, subject to restrictions on methodologies, vintages, and more granular project elements. Currently, no standard is approved without exclusions. Credits eligible for use under CORSIA are known as Eligible Emissions Units (EEUs).
TAB broadly excludes some project types across standards, including large-scale grid-connected renewable energy projects and most project-level REDD+ activities. The exclusions reflect TAB's assessments of baselines, safeguards, and quantification gaps. However, these assessments are not static; ICAO updates its determinations as the evidence base improves. For example, in 2025, TAB approved certain direct air capture (DAC) and biochar pathways for the first time.
A record 25 carbon standards—certifying projects from emissions avoidance to engineered carbon dioxide removal (CDR)—have applied for Phase 2 eligibility in the 2026 assessment cycle, reflecting the scale of the opportunity. The International Air Transportation Association (IATA) projected a demand of 170–236 million EEUs for Phase 1 alone; developers are eager to serve this growing market. Assessment results are expected in October 2026.
Article 6 and Corresponding Adjustments
The biggest bottleneck for eligible supply has been requirements relating to Article 6.2 of the Paris Agreement. CORSIA requires that EEUs carry a host country Letter of Authorization (LoA) confirming that the host country will not count the underlying mitigation toward its Nationally Determined Contribution (NDC). This prevents double counting between CORSIA and national emission inventories, but it also means eligible supply depends on host country authorization, not just meeting methodological requirements. Authorized credits are called Internationally Transferred Mitigation Outcomes (ITMOs).
To manage the risk that a host country fails to apply the promised corresponding adjustment, projects must secure legally enforceable insurance policies that either provide replacement EEUs or funds to secure them. Several providers have been approved to insure EEUs registered by Gold Standard and Verra.
Insurance requirements do not apply when the host country has already confirmed the corresponding adjustments in its mandatory Paris Agreement reporting. For example, in March 2026, Madagascar submitted a Biennial Transparency Report (BTR) and annual information report that reflect the application of corresponding adjustments to CORSIA-eligible clean cookstoves credits listed on the Verra registry. According to Verra, BTR accounting is the “highest level of assurance” that ITMOs will not be double counted.
The Enforcement Challenge
With the authorization bottleneck loosening, market attention is turning to demand. Critically, ICAO has no direct enforcement power; for CORSIA to work, participating countries must pass laws requiring airlines to comply with its requirements. Under CORSIA rules, airlines must retire their Phase 1 EEUs by January 2028, but most are not yet subject to legal sanctions for failing to comply. Where regulations do exist, it remains unclear whether penalties will be stringent enough to matter, or whether they will be enforced at all.
Where legal enforcement of offsetting requirements does exist, it varies by design. For example, in Brazil, failure to comply attracts a penalty of BRL 50/tCO2 (US$10/tCO2) and an administrative fine. Meanwhile, the Canadian Aviation Regulations impose administrative fines capped at CAD 25,000 (US$18,000) per infraction, but there is no specific fine for each tCO2 not offset. However, the absence of a statutory penalty framework does not necessarily mean compliance will not be enforced. For example, New Zealand manages CORSIA participation through an administrative Memorandum of Understanding with Air New Zealand, rather than a dedicated legal regime (though this will change from 2027). Similar informal arrangements may be more common than the legislative record suggests.
According to 2024 data, US-based airlines account for around 15% of CORSIA-covered emissions. However, there is no indication that the federal government will implement CORSIA penalties under the current administration. It is unclear how non-compliance by a major economy will impact market confidence or enforcement by other governments, but uncertainty about US participation in multilateral climate programs is not new.
What to Watch
- Global enforcement: As Phase 2 approaches, the prospects for CORSIA enforcement in key aviation markets will become clearer. China, which has not participated in the voluntary phase and has raised objections to CORSIA’s design on grounds of fairness, presents an uncertain picture for domestic transposition. The UK government has consulted on a draft legal amendment that would penalise non-compliance for UK airlines at £100/tCO2 (US$130/tCO2), but has not published updates since February 2025.
- EU Emissions Trading Scheme (ETS) update: In July 2026, the European Commission proposed to expand the ETS to address emissions from flights departing the European Economic Area (EEA) to destinations within 5,000 km. To avoid double charging emissions also regulated under CORSIA, the Commission proposed to deduct CORSIA costs from airlines’ ETS obligations. While the Commission flagged concern about the stringency of CORSIA eligibility criteria, the proposed rules would not impact demand for Phase 1 EEUs. Still, it is worth watching for future restrictions on which credits EU airlines can use for CORSIA, whether in Phase 1 or 2.
- Supply financing vehicles: The LEAF Coalition—which purchases credits verified under the CORSIA-eligible ART TREES standard—has signed over US$1.5 billion worth of purchase agreements with host countries. The Forest Carbon Partnership Facility (FCPF) and BioCarbon Fund Initiative for Sustainable Forest Landscapes (ISFL), both CORSIA-approved for Phase 1 in early 2026, have built jurisdictional REDD+ pipelines across dozens of countries. As projects mature, it will be worth watching how issued credits are marketed across compliance and voluntary channels.
Strategic Considerations
Avoided emissions credits dominate early CORSIA supply—and consequently demand—principally from avoided deforestation and clean cooking projects. As there is no regulatory premium for higher-cost CDR, this is not surprising. But as the market matures and supply diversifies, airlines are likely to begin differentiating on geography, co-benefits, and environmental performance. Corporate interest is growing in projects that abate non-CO2 superpollutants, due to their outsized near-term climate impact. As many of these projects are based in countries actively issuing LoAs, this may soon translate into a supply of superpollutant EEUs. Some airlines are reluctant to procure aggressively now, anticipating the upcoming availability of higher-quality credits.
Credits that hold value across multiple frameworks could carry a strategic premium. A credit also eligible for Singapore's carbon tax, Switzerland's CO2 Act, or SBTi claims may offer more durable demand than one tied to a single use case. While specific requirements vary significantly, we are beginning to see convergence around broad principles, such as the need for Article 6 authorization for credits used in compliance markets tied to NDCs. Procurement and project development strategies could begin to favour credits that confer wider market optionality.
The precondition for all of this is policy stability. Longer-term offtake agreements, portfolio strategies, and meaningful investment in project development depend on confidence that CORSIA rules will hold. Efforts to soften emissions regulations in response to energy price shocks are now testing this confidence, from proposed changes to soften the EU ETS to Singapore's deferral of its SAF levy. Tracking price signals, enforcement developments, and authorization trends will be essential for identifying firm demand and where the opportunities lie.
Conclusion
Effective engagement with CORSIA requires more than developing quality projects. It means understanding methodological eligibility requirements, navigating Article 6.2 authorization processes, tracking a network of overlapping national regulations, and staying ahead of a rapidly evolving market landscape. Relae (formerly Carbon Direct) brings together policy, market, and scientific expertise to help clients on all of these fronts.
Frequently Asked Questions
Which carbon credits can airlines use for CORSIA compliance?
CORSIA Eligible Emissions Units (EEUs) must be issued by crediting standards approved by ICAO's Technical Advisory Body. Every approved standard currently has exclusions on certain methodologies and project types, so eligibility is granular rather than blanket. EEUs must also have a host country Letter of Authorization confirming a corresponding adjustment under Article 6.2 of the Paris Agreement.
Is CORSIA actually enforceable?
In all phases, CORSIA obligations are legally binding when a country writes them into domestic law. Countries participating in Phase 1 are expected to do this, but not all have, and enforcement remains uncertain in several key aviation markets (e.g., the United States). Even where enforcement exists, penalty regimes vary significantly in stringency and design.
How does the July 2026 EU ETS proposal affect CORSIA?
The European Commission's proposal to expand ETS coverage to more flights does not reduce demand for CORSIA credits. While it would lead to overlap between flights covered under CORSIA and the ETS, as proposed, airlines could have CORSIA costs effectively deducted from their ETS allowance obligations. However, the Commission has signalled continued scrutiny of CORSIA's effectiveness, which could shape future limits on the credits EU airlines are allowed to use.
Shifting Playbook for Corporate Power Procurement
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s proposed scope 2 revisions would shift many large power buyers from annual renewable energy certificate (REC) accounting to 24/7 hourly matching and reveal a larger emissions gap than most inventories currently report.
- Of all the US grid regions modeled, the emissions gap between annual and 24/7 hourly matching is widest in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the markets where data center load is growing fastest.
- Relae's modeling quantifies the shift from annual to 24/7 hourly matching: serving a 4-gigawatt (GW) data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM, a roughly 800-megawatt premium in PJM that translates directly into cost and siting strategy.
- Closing that gap requires investments in clean, firm generation technologies, like natural gas with carbon capture and storage (CCS), battery storage, and geothermal. The optimal mix varies by market and load profile, which means modeling current and future emissions positions under 24/7 accounting to understand the best procurement options for a specific portfolio.
Annual REC Accounting No Longer Holds at Data Center Scale
For years, large corporate energy buyers have relied on a straightforward approach: purchase renewable energy certificates (RECs) or sign virtual power purchase agreements (VPPAs) to offset market-based scope 2 emissions. Under the current GHG Protocol guidance, these instruments allow companies to claim low or zero emissions regardless of when or where clean energy is actually generated. When corporate clean energy demand was modest, this fueled new renewable project development while aggregate grid emissions were trending down.
That approach worked, until now. Energy demand from data centers and hyperscalers is surging. The Federal Energy Regulatory Commission (FERC) reported more than 50 GW of data center capacity operating in the US at the end of 2025, much of it concentrated in regions where local clean generation cannot keep pace. When corporate clean energy demand was modest, the gap between contractual claims and physical generation was small enough that few questioned this argument. At hyperscaler levels, with load concentrated in a handful of grids, that gap is becoming too large to ignore.
From a climate perspective, well-designed renewable procurement has created real impact by channeling corporate capital into new clean generation, and reducing CO2 emissions anywhere to benefit the climate everywhere. From a grid perspective, power consumption and generation must balance in real time, and the flow of electricity is constrained by the physics of the transmission system. Some regulators, investors, and standard-setters argue that corporate clean energy claims should be grounded in this second, engineering perspective rather than the first. The GHG Protocol's proposed revisions reflect that view, and would force buyers to defend their claims against it.
Relae’s modeling of this 24/7 framework in PJM and ERCOT helps quantify its costs and emissions implications in the markets where the stakes are highest.
What Does 24/7 Hourly Matching Mean for Scope 2 Accounting?
The biggest proposed change to the GHG Protocol’s current Scope 2 Guidance is the move from annual power reporting and matching to a 24/7 approach. Instead of calculating emissions with an annual emissions factor (EF) based on their independent system operator (ISO) or eGRID region for each megawatt-hour (MWh) consumed, companies would need to use hourly-specific EFs.
Companies would still be able to retire RECs to reduce their market-based emissions. However, companies would need to show that these RECs came from clean energy that was generated on the same grid, in the same hour as their facilities consumed power. This makes annual, location-agnostic REC retirement, currently the dominant practice, insufficient for 24/7 market-based accounting.
Both the time restriction (hourly matching) and the location restriction (generation on the same grid as consumption) will make it more difficult for companies to retire RECs. For example, because today's methodology is location-agnostic, a New York-based company can retire RECs from a Texas wind farm (purchased unbundled or via a VPPA) to reduce its reported market-based scope 2 value. This has allowed renewable development to follow the best resource sites rather than the load. Similarly, the time of day that the wind farm generates energy is irrelevant, as long as it is approximately in the same calendar year.
Under the proposed revisions, retiring these RECs would no longer be acceptable for the New York company, since they would fail both location- and hourly-matching requirements. As a result, companies with large REC portfolios today may no longer be able to retire them in order to reduce their market-based scope 2 emissions, if the proposed revisions take effect. These companies may face significant unmatched consumption under 24/7 accounting, especially during evening peaks or grid stress events when fossil-based generation fills the gap.
Annual Matching vs 24/7 Hourly Matching
The figure below illustrates the gap between what a representative large buyer reports under the current annual location- and market-based methodologies, versus what an hourly 24/7 analysis reveals.
Understanding this emissions gap is the essential first step for buyers to make informed decisions about which instruments to retain, which contracts to renegotiate, and where new investment will matter most. If the proposed scope 2 revisions are enacted, companies procuring clean energy will be disincentivized from buying RECs sourced from variable renewables in distant locations, and instead will find it more favorable to invest in same-grid clean, firm generation, such as geothermal, nuclear, and renewables plus storage. RECs from these projects would qualify to be retired against market-based scope 2 emissions under the proposed revisions, where today's distant-wind or off-peak-solar RECs would not.
Where Pressure Is the Highest: ERCOT and PJM
Two markets stand out for projected hyperscaler load growth: PJM, which covers the extended mid-Atlantic region, and ERCOT in Texas. Both are on track to absorb massive increases in data center demand over the next decade, and both expose the limits of annual REC accounting in ways that will be hard to ignore under the new proposed framework.
PJM: 60% Fossil Generation Means High Marginal Emissions
PJM is one of the largest and most complex wholesale electricity markets in the world. Its generation mix still includes 60% coal and natural gas, which means hourly emissions intensity remains high, particularly during evening peaks and grid stress events when fossil generation dominates the dispatch stack.
Buyers relying solely on annual REC retirement may show low market-based scope 2 emissions today, but a 24/7 analysis tells a different story. For PJM-based buyers, this means hourly matching gaps will be largest during evening and overnight hours, when nuclear and storage become disproportionately valuable relative to additional solar.
ERCOT: Solar and Wind Don’t Peak When Demand Does
Texas has abundant wind and solar, with solar generation growing nearly 7x since 2020, but those resources don’t always run when demand peaks. While fossil-based generation has declined since 2020, it still comprises more than half of ERCOT’s generation. Solar dominates midday, wind peaks in the evening, and natural gas fills the gaps, especially during high-demand evenings or extreme weather events.
Buyers with large ERCOT footprints may find that VPPA portfolios, which generate most of their clean energy in off-peak hours, already satisfy the proposed location-based test but fail on hourly matching. Battery storage and demand flexibility could help bridge the gap.
Figure 3 below quantifies that gap in both markets by showcasing the carbon-free energy (CFE) score in ERCOT and PJM, as well as the additional capacity required for a 4 GW load to achieve a 100% CFE target. The CFE score is the share of grid-supplied electricity in a given hour that comes from carbon-free sources, and is the metric the proposed scope 2 revisions would use to evaluate hourly matching. A 100% CFE target means electricity consumption is matched to carbon-free generation in every hour of the year.
In the left panel, a representation1 of each market's 2030 hours are sorted by grid (CFE) score, from the dirtiest hour on the left to the cleanest on the right. Neither grid approaches 100% carbon-free on its own, and the shaded areas represent the unmatched hours a buyer claiming 100% clean energy through annual instruments would actually carry under 24/7 accounting. The gap is the maximum unmatched hours a buyer might be exposed to, as some RECs procured through annual matching may qualify under the new rules, if satisfying the locational and hourly requirements.
The right panel translates that gap into action. The additional co-located clean generation and storage required to serve a representative 4 GW load (roughly 5% of the forecast 2030 C&I load in ERCOT and 4% in PJM) at a 100% hourly CFE target, on top of what the underlying grid already provides.
A few patterns are worth highlighting. First, the left panel confirms that PJM’s grid will still spend materially more hours below 100% carbon-free than ERCOT’s in 2030, a direct consequence of the coal- and gas-heavy generation mix described above. Notably, ERCOT's curve reaches 100% in a meaningful share of hours (windows when the grid is running entirely on carbon-free resources), while PJM's never does, meaning some fossil generation is dispatched in every hour.
Second, the ISO a buyer operates in drives a meaningful difference in build-out: hitting 100% hourly CFE for a 4 GW load takes 9.6 GW of additional capacity in ERCOT and closer to 10.5 GW in PJM. This indicates the advantage of achieving hourly and locational matching in already clean grids, which may influence a buyer choosing where to site new workloads.
Renewables have the largest share of the additional capacity in both markets (5-6 GW), paired with significant long-duration energy storage (~2 GW), while natural gas with CCS provides meaningful clean, firm capacity (~3 GW). ERCOT’s storage share of capacity is slightly larger, reflecting the midday-solar/evening-load mismatch, while PJM leans a bit more on natural gas with CCS, where clean, firm generation does more of the heavy lifting due to lower wind speeds and solar irradiance than Texas.
The right panel also illustrates why clean, firm technologies (natural gas with CCS, advanced nuclear, and enhanced geothermal) are likely to be included alongside renewables and batteries in any serious 24/7 portfolio. With only renewables and batteries, hitting the same target requires about double the total generation and storage capacity. In both markets, targets that look achievable today on an annual REC basis will require materially more capital and a different mix of resources, under 24/7 accounting.
Top Questions Large Power Buyers Need to Model Before the Rules Change
The GHG Protocol revisions are not finalized, and the timing of any mandate remains uncertain, which is exactly why modeling cannot wait.
A useful self-test for any large power buyer is: can your team answer the following today with defensible numbers?
- What is your hourly CFE score across your largest load centers, and how far does it sit from your reported market-based emissions?
- Which of your existing VPPAs and REC contracts hold value under 24/7 accounting, and which become effectively stranded?
- What mix of resources delivers the incremental clean, firm capacity that closes your gap in PJM, ERCOT, or wherever your load is concentrated at the lowest cost?
- If your next gigawatt of load were sited in a different ISO, how would your emissions position change?
Clean firm projects do not appear off the shelf. Advanced nuclear, enhanced geothermal, and natural gas with CCS all carry multi-year development timelines, and corporate offtake agreements are often what get these projects financed in the first place. Buyers who engage now help shape the project pipeline that will be available in their target markets in 2030, and can lock in offtake terms before competition for the most valuable sites tightens. Buyers who wait until the methodology is final will be working with shorter lead times, fewer development partners, and less leverage to specify projects that fit their load profiles and hourly matching needs.
Frequently Asked Questions
What is 24/7 hourly matching, and how does it differ from today's REC accounting?
Today's scope 2 accounting lets companies retire renewable energy certificates (RECs) from any grid, at any time of year, to offset their emissions. The GHG Protocol's proposed 24/7 hourly matching would require RECs to come from clean generation on the same grid, in the same hour a facility consumes power, making most of today's location-agnostic RECs ineligible for market-based accounting.
Why are PJM and ERCOT under the most pressure from this shift?
Both markets are absorbing the fastest-growing data center load in the country, and both still lean on fossil generation to meet demand outside peak renewable hours. PJM's generation mix is 60% coal and gas, while ERCOT's solar and wind often don't peak when demand does, so buyers in these markets face the largest gaps between their annual REC claims and their actual hourly carbon-free energy score.
How much additional clean capacity does it take to close the gap?
Relae's modeling finds that serving a 4 GW data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM. That capacity mix leans on renewables and long-duration storage in both markets, with natural gas with CCS playing a larger role in PJM, where wind and solar resources are weaker.
What should power buyers do before the GHG Protocol revisions are finalized?
Start modeling now. Buyers should know their hourly carbon-free energy score, understand which existing VPPAs and REC contracts hold value under 24/7 accounting, and identify the lowest-cost mix of clean, firm resources that closes their gap. Clean firm projects like advanced nuclear, enhanced geothermal, and natural gas with CCS take years to develop, so buyers who engage early have more influence over the project pipeline and better offtake terms.
Modeling the 24/7 Emissions Gap with Relae
For large power buyers assessing what the proposed GHG Protocol revisions mean for their power procurement portfolio, Relae's Advanced Power Emissions Analysis solution models the gap between current market-based reporting and what 24/7 accounting would reveal—by market, load profile, and technology stack.
Reconciliation Bill Dramatically Shifts the Clean Energy Landscape
Key Takeaways
- Accelerated phase-out schedules for key clean energy and decarbonization tax credits will shorten the runway for project development, which could stall or cancel projects.
- Urgency is paramount, and qualified projects should expedite construction and operational timelines to secure eligibility for existing credits.
- A more complicated policy landscape requires concerted effort to navigate, including with the support of policy professionals.
Reconciliation Rolls Back Much of the IRA
On Friday, July 4, 2025, the President signed a sweeping reconciliation bill, H.R. 1, that will add at least $3.3 trillion to the national debt and marks a pivotal, contentious moment for US clean energy policy. The law was enacted through the complex legislative process known as budget reconciliation, requiring only a simple majority of votes in the House and Senate. The new law substantially modifies or terminates many of the Inflation Reduction Act of 2022 (IRA)'s clean energy incentives and has extensive implications for the economic viability of American energy and manufacturing projects.
In the Senate, three Republicans crossed party lines to vote against the bill, requiring Vice President JD Vance to break the tie. In the House, only two Republicans broke ranks to vote against final passage. While some of the more complex provisions of the bill, such as new foreign entity of concern (FEOC) restrictions, will require more time to fully assess, we've prepared a rapid run-down of key alterations to IRA incentives for carbon management, hydrogen, and clean fuel technologies.
What Is the 2025 Reconciliation Bill?
While the 2025 reconciliation bill is staggering in length, scope, and severity, containing provisions to cut Medicaid, reduce nutrition assistance, raise the debt limit, and cut taxes primarily for the wealthy, some of the most drastic sections of the bill modify tax incentives and other public funding for clean energy and emissions reductions.
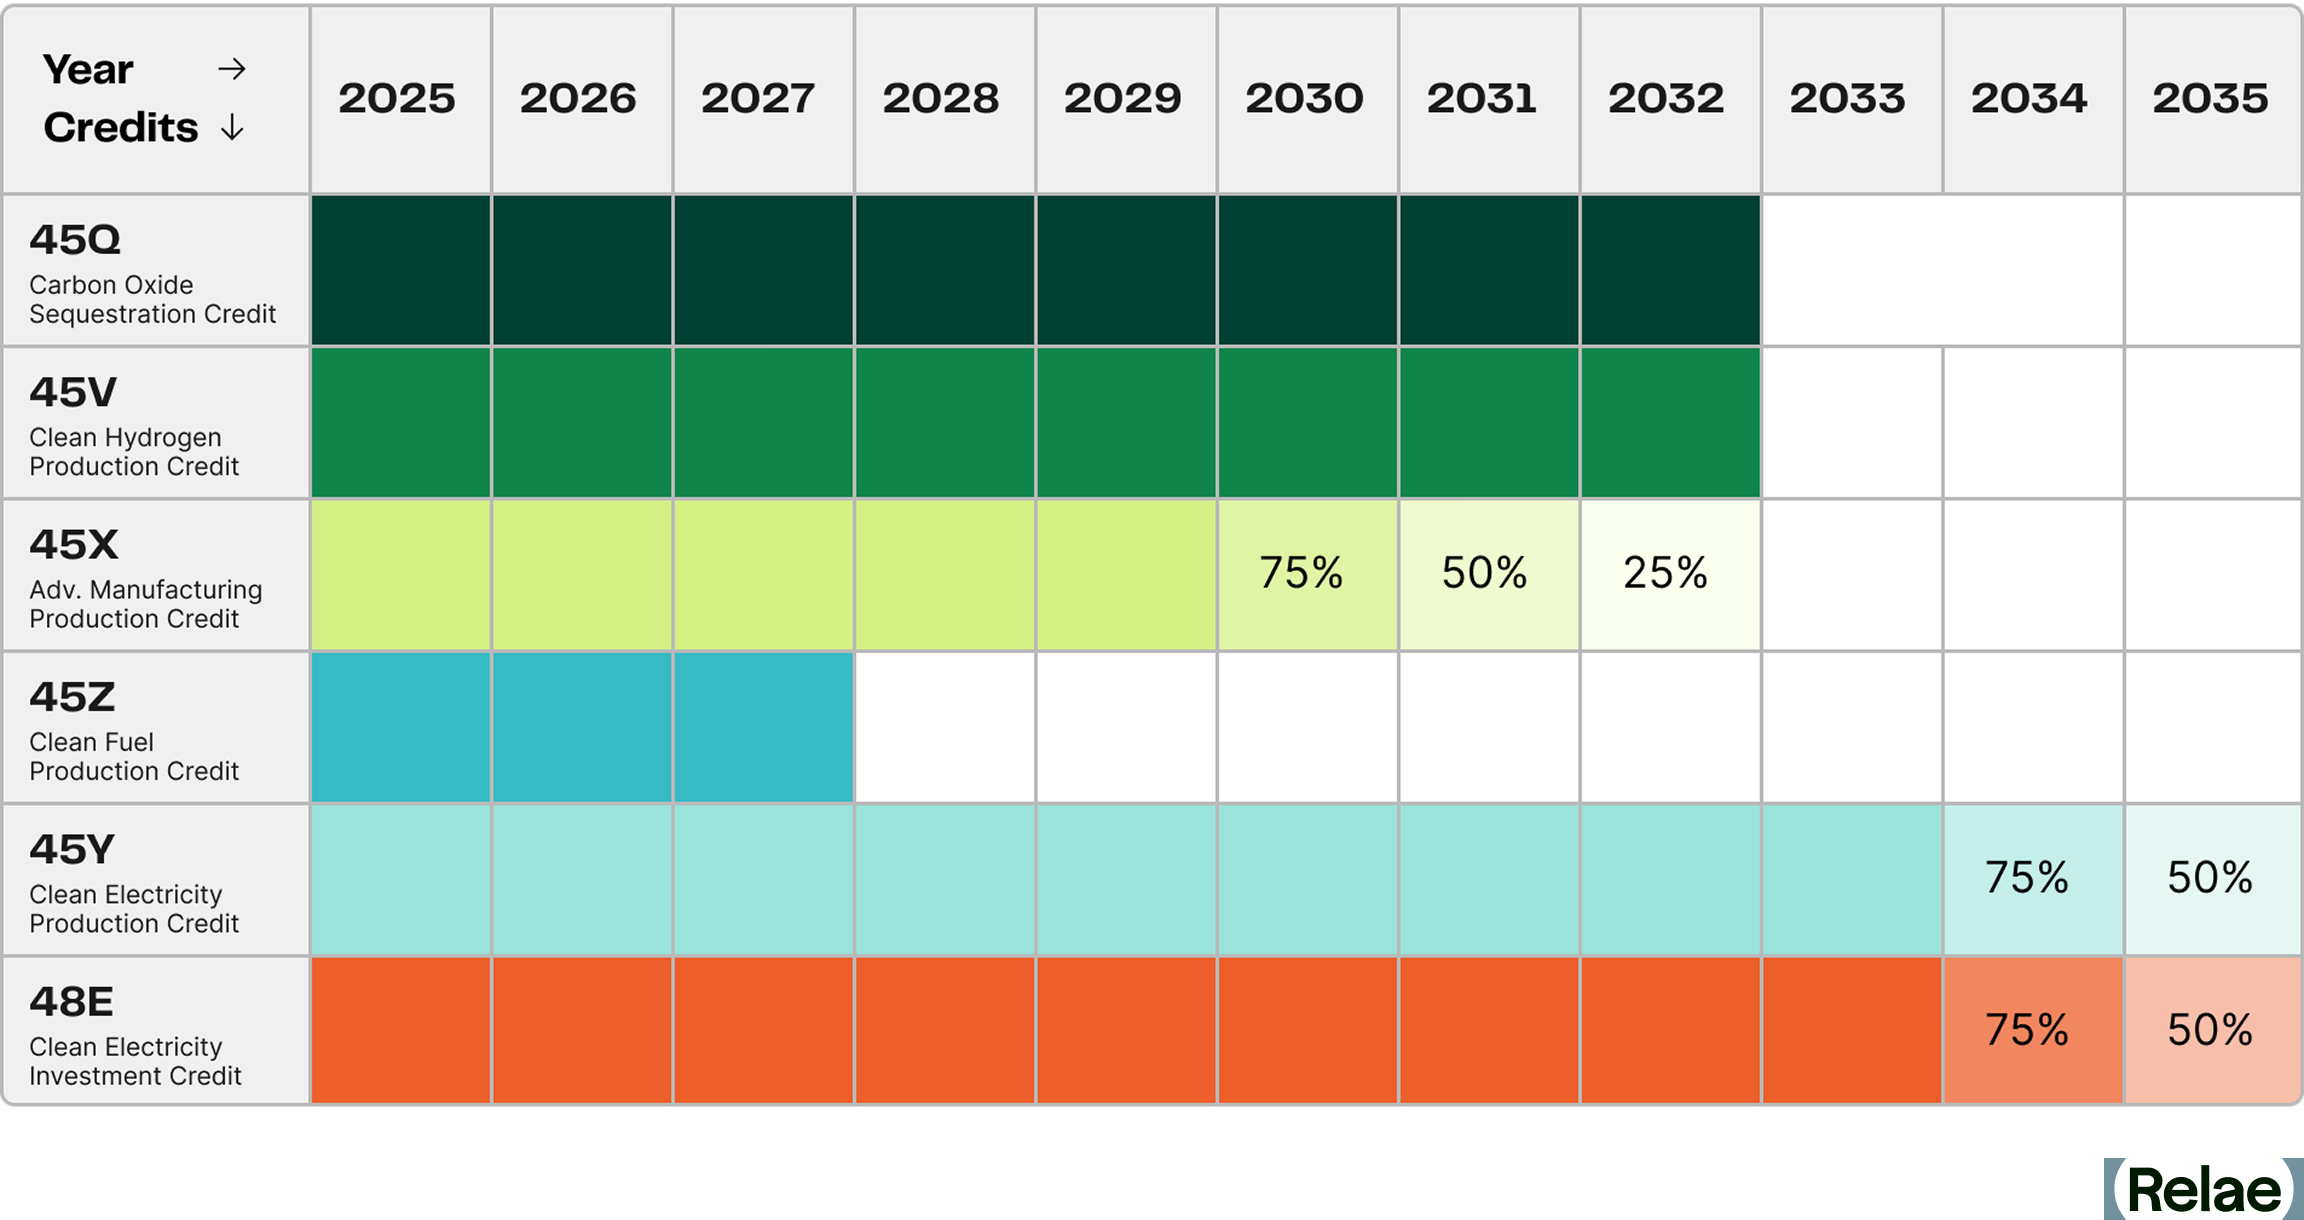
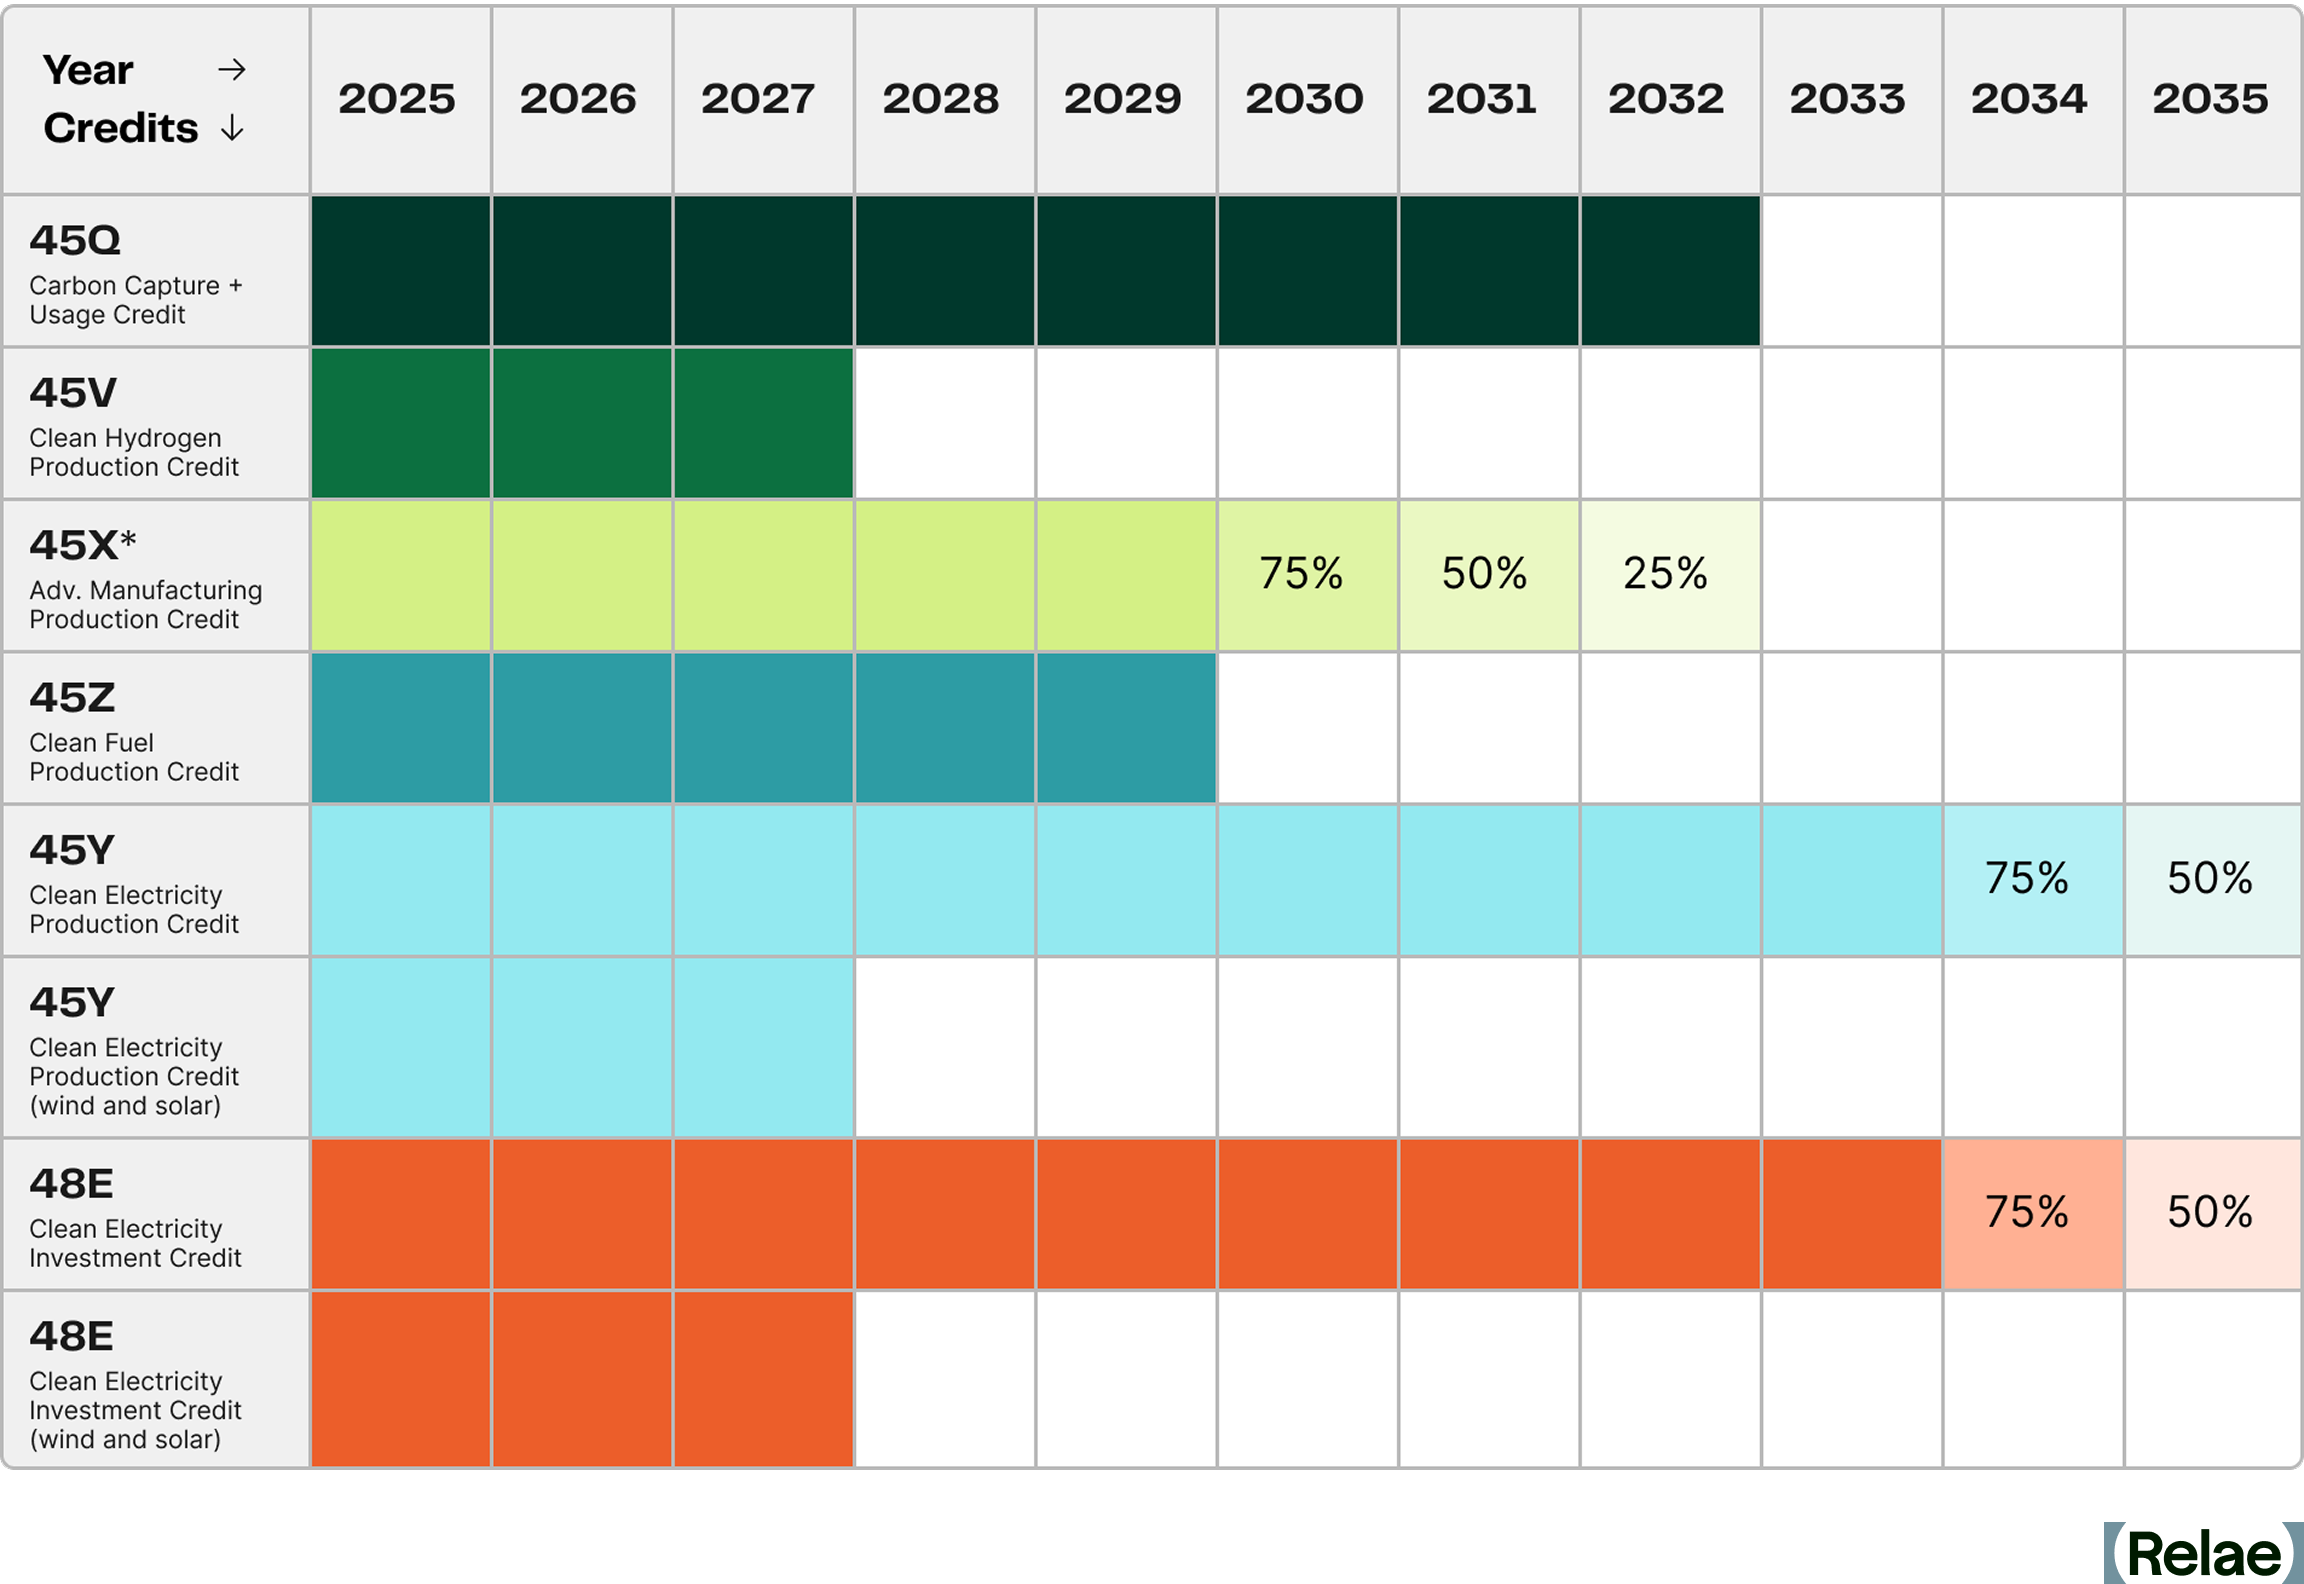
Many of the incentives to deploy clean energy that were created or enhanced under the IRA will be phased out early or repealed altogether. Credits with accelerated phase-out schedules include the newly created 45Y clean electricity production tax credit, which will no longer support wind or solar projects after 2027, and the 45V credit for clean hydrogen production for which projects must now commence construction before Jan 1, 2028 (moved up from Jan 1, 2033).
Since the passage of the reconciliation package, there has been active litigation on several provisions, including an order from a federal district court to vacate IRS guidance that would have prohibited certain wind and solar projects from securing safe harbor. The table below provides a detailed breakdown of key changes to major tax credits between the original IRA, the draft that moved through Committees in the House, and the final text that was passed by the Senate and signed into law.
Major Tax Credit Changes in the Reconciliation Law
How FEOC Restrictions Threaten Clean Energy Supply Chains
Many clean energy tax credits include ambiguous language restricting projects connected to FEOC, complicating supply chains and creating new problems for developers of clean energy projects. The law also introduces a complex matrix of new definitions, such as "Prohibited Foreign Entities," which includes both "Specified Foreign Entities" and "Foreign-Influenced Entities."
The FEOC restrictions embedded in the reconciliation bill represent a seismic shift for clean energy developers. These new rules, designed to limit the influence of Covered Nations (China, Russia, North Korea, and Iran), will disqualify projects from receiving tax credits if they source components, minerals, or intellectual property from entities tied to these nations. In other instances, the partial ownership or investment of an entity with financial ties to a Prohibited Foreign Entity may also disqualify a project from qualifying for tax credits.
This FEOC language matters for developers and investors because of the resulting global supply chain disruptions, investment uncertainty, and compliance burdens. The clean energy sector is deeply reliant on global supply chains, especially for solar panels, batteries, and wind components, industries where China currently dominates. The IRA intended to counter this by moving the manufacturing and production of these supply chains to the US. Project developers must now thoroughly review their supply chains and capital providers, and may need to quickly pivot to compliant resources.
In February 2026, the IRS released interim guidance on the FEOC provisions to provide safe harbor guidance for clean energy manufacturing, investment, and production credits to help taxpayers gauge whether material assistance was provided by a prohibited foreign entity.
Other Major Rollbacks to the IRA
Beyond clean energy tax credits, the reconciliation package also repeals and rescinds many other IRA provisions. This includes a full rescission of all unobligated IRA appropriated balances at the Department of Energy's Loan Programs Office, and several other programs, including:
- The Tribal Energy Loan Guarantee Program
- Greenhouse Gas Reduction Fund
- Transmission Facility Financing
A complete list of rescissions of energy-related funding is outlined in Sections 60001-60024 and 50402 of the law. These rescissions represent tens of billions of dollars in lost climate investments made under the IRA, which would have provided funds to state, local, and Tribal governments, federal agencies, non-profits, and commercial project developers to reduce emissions and update critical infrastructure.
What Can Project Developers and Other Companies Do?
Developers will need to act quickly to meet updated commence construction and place into service requirements, though circumstances are technology specific (e.g., safe harbor updates to 48E and 45Y). Tax credits generally have advanced commence construction and operational deadlines, resulting in a strong first-movers advantage. Companies should also review their supply chains and revise equipment and material procurement sourcing plans as necessary to address restrictions presented in the reconciliation bill.
An executive order from President Donald Trump issued on July 7 will further complicate how companies proceed. In the EO, the President directs his administration to "strictly enforce the termination of […] 45Y and 48E […] for wind and solar facilities." The Administration will likely issue extremely strict interpretations of "commence construction" clauses and FEOC requirements in forthcoming tax credit guidance issued by the Treasury Department, though these moves are quite likely to face litigation.
The new restrictions being proposed by the Administration, including specific details on FEOC, qualified equipment, commence construction, and other reporting requirements, will require additional guidance from the IRS and provide an opportunity for engagement through public comment. It is important that impacted companies weigh in during these public comment periods, not only to help inform and influence the final rules issued by the Administration, but also to build an administrative record that could support litigation efforts to strike down the final rules.
Staying Ahead of Policy Changes
Given the rapidly shifting landscape of energy policy, it's paramount that companies stay abreast of the latest changes and dedicate resources to understanding how they may be affected. Policy professionals, including the experts at Relae (formerly Carbon Direct), can support organizations as they engage in the regulatory process, anticipate and prepare for new legislation, and navigate the requirements to access essential tax credits and incentives. Even under new constraints, expert guidance can help maximize impact and minimize disruption.
Frequently Asked Questions
How does the reconciliation bill change the timelines for major clean energy tax credits?
Most clean energy tax credits saw their windows shortened relative to the original IRA:
- The 45Y and 48E credits now terminate entirely for wind and solar facilities placed in service after December 31, 2027, with a separate phase-down (75% in 2034, 50% in 2035, 0% after) for other technologies.
- The 45V clean hydrogen credit's "commence construction" deadline moved from December 31, 2032 to December 31, 2027.
- The 45Z clean fuel credit now ends on December 31, 2029 (versus 2027 in the original IRA, but bonuses for SAF have been removed and new emissions-calculation methods favor corn ethanol).
- Notably, the 45Q carbon capture credit saw little change and retained transferability, with credit values for enhanced oil recovery and utilization raised to match secure geological storage.
What are the FEOC restrictions, and why do they matter so much for developers?
FEOC ("Foreign Entity of Concern") restrictions disqualify projects from tax credits if they source components, minerals, or intellectual property from entities tied to China, Russia, North Korea, or Iran. Even partial ownership or investment ties to a "Prohibited Foreign Entity" can trigger disqualification. The definitions are complex and still being clarified through IRS guidance, meaning developers need to review supply chains and capital providers carefully and may need to pivot to compliant sourcing.
What should project developers do now in response to these changes?
Developers should move quickly to meet the earlier "commence construction" and "placed in service" deadlines, since credits now benefit early actors. This includes reviewing and potentially restructuring supply chains and procurement plans to address FEOC restrictions, and closely monitoring forthcoming IRS/Treasury guidance.
Why Behind-the-Meter Power Emissions Belong in Scope 2
Key Takeaways
- Larger power users are securing behind-the-meter (BTM) power to bypass grid constraints, pairing data centers with third-party-owned generation assets that deliver electricity through a private line rather than the grid.
- BTM power arrangements can create confusion about electricity emissions classification: the power users neither own the generating asset nor purchase electricity from the grid, leading some to misclassify those emissions as scope 3 in their corporate GHG inventories. But the GHG Protocol's Corporate Standard is clear: BTM electricity emissions belong in scope 2.
- Misclassifying BTM emissions can create reputational and regulatory risk. Relae can help organizations get this right before the contract closes.
Why Large Power Users Are Turning to Behind-the-Meter Power
Large power users are consuming more electricity due to data center growth and are looking to add capacity faster than the grid can support, which is having a direct impact on corporate emissions. For example, between 2020 and 2024, Microsoft’s location-based scope 2 emissions rose 130%, and Google’s rose 92%, driven almost entirely by soaring electricity demand from AI infrastructure.
To bypass grid congestion and long interconnection queues, many are turning to behind-the-meter (BTM) power. It’s a pragmatic solution to a real supply problem, but it’s opening an urgent carbon accounting question: when the BTM asset is owned and operated by a third party, where should we account for those emissions?
There has been some confusion that has resulted in companies pursuing an interpretation that would place those emissions in scope 3. The GHG Protocol’s Corporate Standard says otherwise, and the stakes of getting this wrong are high.
What Is Behind-the-Meter Power Generation?
Behind-the-meter refers to electricity generated on the power consumer’s side of the utility meter, bypassing the grid, and typically located on or near the site where the power is consumed.
In most BTM arrangements for a data center, a third-party developer builds and operates a generation asset, such as natural gas, geothermal, or renewable energy, and delivers electricity directly to the facility through a private transmission line. There is no utility meter, no grid connection, and no standard energy invoice.
This structure allows companies to access large, reliable blocks of power without waiting years for grid interconnection approvals. Since the company does not own or operate the generation asset and is not purchasing electricity through a conventional utility relationship, this arrangement has created some uncertainty around how to account for the associated emissions.
Can BTM Electricity Emissions Be Classified As Scope 3?
In this scenario, no. The GHG Protocol's Corporate Standard is unambiguous: BTM electricity emissions belong in scope 2, not scope 3. Yet, some companies have been confused about this classification.
There is broad agreement that since the power users do not own or operate the generating asset, those emissions do not belong in scope 1. Divergence starts when we consider that the company is purchasing BTM power, i.e., not from the grid. Since no electricity is acquired from the grid, some argue that rather than accounting for these emissions in scope 2, they are better placed in scope 3, category 8: emissions from leased assets.
The appeal is obvious for BTM power consumers. Scope 3 emissions face less scrutiny from investors, auditors, and regulators who focus most of their attention on scopes 1 and 2. Classifying BTM emissions as scope 3 would reduce near-term pressure to act. However, the GHG Protocol is unambiguous in its stance.
What the GHG Protocol Actually Says
The GHG Protocol’s Scope 2 Guidance states that “organizations must quantify emissions from the generation of acquired and consumed electricity, steam, heat, or cooling (collectively referred to as ‘electricity’).” The method of delivery, whether grid or BTM, does not change the classification.
If a company consumes electricity from a BTM source, the emissions from generating that electricity belong in scope 2. Section 5.4 of the Scope 2 Guidance addresses BTM power generation directly: “the company with operational or financial control of the energy generation facility reports those emissions in scope 1, following the operational control approach, while the consumer of the energy reports the emissions in scope 2.”
This resolves the question completely. The emissions sit in scope 1 if the company has operational or financial control of the asset, or in scope 2 if a third party controls it.
The GHG Protocol’s Corporate Value Chain (Scope 3) Accounting and Reporting Standard reinforces this conclusion. “Category 8 includes emissions from the operation of assets that are leased by the reporting company in the reporting year and not already included in the reporting company’s scope 1 or scope 2 inventories.”
Because BTM electricity emissions are captured by the Scope 2 Guidance, the scope 3 category 8 does not apply.
Get the Accounting Right Before the Contract Closes
The GHG Protocol is unambiguous: behind-the-meter electricity emissions belong in scope 2 for companies that consume, but do not control the generating asset. This means that BTM contract terms are crucial to determining how the emissions will be classified, since the GHG Protocol assigns scope based on who holds operational or financial control of the generating asset.
Companies that move fast on BTM capacity without understanding this distinction risk locking in a scope 1 or scope 2 obligation they didn't anticipate or building a reporting strategy around a scope 3 interpretation the GHG Protocol doesn't support. This can become a reputational or even a regulatory liability that is far harder to address after the contract is signed.
[cta]
Carbon Removal, Reduction, and Avoidance Credits Explained
Key Takeaways
- Trust in carbon credits remains low. In part, this is because many mistakenly treat every credit type as interchangeable.
- Reduction, removal, and avoidance credits are verified against fundamentally different baselines, so credit quality must be judged based on type and project specifics, never with one blanket standard.
- The Integrity Council for the Voluntary Carbon Market's Core Carbon Principles now give buyers an independent bar to check against, including 44 methodologies approved across 13 eligible crediting programs, as of August 2026.
- Removal credits still make up only 5–6% of the market, even as compliance-driven demand accelerates, per our 2026 State of the Voluntary Carbon Market report.
Three Types of Carbon Credits: Reduction, Removal, and Avoidance
A carbon credit is a mechanism that allows one party to compensate another for their carbon mitigation activities. Based on their net emissions impact, there are three types of carbon credits: reduction, removal, and avoidance.
- Reduction credits reflect activities that decrease greenhouse gas emissions, compared to prior practices.
- Removal credits reflect activities that remove carbon dioxide already present in the atmosphere and oceans and lock it away for decades, centuries, or millennia.
- Avoidance credits reflect activities that prevent greenhouse gases from being emitted in the first place. For all three types, credits are assessed and issued by measuring or estimating how much carbon is reduced, removed, or avoided as a result of a credit purchase and its associated activities.
While credits are assessed in different ways depending on the type, one of the most important indicators of quality is a project's baseline - the emissions that would be present in a business-as-usual scenario, without action being taken to reduce, remove, or avoid them. Project developers use baselines as a means of comparison to assess the net emissions impact of a project.
- Baselines must be accurately set and data-driven.
- Emissions impacts of a project must be correctly calculated against its baseline.
Reduction, removal, and avoidance projects involve very different activities and, for some types of projects, it may be more challenging to establish an accurate baseline. However, without accurate baselines, climate impacts cannot be reliably determined.
Across the voluntary carbon market, Reduction credits represent roughly 20% of the purchases. Removal credits represent roughly 5% of the purchases. The remainder, roughly 75%, are avoidance credits.
Carbon Reduction Credits
Carbon reduction must drive the majority of our push to net zero, but translating carbon reduction activities into carbon credits that can be purchased is challenging. Examples of activities represented by carbon reduction credits include reducing fossil fuel use by improving fuel efficiency, or programs that reduce the methane that is generated from farms or municipal waste processing.
Reduction credits are measured and quantified against the baseline emissions of an existing technology or process. Some reduction credits are easy to track and measure, such as efficiency investments or destruction of fugitive methane. Other projects are more complex. For example, low-emission cookstove projects in developing regions rely on tracking patterns of cookstove use and quantifying emission factors for various fuel and stove combinations, both of which are hard to do. The result, as studies have shown, sometimes leads to overcrediting in reduction projects.
Superpollutant Credits
One class of reduction credit, superpollutant credits, has garnered recent attention. These credits involve the reduction of non-CO2 greenhouse gases with very strong radiative forcing, such as methane, nitrous oxides, or fluorinated gases like chlorofluorocarbons. These are not a substitute for CO2 removal, but can provide rapid and profound reductions at modest cost. Many different kinds of superpollutants exist in today’s market, worth roughly $60M today. Recent purchases by tech companies and others have highlighted the potential of these reduction credits.
Another class of reduction credit, transition credits, involves the deliberate early closure of emitting assets like coal-fired power plants or heavy manufacturing facilities. Early efforts by governments, banks, and companies around the world under the Just Energy Transition Partnership agreement jump-started transition credits as a concept at COP26. The Kinetic Coalition, in partnership with many groups including Relae, has launched work to bring transition credits to market with several pilot efforts, including closing a coal plant in the Philippines 10 years early.
Carbon Removal Credits
Projects that remove carbon come from a diverse set of solutions, from nature-based solutions like reforestation, to hybrid solutions like biochar, to engineered solutions such as direct air capture and storage. Roughly 5–6% of credits on the voluntary carbon market today are classified as removals, up from roughly 3% a few years ago.
Carbon removal baselines are determined differently depending on whether a project uses an engineered, hybrid, or nature-based solution. For engineered removals, the baseline is zero, because no carbon removal was occurring in the absence of the project. The credited removal will be the difference between the quantity of carbon removed and any emissions that occur to facilitate the removal (determined through a carbon credit life cycle assessment). Baselines for hybrid and nature-based removals can be more challenging. In natural systems, changes in carbon stocks created by removals must be measured and approximated over time, and creditable removals represent the additional carbon removed by the intervention relative to the baseline (e.g., fallow land versus a reforestation project).
Another important consideration for carbon removal credits is project durability, a measure of the likely duration of carbon storage. Stored carbon can re-enter the atmosphere either through deliberate actions (e.g., deforestation) or accidental ones (e.g., wildfires). Nature-based removals are especially vulnerable to being re-released and are usually considered less durable (i.e., stored for less than 50 years). In contrast, engineered solutions offer high durability (i.e., stored for hundreds to thousands of years), and hybrid removals also offer durability periods that are typically longer than those of nature-based removals.
While less durable, nature-based solutions are effective, cost-effective, and widely available today. They made up over 95% of all carbon removal credits issued in 2025. Engineered and hybrid solutions are more expensive and scarce but offer longer durability. Prices of engineered carbon removal are likely to fall with innovation and increased market participation, but are currently much higher than most nature-based credits. With SBTi's finalized Corporate Net-Zero Standard V2.0, this balance is likely to shift. Large companies must now purchase removal credits covering 1–100% of scope 1, scope 2, and scope 3 emissions between 2035 and their net-zero year, with an explicit focus on more durable CO2 removal credits.
Carbon Avoidance Credits
Examples of carbon avoidance include avoiding deforestation that would result in the release of carbon dioxide into the atmosphere or clean energy projects that avoid the release of emissions from burning fossil fuels in possible facilities. This can be confusing, since many avoided credits are called reduction credits, as is the case with projects under the Reducing Emissions from Deforestation and Forest Degradation (REDD+) framework. Avoidance credits make up roughly 75% of certified credits on the voluntary carbon market today - an overwhelming majority - in part due to high availability and low price.
Avoiding emissions is an important goal with numerous environmental, climate, community, and other benefits. Relae works with clients and customers across industries on developing and implementing strategies to avoid emissions within their value chain. However, there are significant challenges with the way that many carbon avoidance credits are created.
- Carbon avoidance credits are based on an estimate of the emissions that might have existed had a project not been funded. Because it is impossible to observe what might have happened in the absence of a project, carbon avoidance estimates are determined by considering historic data and contextual information. Statistical models can be used to create a presumed baseline that represents what would have happened in the absence of the project.
- Because the baseline is not observed in an avoided emissions project, there is uncertainty in calculating the number of carbon credits it produces. If the baseline is not set accurately, a project can overcredit. While the lack of a directly observed and measured baseline means avoidance credits will always have some degree of uncertainty, high-quality avoidance projects present compelling evidence to support their baselines, greatly reducing uncertainty.
New datasets, statistical techniques, and methodologies are providing opportunities for developing avoidance credits with more certainty. Three REDD+ methodologies have now cleared the Integrity Council for the Voluntary Carbon Market (ICVCM) assessment for its Core Carbon Principles (CCPs), a concrete sign that credit quality standards for avoidance projects are maturing.
Defining and Standardizing Quality in the Voluntary Carbon Market
Carbon credits are intended to reduce, remove, or avoid emissions. They pay for an environmental service that must be delivered. Companies working to generate climate benefits through credit purchases must grapple with the differences and uncertainties of credit quality to ensure that the intended benefits are realized.
While high-quality credits exist for all types of projects, a rich understanding of the differences in methodologies, geographies, physics, and ecology is required to identify high-quality projects and understand varied certainty, durability, and risk terms. Identifying high-quality carbon projects demands extensive and project-specific diligence beyond carbon market certification.
Our own diligence work reveals that high-quality projects can be hard to find. Fewer than 10% of the carbon removal projects we assessed for our 2026 State of the Voluntary Carbon Market report met our quality criteria. This diligence work now has an additional, independent backstop. As of August 2026, the ICVCM has approved 44 methodologies across 13 programs, as eligible for its CCP label, including ACR, Gold Standard, and VCS. For buyers, considering projects that are CCP-eligible should be used as a first filter—not a substitute for project-level diligence, but representing a legitimate floor.
While realized emissions impacts may be difficult to prove in some cases, it is important to remember that some projects provide additional co-benefits. REDD+ projects, for example, may have a positive impact on conservation and biodiversity, and cookstove projects may offer clear human health and social welfare benefits. However, these benefits should be assessed separately from carbon reduction, removal, or avoidance benefits.
Frequently Asked Questions
What's the difference between a carbon credit and a carbon offset?
A carbon credit represents one verified tonne of emissions reduced, removed, or avoided. A carbon offset describes how a buyer uses that credit, typically to counterbalance emissions it has not yet accounted for. The credit itself does not change type based on how it's claimed.
Which type of carbon credit—reduction, removal, or avoidance—is highest quality?
No single type is inherently highest quality. Each project, regardless of type, is verified against a defined baseline. Quality depends on how rigorously that specific baseline was set and how well the project meets other quality criteria. Removal credits from engineered sources have the most straightforward baseline (zero), and avoidance credits carry the most baseline uncertainty by design, but these are only one determinant of credit quality.
Do carbon removal credits automatically meet the ICVCM’s Core Carbon Principles?
No. The ICVCM assesses methodologies and programs, not individual projects. If a project uses a methodology that is eligible for the CCP label, this can be a useful floor but is not a guarantee of high quality.
How does SBTi's near-term removal mandate change which credits I should buy now?
SBTi's finalized Corporate Net-Zero Standard V2.0 doesn't require removal purchases until 2035, but it sets the ramp now (i.e., 1% of scope 1, scope 2, and scope 3 emissions in 2035, scaling to 100% by the net-zero year). This means the highest-durability removal supply that is scarcest and most in demand today is the same supply that many companies will need later. The SBTi guidelines are still changing, so buyers and project developers must track them closely.



