How to Fix Load Forecasting for the AI Era
Key Takeaways
- Accurate load forecasting is needed to distinguish and prioritize real demand, align capital deployment, and reduce delays in bringing new power capacity online. Traditional load forecasting was built for predictable, gradual demand growth, not for the scale, uncertainty, and dynamic behavior of data centers.
- The system-level fix to data-center load forecasting requires probabilistic, more frequent, category-specific methods paired with mandatory data standards and policy alignment. Together, these give planners visibility into the range of possible futures and the likelihood of each.
- Without that fix, today's forecasts conflate real demand with speculative submissions, reducing accuracy. Inaccurate forecasting in either direction is expensive: underbuild adds friction to economic development; overbuild risks raising retail rates. Both can erode public trust in planning.
- Behind-the-meter generation (BTM) and load flexibility can help achieve speed-to-power in the near term. Just 1% data-center flexibility could unlock 100 GW—more than the entire US nuclear fleet.
Load Growth Is Increasing, Uncertain, and Concentrated
For two decades, US electricity demand was flat. Utilities, transmission planners, and corporate buyers built their planning models around that reality. Then AI workloads changed it.
AI load growth is large, uncertain, and concentrated in major power markets. While load forecasting projections vary across studies, the trajectory is clear: electricity demand is scaling faster than the bulk power grid was designed to handle. Accurate load forecasting is needed to distinguish and prioritize real demand, align capital deployment, and reduce delays in bringing new power capacity online.
On April 30, 2026, Relae (formerly Carbon Direct) hosted a Trellis Group panel on load forecasting in the AI era. Panelists included Derya Eryilmaz, PhD, Vice President of Power Commercialization at Relae; John Miller, Director of Transmission Policy at the Corporate Energy Buyers Association (CEBA); Daniel Padilla, Strategy and Business Development Lead at Emerald AI; and Sam Hodas, Head of US Government Affairs at National Grid. Jake Mitchell, Director of Climate Tech Innovation at Trellis Group, moderated.
The conversation explored where load forecasts fail, what they cost, how to fix them, and near-term solutions to overcome grid constraints. Here is what the panel found.
What Is Load Forecasting?
Load forecasting is the practice of predicting how much electricity will be consumed across a region, at what times, and under what conditions. It informs the major capital and procurement decisions on the grid: where to build transmission, how much generation to procure, what capacity to bid into wholesale markets, and how corporate buyers secure clean, firm power.
Long-term forecasts inform multi-year decisions about transmission and generation. Short-term operational forecasts inform real-time grid operations and trading. The two often sit in separate workflows, but short-term operational forecasts should feed into long-term system planning to improve accuracy as demand patterns shift.
The Bulk Power Grid Is Under Strain
Large power users face constraints on clean, firm power, transmission capacity, multi-year interconnection queues, and aging infrastructure. The strain is most acute in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the two US markets expected to see the most significant load growth. Each constraint raises the cost of getting load forecasts wrong.
Hodas from National Grid describes the operational reality on the utility side: aging infrastructure inherited from a different demand era. “We’ve got transmission lines that are 70 to 100 years old in New York and Massachusetts, some of the oldest in the country, still in operation.” Replacing or upgrading that infrastructure requires investment, and ratepayers are already pressed.
Why Today’s Load Forecasts Fail
Traditional load forecasting was built for predictable, gradual demand growth, not for the scale, uncertainty, and dynamic behavior of data centers.
Most utilities and Independent System Operators (ISOs) produce load forecasts on annual or biannual cycles. They aggregate submissions from individual customers, run that data through a deterministic single-peak load estimate against a single capacity scenario, and pass the consolidated forecast up to regional planners. Regional Transmission Organizations (RTOs) roll those bottom-up utility forecasts into a regional view.
This worked when demand was flat and predictable. It no longer works with nonlinear growth driven by data centers. Eryilmaz from Relae identifies key structural limitations.
Four Structural Limitations to Traditional Forecasting Methods
- Over-stating and double-counting. Data centers bid into multiple regions while shopping for power, inflating regional forecasts and blurring the line between real and hypothetical demand—the speculative-load problem.
- Deterministic models (vs probabilistic models). Most planning runs a single peak load estimate against a single capacity scenario, missing the geographic concentration and uncertainty inherent in integrating large loads into the system.
- Aggregated submissions. Utilities report large loads as a single block of gigawatts, with no resolution into workload type, ramp schedule, or operational shape. Planners reverse-engineer peak-demand assumptions rather than measure them.
- Infrequent cadence. Annual or biannual forecasts cannot catch an 80% queue reduction or a multi-gigawatt addition between cycles.
The Speculative-Load Problem
The core challenge in load forecasting is distinguishing real versus hypothetical load. While data center electricity demand is projected to grow by 13-27% annually through 2028, the majority of the projects in the data center queue may not materialize, inflating regional load forecasts.
American Electric Power's Ohio utility (AEP Ohio) introduced a tariff requiring data centers to put up firm financial commitments before getting in line for grid connection. Its interconnection queue dropped from 30 gigawatts to 5.6 gigawatts. More than 80% of the submitted load was speculative: projects that disappeared once commitment became required.
ERCOT shows the same overstatement problem on a larger scale. Roughly 225 gigawatts of data center demand sits in the ERCOT queue against a historic system peak of 85 gigawatts. Texas Senate Bill 6 introduced similar financial obligations for new loads, but those rules apply only to interconnections after 2025, and the cleanup of speculative demand has not yet materialized.
The speculative-load problem shows up in interconnection times. An average new project in PJM can wait 4 to 5 years to become operational. Some of that delay is a real backlog. The rest comes from the inability to distinguish real submissions from speculative ones.
As Eryilmaz puts it, “Load forecasting is actually the center of all of these problems. It is a tool to help planners make the right investment decisions.”
The Cost of Inaccurate Forecasting
As Miller from CEBA notes, “A single misforecasted project can swing a transmission plan by hundreds of megawatts.” Significant inaccuracies can erode public trust in the planning process in two main ways. Underbuilding adds friction to economic development and can limit corporate access to clean power markets. Conversely, overbuilding risks raising retail rates if capacity remains underutilized.
The goal is to achieve right-sized infrastructure investment. When planning aligns with actual large load growth, it can be net beneficial to retail rates. By spreading fixed costs across more usage, significant new demand can put downward pressure on the rates via the “denominator effect.”
On the other hand, forecasting variability can distort capacity procurement and interconnection queue prioritization. When load forecasts spike upward, grid operators like PJM have to scramble to buy additional electricity capacity on short notice. These emergency procurements lock in major dollar commitments on the basis of unstable forecast numbers.
PJM, Midcontinent Independent System Operator (MISO), and Southwest Power Pool (SPP) have also reshaped their interconnection queues to make room for new large loads, but those queue priorities depend on the same forecasts that are unreliable in the first place.
“There is no substitute for good backbone regional transmission planning,” Miller says. “Full stop. That is the enabler of all of the load growth that we’re talking about.”
BTM Generation and Load Flexibility: A Near-Term Bridge
Hyperscalers’ need for power is way faster than that of utilities and RTOs. Generation alone cannot scale fast enough to meet this new demand, and hyperscalers need speed-to-power.
As Eryilmaz frames it, behind-the-meter generation and load flexibility are interim solutions to the timing mismatch between data center urgency and the grid's slower build cycles. BTM generation and flexibility work differently:
- BTM is power generated on the data center's side of the utility meter, bypassing grid interconnection entirely. The structure gives operators large, reliable blocks of power without waiting years for grid approval.
- Load flexibility is the demand-side approach. A data center modifies its grid draw in response to grid signals. In practice, that can mean curtailing compute workloads during stress events, pre-cooling facilities ahead of a heat wave, drawing from on-site batteries or generators, or shifting workloads to data centers in less-constrained regions.
The Value of Load Flexibility
Relae’s power system modeling quantifies the dollar value of load flexibility in ERCOT. Load flexibility can eliminate forced load shedding risk, even at 40 gigawatts of data center buildout, preventing $5.5 billion in annual consumer welfare losses by curtailing an average of 5% of demand for under 1% of operating hours.
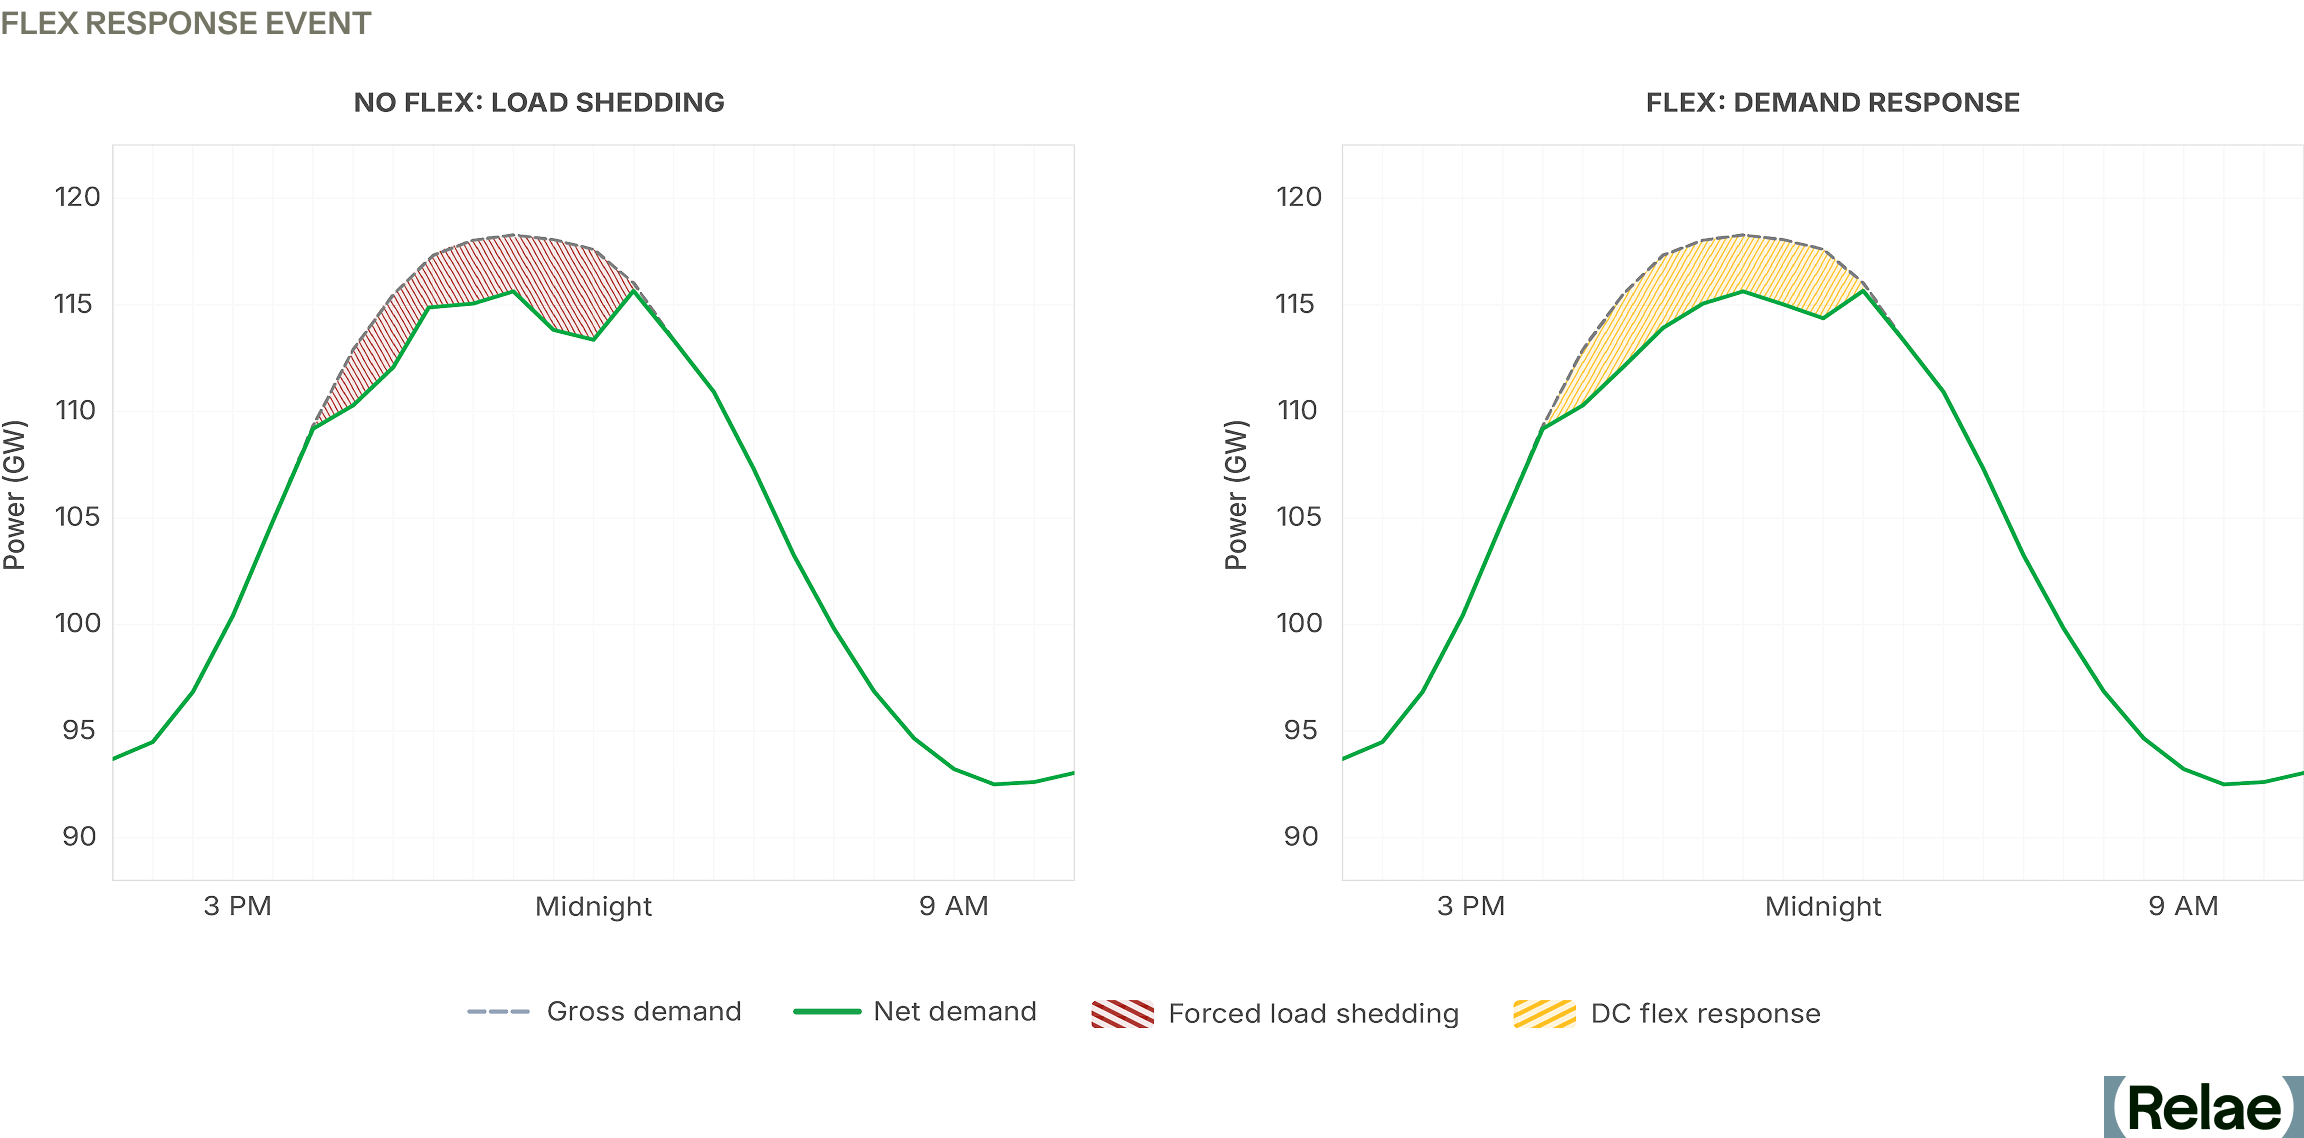
Padilla from Emerald AI reinforces the scale and value of load flexibility: “With just 1% flexibility, we can unlock 100 gigawatts of data centers across the US. That’s more than the entire US nuclear fleet.”
Silicon Valley Power, a municipal utility, is the first US utility to tie flexibility to interconnection speed: flexible data centers get connected faster. NVIDIA, EPRI, Digital Realty, and PJM are partnering on the Aurora AI Factory, the first purpose-built reference design for flexible AI data centers.
But standardized policy for load flexibility is lagging. Padilla highlights this challenge: “Today, if a data center wants to be flexible, they have nowhere to point. We need standardized tariffs, interconnection rules, and product definitions for large loads that reward them with upsizing interconnection in response to flexibility.”
Flexibility Takes Many Forms, but it Isn't Universal
Flexibility means accepting brief, predictable downtime, and some workloads can't tolerate it. Hospital systems and mission-critical enterprise applications need 99.999% uptime, the "five nines" standard. As Padilla puts it: "99.9% uptime, with brief and predictable curtailments, is plenty" for most AI workloads. That distinction determines which data centers can participate in flexibility programs.
Miller points out that compute-level flexibility is not always feasible. BTM batteries and virtual power plants (VPPs) are among the alternatives that can offset what data centers withdraw when the grid is stressed, even at facilities whose compute workloads cannot pause directly.
Better Load Forecasting: The Longer-Term Fix
While BTM generation and load flexibility can help address near-term speed-to-power, the longer-term fix is improving load forecasting methods and the standardization of data provided by the data centers themselves.
Eryilmaz outlines three technical shifts for better load forecasting:
- Embed short-term operational forecasting into long-term planning. Short-term spikes, weather risk, and reserve considerations carry direct implications for multi-year capital decisions. The line between operations and planning breaks down when growth is nonlinear.
- Replace deterministic models with probabilistic methods. Risk metrics like loss of load hours (expected hours per year that demand exceeds supply) and expected unserved energy (total expected energy shortfall) measure both how much capacity the system has and the conditions under which it might fall short. The North American Electric Reliability Corporation (NERC) has suggested both metrics as part of its reliability framework.
- Forecast load by category. Treating all data center load as a single block hides the differences in load profiles, operational schedules, and ramp-up timing that drive system planning.
Policy Alignment
Technical forecasting improvements only scale with policy alignment, and Miller proposes a two-part fix:
On the top-down side, RTOs need authority to take an independent view of utility-submitted forecasts. They should require milestones, such as firm financial commitments and secured financing, before counting a submitted load against the regional forecast.
On the bottom-up side, state regulators set the rules that govern how individual utilities prepare their forecasts. Large load tariffs play a big role in how utility-level forecasts come together. Federal and state authorities need to row in the same direction. Hodas frames the same alignment from the utility side: “Grid investment unlocks economic growth, but for us to make those investments, we need regulatory certainty.”
Standardizing Large-Load Data
The Federal Energy Regulatory Commission (FERC) has since moved: in June 2026 it issued show cause orders directing six RTOs and ISOs—CAISO, ISO-NE, MISO, NYISO, PJM, and SPP—to revise or justify their large-load interconnection rules, and in July 2026 it directed NERC to develop computational-load reliability standards and registration criteria by the end of the year. Both are useful first steps. But as Eryilmaz argues, voluntary disclosure has not closed the gap.
The industry cannot meaningfully compare ISO forecasts when each utility submits load data in different shapes (e.g., using different methods and data standards) on different schedules. Mandatory submission requirements and published methodologies, applied consistently across utilities, ISOs, and state regulators, are the only path to forecasts whose components are actually comparable.
Getting Load Forecasting Right Starts Now
The system-level fix to improving forecasting is through probabilistic, category-specific methods paired with data standardization and policy support. Together, these account for the scale, uncertainty, and dynamic behavior of data center loads, and give planners visibility into the range of possible futures and the likelihood of each.
All forecasts will be wrong to some degree, but as Miller puts it, “It's ultimately not about having a perfect prediction. It's about baking in methods to account for uncertainty.” These system-level improvements won't eliminate errors entirely, but they will minimize them, leading to more confident investment decisions and a grid better prepared for what's ahead.
Frequently Asked Questions
What is load forecasting, and why is it harder now with AI data center loads?
Load forecasting predicts how much electricity a region will consume, when, and under what conditions—the basis for where to build transmission, how much generation to procure, and how corporate buyers secure clean, firm power. It was designed for two decades of flat, gradual demand growth. Data center load is none of those things: it is large, geographically concentrated, arrives in gigawatt blocks with no disclosed operating shape, and can be withdrawn as quickly as it appeared.
What is speculative load in an interconnection queue, and how do planners tell it apart from real demand?
Speculative load is capacity requested by projects that may never be built — often the same data center bidding into several regions at once while shopping for power, which counts the same gigawatts more than once. The tested filter is a financial commitment: when AEP Ohio required firm commitments before queue entry, the utility's reported data center pipeline fell from about 30 GW to roughly 5.7 GW. Milestone requirements, independent RTO review of utility submissions, and mandatory data standards are the tools planners have.
Is load flexibility proven and scalable today, or still emerging?
The modeling case for load flexibility is strong; the commercial case is still early. Duke's Nicholas Institute found the 22 largest US balancing authority areas could absorb roughly 76–126 GW of new load if it accepts modest curtailment, and Relae's ERCOT modeling shows demand response eliminating forced load shedding risk at 40 GW of data center buildout, avoiding $5.5 billion in annual consumer welfare losses. What is still missing is the market plumbing—standardized tariffs, interconnection rules, and product definitions—so a data center willing to be flexible has somewhere to sign up.
What should a company look for when evaluating a region's load forecast?
Ask whether the forecast is probabilistic or a single deterministic peak, how often it is refreshed, and whether large loads are broken out by category and operating shape rather than reported as one block of gigawatts. Then ask what milestone or financial commitment a project must clear before its megawatts count toward the forecast. A forecast that cannot answer those three questions cannot tell you how much of the queue ahead of you is real.
[cta]
Power & Energy
Relae provides independent advisory for large corporate buyers, power providers, and infrastructure investors making high-stakes decisions about clean firm power, grid constraints, data center energy optimization, and long-term investment strategy. Our insights help you evaluate solutions that can be deployed reliably, responsibly, and affordably, so you can navigate an evolving energy landscape with confidence.
Ready to Navigate What Comes Next?


Rhianna Hixon
Rhianna Hixon

Rhianna Hixon brings over eight years of content strategy expertise to Relae, where she leads the company's content program, translating Relae's scientific expertise into resources that equip decision-makers to act with confidence.
At Relae, Rhianna has built and scaled a content program spanning power and energy, environmental markets, natural capital, and climate strategy. She partners with subject matter experts across the organization to turn rigorous science into compelling narratives that rank, resonate, and drive action.
Before joining Relae, Rhianna spent five years at a B2B digital marketing agency, where she pioneered the content marketing department and developed full-funnel SEO and content strategies for 35+ B2B companies. She holds a B.A. in Environmental Studies and Communications from UC Santa Barbara, a foundation that shapes both her subject matter depth and her approach to climate storytelling.
Academic Achievement Award, University of California, Santa Barbara
Dean's Honors, University of California, Santa Barbara
What to Read Next
Inside NERC’s Level 3 Alert on Data Center Loads
Key Takeaways
- On May 4, 2026, the North American Electric Reliability Corporation (NERC) issued a rare Level 3 “Essential Actions” Alert in response to repeated events in which 1,000+ megawatts (MW) of computation load dropped off the bulk power system in seconds, leading to major grid stability issues.
- The pattern has since escalated: on July 22, 2026, a transmission fault in Ashburn, Virginia took more than 3 GW of data center load offline in seconds—roughly 3% of PJM demand at the time.
- NERC also published Reliability Guidelines that push the same concerns into long-term planning, explicitly recommending resource adequacy models that capture firm vs. flexible load, behind-the-meter resources, and AI training operating windows.
- For transmission operators and balancing authorities, the releases compel new scrutiny of how computational loads affect stability and resource adequacy. For hyperscalers and other large loads, those assessments now sit on the critical path: if operators cannot show through advanced modeling that they can integrate the new loads, interconnection and buildout plans stall.
- Meeting the bar takes advanced grid modeling at multiple time and spatial scales, from sub-second stability through long-horizon capacity and resource adequacy, to evaluate the role of large load portfolios considering demand response, storage, and co-located generation.
Why Grid Frequency Matters for Large Loads
When we turn on the lights or charge our phones, it’s easy to forget that electricity travels through the power grid as alternating current. Sixty times a second—far faster than our eyes can see—the flow of electricity alternates back and forth along the wires making up both the transmission and distribution parts of the North American grid.
Power generation equipment and most large industrial loads are designed to work with this 60 Hertz (Hz) alternating flow and must be synchronized precisely to this rhythm to function. Grid synchronization is so important that it can even have geopolitical implications.
For some electrical equipment, getting out of sync with the grid’s frequency can lead to malfunctions or even physical damage and destruction. That’s why grid-connected equipment is protected by circuits that automatically disconnect from the grid (“trip offline”) if the grid frequency begins to deviate by even one percent. For minor equipment, this is easily managed. However, when large amounts of generation or load trip offline quickly, it can lead to rapidly cascading grid blackouts affecting tens of millions of people with costs in the billions.
Grid operators pay extremely careful attention to factors that could cause grid frequency to deviate. The grid’s frequency stays near 60 Hz only when total power generation and consumption (load) are closely balanced. If load suddenly drops below generation, physical rotating generators like gas turbines can begin to speed up, making grid frequency rise.
This becomes particularly dangerous when large grid-connected loads all trip offline simultaneously because of minor frequency deviations or other factors. If these loads are large enough, they can trigger a cascading sequence of rising frequency and further equipment and generator trips, potentially causing a complete “grid collapse” blackout. The North American grid may be getting closer to this scenario.
What Triggered NERC’s Highest-Urgency Alert
Data center load drops are now a documented grid stability threat. On May 4, 2026, NERC issued a rare Level 3 “Essential Actions” Alert—its highest-urgency notification—in response to a pattern of customer-initiated load reductions in which 1,000+ MW of computational load (data centers) dropped off the bulk power system (tripped offline) in seconds. These were “customer-initiated” because protection circuits at data centers detected problems with grid-supplied power and automatically disconnected to protect their sensitive computing equipment from electrical damage.
Paired with a new Reliability Guideline on emerging large loads, the alert highlights the urgent need to better understand the potential for these events to cause grid instability or even blackouts. Together, these two documents reset the bar for the detailed grid modeling and planning needed for any utility, independent system operator (ISO), or hyperscaler with material data-center growth in its footprint.
Customer-Initiated Load Reductions
A customer-initiated load reduction (CILR) is an event in which a large load, most often a data center, AI training facility, or crypto miner, abruptly and without warning reduces or disconnects its electricity draw from the grid in response to a frequency or voltage disturbance that the grid’s internal protection circuits interpret as unsafe.
Compute-based loads like AI data centers are particularly sensitive to changes in the expected voltage and frequency from grid-supplied power, and their automated electrical protection systems tend to react more quickly and at smaller deviations than conventional industrial, commercial, and residential loads.
NERC has documented multiple events of 1,000+ MW since 2022, with reductions occurring in seconds, much faster than real-time operators can respond. This makes these events a significant risk to grid frequency stability that is distinct from more traditional load loss events that occur at a smaller scale or over slower timescales, allowing grid operators to take action to compensate.
How the Alert Reshapes Grid Interconnection
For utilities and ISOs, the alert and guideline raise the standard of evidence required to connect computational loads safely to the grid. Modeling assessments now sit on the critical path for large load interconnection decisions, and the same studies will increasingly inform reserve margin, transmission, and dispatch program designs.
For hyperscalers and other large loads, the consequence is direct. Plans that assume firm service without supporting analysis will face longer queues and tougher interconnection conditions. Buildout timelines now depend on whether utilities and ISOs can show, through stability and resource adequacy modeling, that the system can absorb the load and respond safely to its disturbances.
For storage developers, particularly long-duration and fast-responding assets, these events elevate the reliability value of rapid response and load-shifting resources. The same grid modeling improvements that capture flexible load behavior also surface storage's full reliability contribution.
For flexibility platforms, the same modeling work that satisfies NERC's expectations unlocks faster, cheaper interconnection. Demand response, large-load shifting, and co-located dispatch coordination are now both technical and commercial enablers.
A Higher Bar for Power Analysis
These pressures point to a higher bar for power analysis at multiple time and spatial scales, for utilities and the large loads they serve.
At sub-second to second timescales, electromagnetic transient (EMT) models capture fast electrical switching and the uninterruptible power supply behavior that determines whether a data center stays connected during a disturbance (“rides through”). The alert asks for these models to be more detailed, validated against actual equipment, and shared between large loads, transmission owners, and planners.
At seconds-to-minutes, dynamic stability simulation covers system frequency response, voltage recovery, and oscillation behavior after disturbances. NERC now expects annual stability studies and explicit load drop contingencies in planning files.
At hours-to-years, capacity expansion and production cost modeling determine whether the system has enough resources, in the right places, with the right flexibility, to keep up with computational load growth. NERC’s May 2026 Large Loads Reliability Guideline is most explicit at this scale, calling for resource adequacy studies that represent firm and flexible load components, behind-the-meter resources, AI training operating windows, and probabilistic scenarios across many weather, load, and outage combinations on a network-aware footprint.
Rising to the Challenge
Since the alert was issued, its expectations have begun hardening into rules. Registered entities were required to report to NERC on their progress against the seven Essential Actions by August 3, 2026, and on July 16, 2026, FERC directed NERC to go further: to develop mandatory reliability standards for computational loads and revise its registration criteria, with the first standards and Rules of Procedure changes due December 31, 2026 and a second-phase work plan due March 1, 2027. NERC's Large Loads Action Plan anticipates new "Computational Load Owner" and "Computational Load Operator" registered entity types alongside the first three computational load standards.
The practical consequence is that the modeling described above is no longer only good planning practice: utilities, ISOs, hyperscalers, and other large loads should expect the data-sharing, study, and commissioning expectations in the alert to return as auditable requirements, and should build the capability before the compliance deadline rather than after it.
Frequently Asked Questions
What is a NERC Level 3 Alert, and what does it require?
A Level 3 “Essential Actions” Alert is the most urgent of NERC's three alert levels, reserved for risks that need immediate, documented industry response. The May 4, 2026 alert directed registered entities to take seven essential actions on computational load—covering modeling, system studies, commissioning, protection, fault recording, and direct operational communication with large load operators. Written responses were due to NERC by August 3, 2026.
Why do data centers disconnect from the grid during minor disturbances?
Data centers run voltage- and frequency-sensitive computing equipment protected by automatic transfer systems that switch to on-site UPS or backup generation the moment grid power looks abnormal. Those protection settings trip faster, and at smaller deviations, than conventional industrial loads, so a fault lasting milliseconds can move a gigawatt of demand off the system in seconds. Because the shift is customer-initiated, grid operators get no warning and no time to rebalance.
How does the alert change interconnection for hyperscalers and other large loads?
Modeling assessments now sit on the critical path for large load interconnection. A plan that assumes firm service without stability and resource adequacy analysis behind it will face longer queues and tougher interconnection conditions, because the utility or ISO has to be able to show the system can absorb the load and respond safely to its disturbances. In practice, buildout timelines are now tied to someone else's study queue.
What modeling do utilities and large loads need to meet NERC's expectations?
Electromagnetic transient (EMT) models validated against actual equipment for sub-second ride-through behavior; dynamic stability simulation with explicit load-drop contingencies for seconds-to-minutes frequency and voltage response; and capacity expansion and probabilistic resource adequacy modeling that separates firm from flexible load, represents behind-the-meter resources, and reflects AI training operating windows. The paired Reliability Guideline is most explicit about the last of these.
Electricity Emissions Accounting: GHG Protocol and LCA Explained
Key Takeaways
- The GHG Protocol Corporate Standard and life cycle assessment (LCA) offer distinct frameworks for measuring electricity-related emissions, one for annual corporate reporting and one for detailed cradle-to-grave analysis, leading to different emissions results.
- Renewable energy certificates (RECs) are accepted under the GHG Protocol's market-based approach to reduce reported scope 2 and scope 3: category 3 emissions, but are not explicitly addressed in ISO LCA standards, where transparent disclosure is essential.
- Using both the GHG Protocol and LCA together, while recognizing their different scopes, boundaries, and purposes, can give organizations a more complete and strategic view of electricity-related emissions and decarbonization opportunities.
Electricity-Related Emissions: Why Measurement Methods Matter
In the era of AI-driven power demand, scrutiny over electricity-related emissions is intensifying. With this increased attention comes growing confusion around how to measure and report these emissions. The GHG Protocol Corporate Standard and life cycle assessment (LCA) are two widely used methods for measuring and reporting electricity-related emissions, but each follows its own complex and often incompatible, set of rules.
This piece will examine the differences between these approaches and answer common questions such as:
- What are the differences between the GHG Protocol Corporate Standard and LCA?
- Why do they result in different emissions for the same type and amount of electricity?
- Can renewable energy contracts reduce electricity-related emissions under both methods?
- When should you use each approach?
Both the GHG Protocol Corporate Standard and LCA are powerful tools that, if used in complementary ways, can help organizations identify emissions hotspots and develop more effective pathways for decarbonization.
What Is the GHG Protocol Corporate Standard?
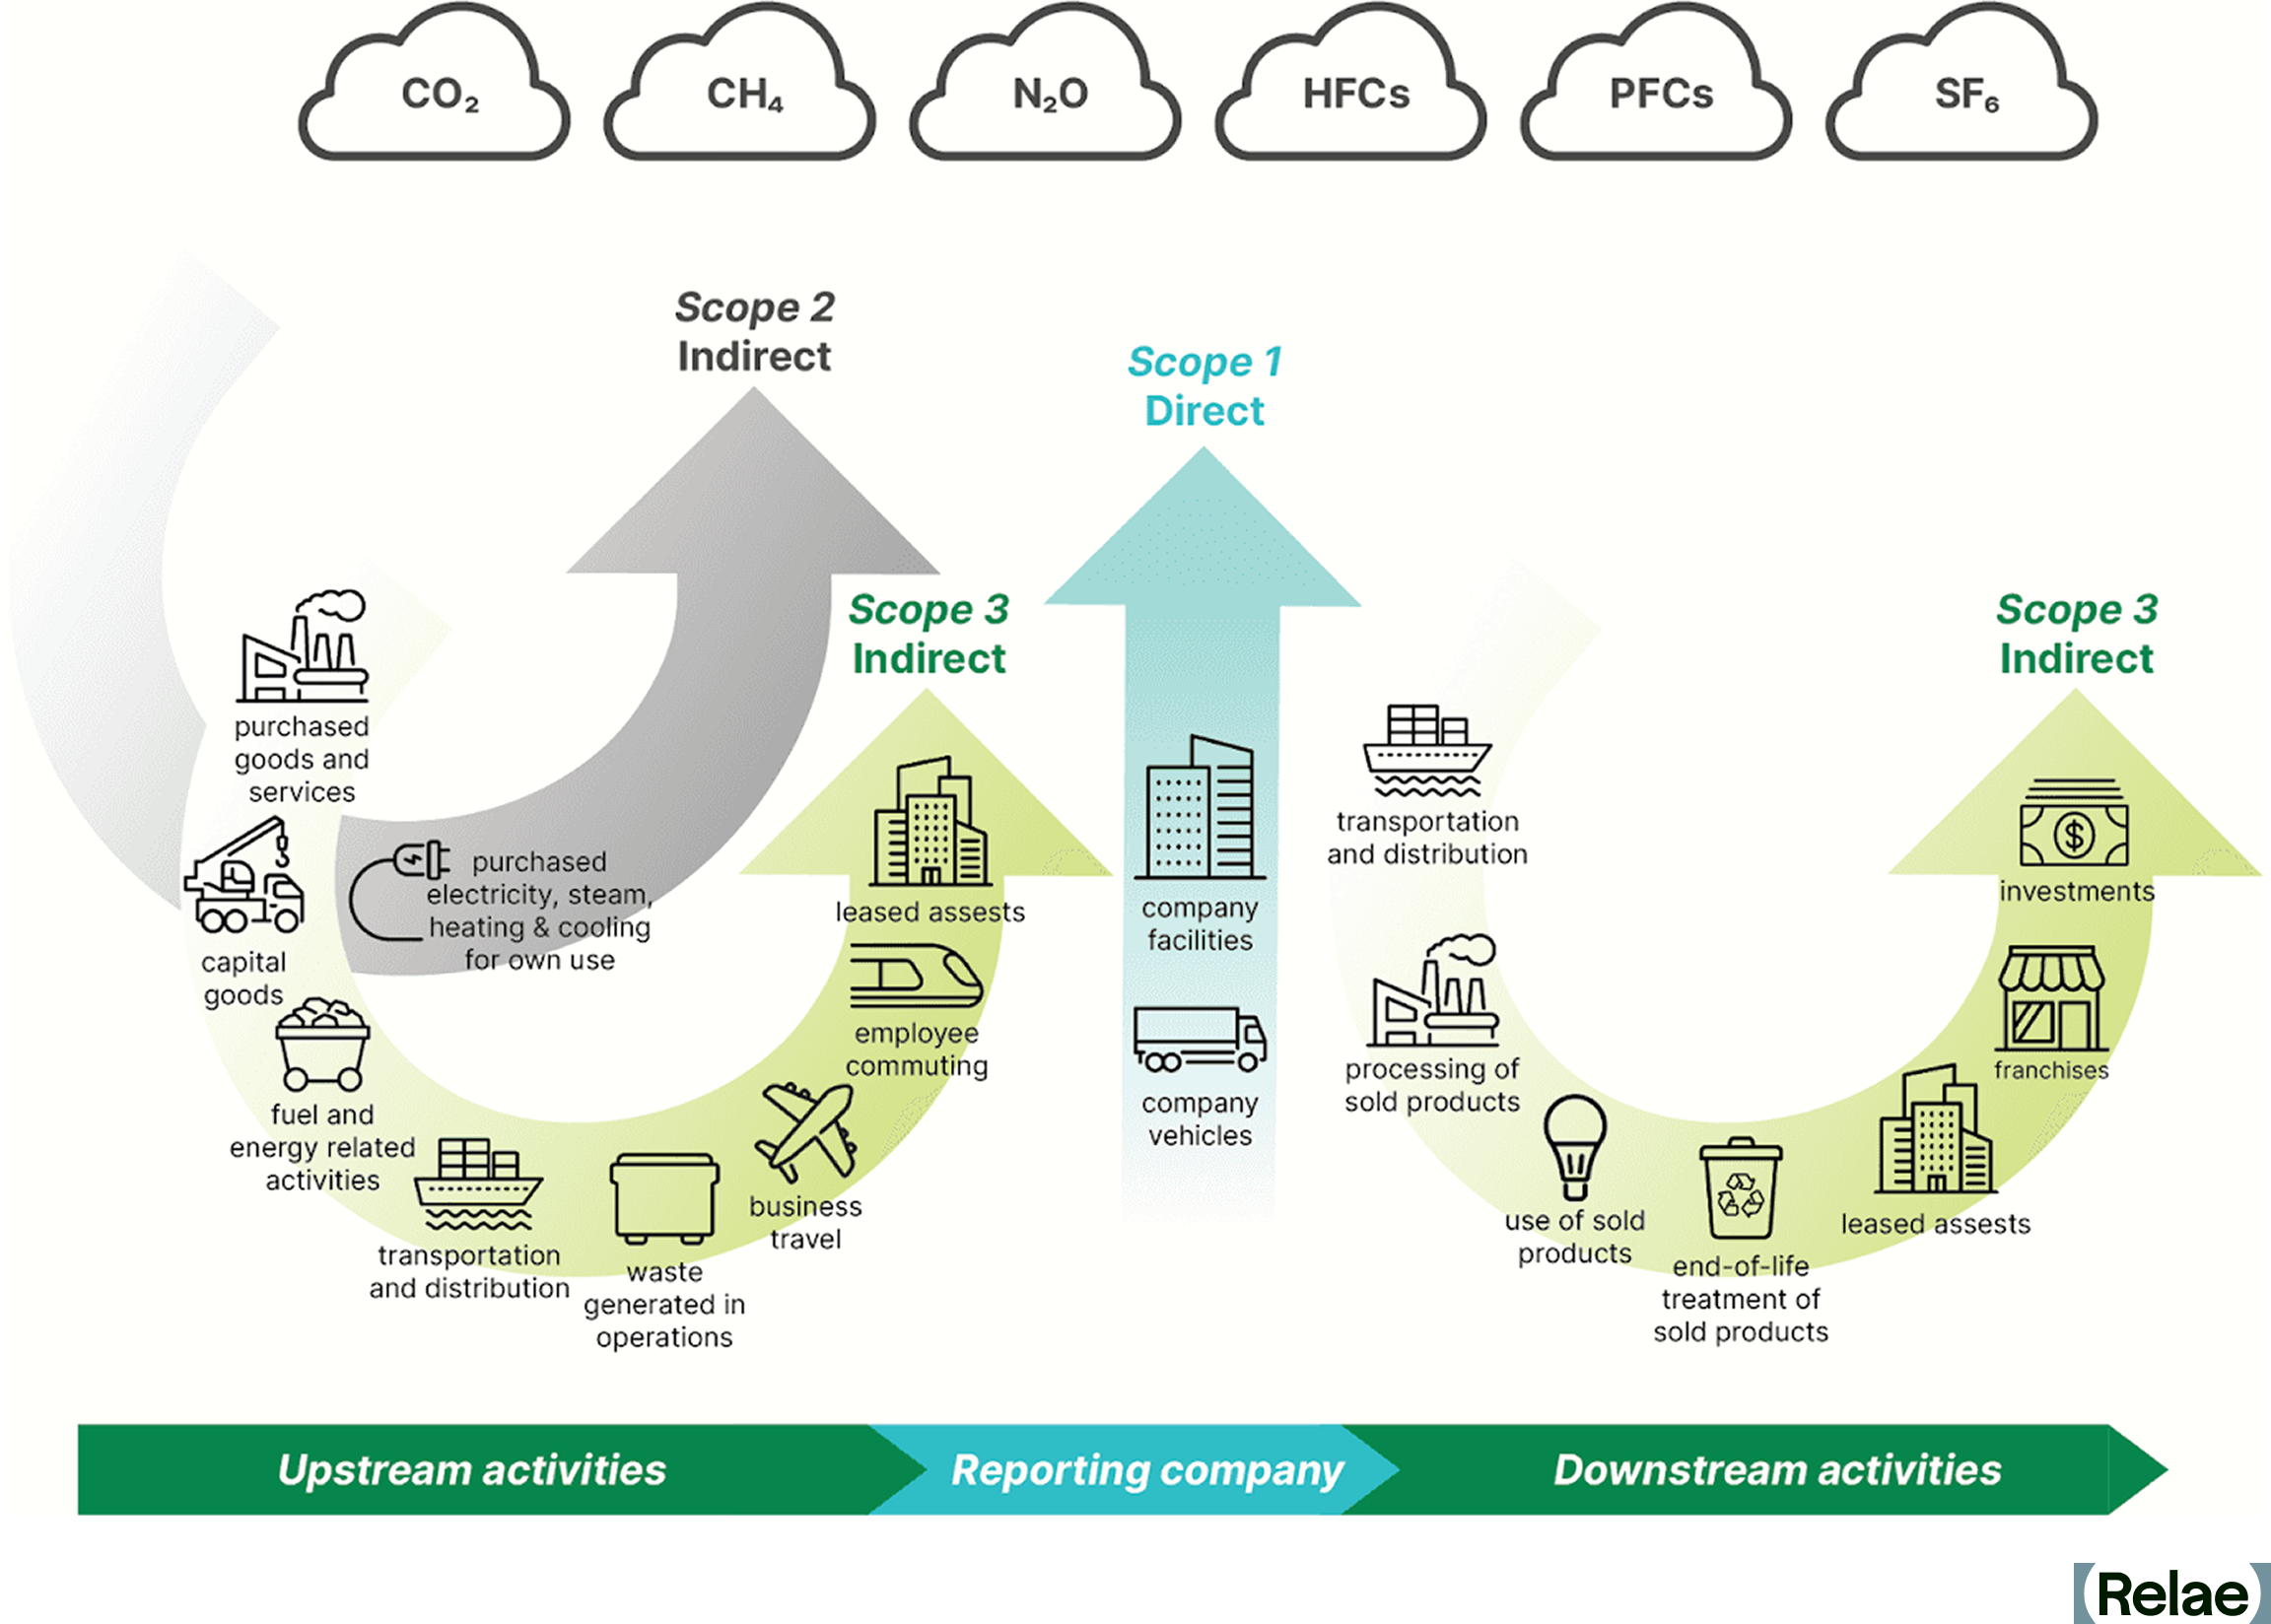
The GHG Protocol Corporate Standard is a globally recognized framework for corporate entities to publicly report GHG emissions throughout their value chain. It divides emissions into three scopes:
- Scope 1: Direct emissions from owned or controlled sources, such as company-owned vehicles, on-site fuel consumption, or industrial processes.,
- Scope 2: Indirect emissions from the generation of purchased electricity, heat, steam, or cooling. These emissions are generated off-site, but result from an organization's energy consumption.
- Scope 3: Indirect emissions across an organization's value chain. Scope 3 is divided into 15 categories, including a company's supply chain activities, business travel, employee commuting, investments, and product life cycle emissions.
This piece focuses on emissions associated with electricity consumed by a reporting entity. These electricity-related emissions primarily fall under scope 2 and scope 3: category 3 (fuel- and energy-related activities, or FERA).
Scope 2: Electricity Generation Emissions
Scope 2 emissions account for the generation of electricity a company purchases or uses. Hypothetically, if a company were powered by a single solar project, it would report zero scope 2 emissions. In reality, a company is powered by a combination of power generation assets and must report them under scope 2 emissions. These emissions can be reported using two methods:
- Location-based method: Reflects the average emissions intensity of the local electricity grid where the consumption occurs. This approach is mandatory under various reporting frameworks and does not take into account a company's procurement choices.
- Market-based method: Reflects an organization's actual procurement decisions and energy-sourcing strategies. It accounts for specific contracts, such as power purchase agreements (PPAs), renewable energy certificates (RECs), and green tariffs, which allow businesses to claim lower emissions from their purchased electricity.
Scope 3: Category 3 FERA
Scope 3: category 3 FERA reports on non-generation electricity emissions associated with:
- Upstream emissions: Emissions associated with the production and transportation of fuels needed for electricity generation
- Transmission and distribution losses: Emissions associated with the loss of electricity while delivering it from the generator to the consumer.
The GHG Protocol Corporate Standard does not include emissions associated with the manufacturing, construction, and end-of-life phases of electricity generation equipment; however, some datasets used for reporting may include manufacturing emissions. While scope 3: category 3 guidance may not require these emissions to be included, if possible, companies reporting on their electricity-related emissions should include these additional sources of emissions in order to more completely represent their total emissions impact. The GHG Protocol Scope 2 Guidance allows for the reduction of some of the reported scope 3 FERA emissions by contracting renewable energy (see Appendix B).
What is an LCA?
An LCA is a systematic method used to quantify the environmental impacts of a process, product, or project throughout its full life cycle. A life cycle includes everything from raw material extraction ("cradle") to manufacturing/production ("gate") through disposal ("grave").
LCAs primarily follow a standard published by the ISO organization (ISO 14040/14044). The ISO standards establish industry-wide rules for which processes are included and how to assign environmental burdens to products.
An LCA can be used for any product, process, or project, and can estimate multiple different environmental impacts (i.e., climate change, human health, ecotoxicity, eutrophication, ozone depletion).
Electricity-Related Emissions Can Be Different Using the GHG Protocol and an LCA
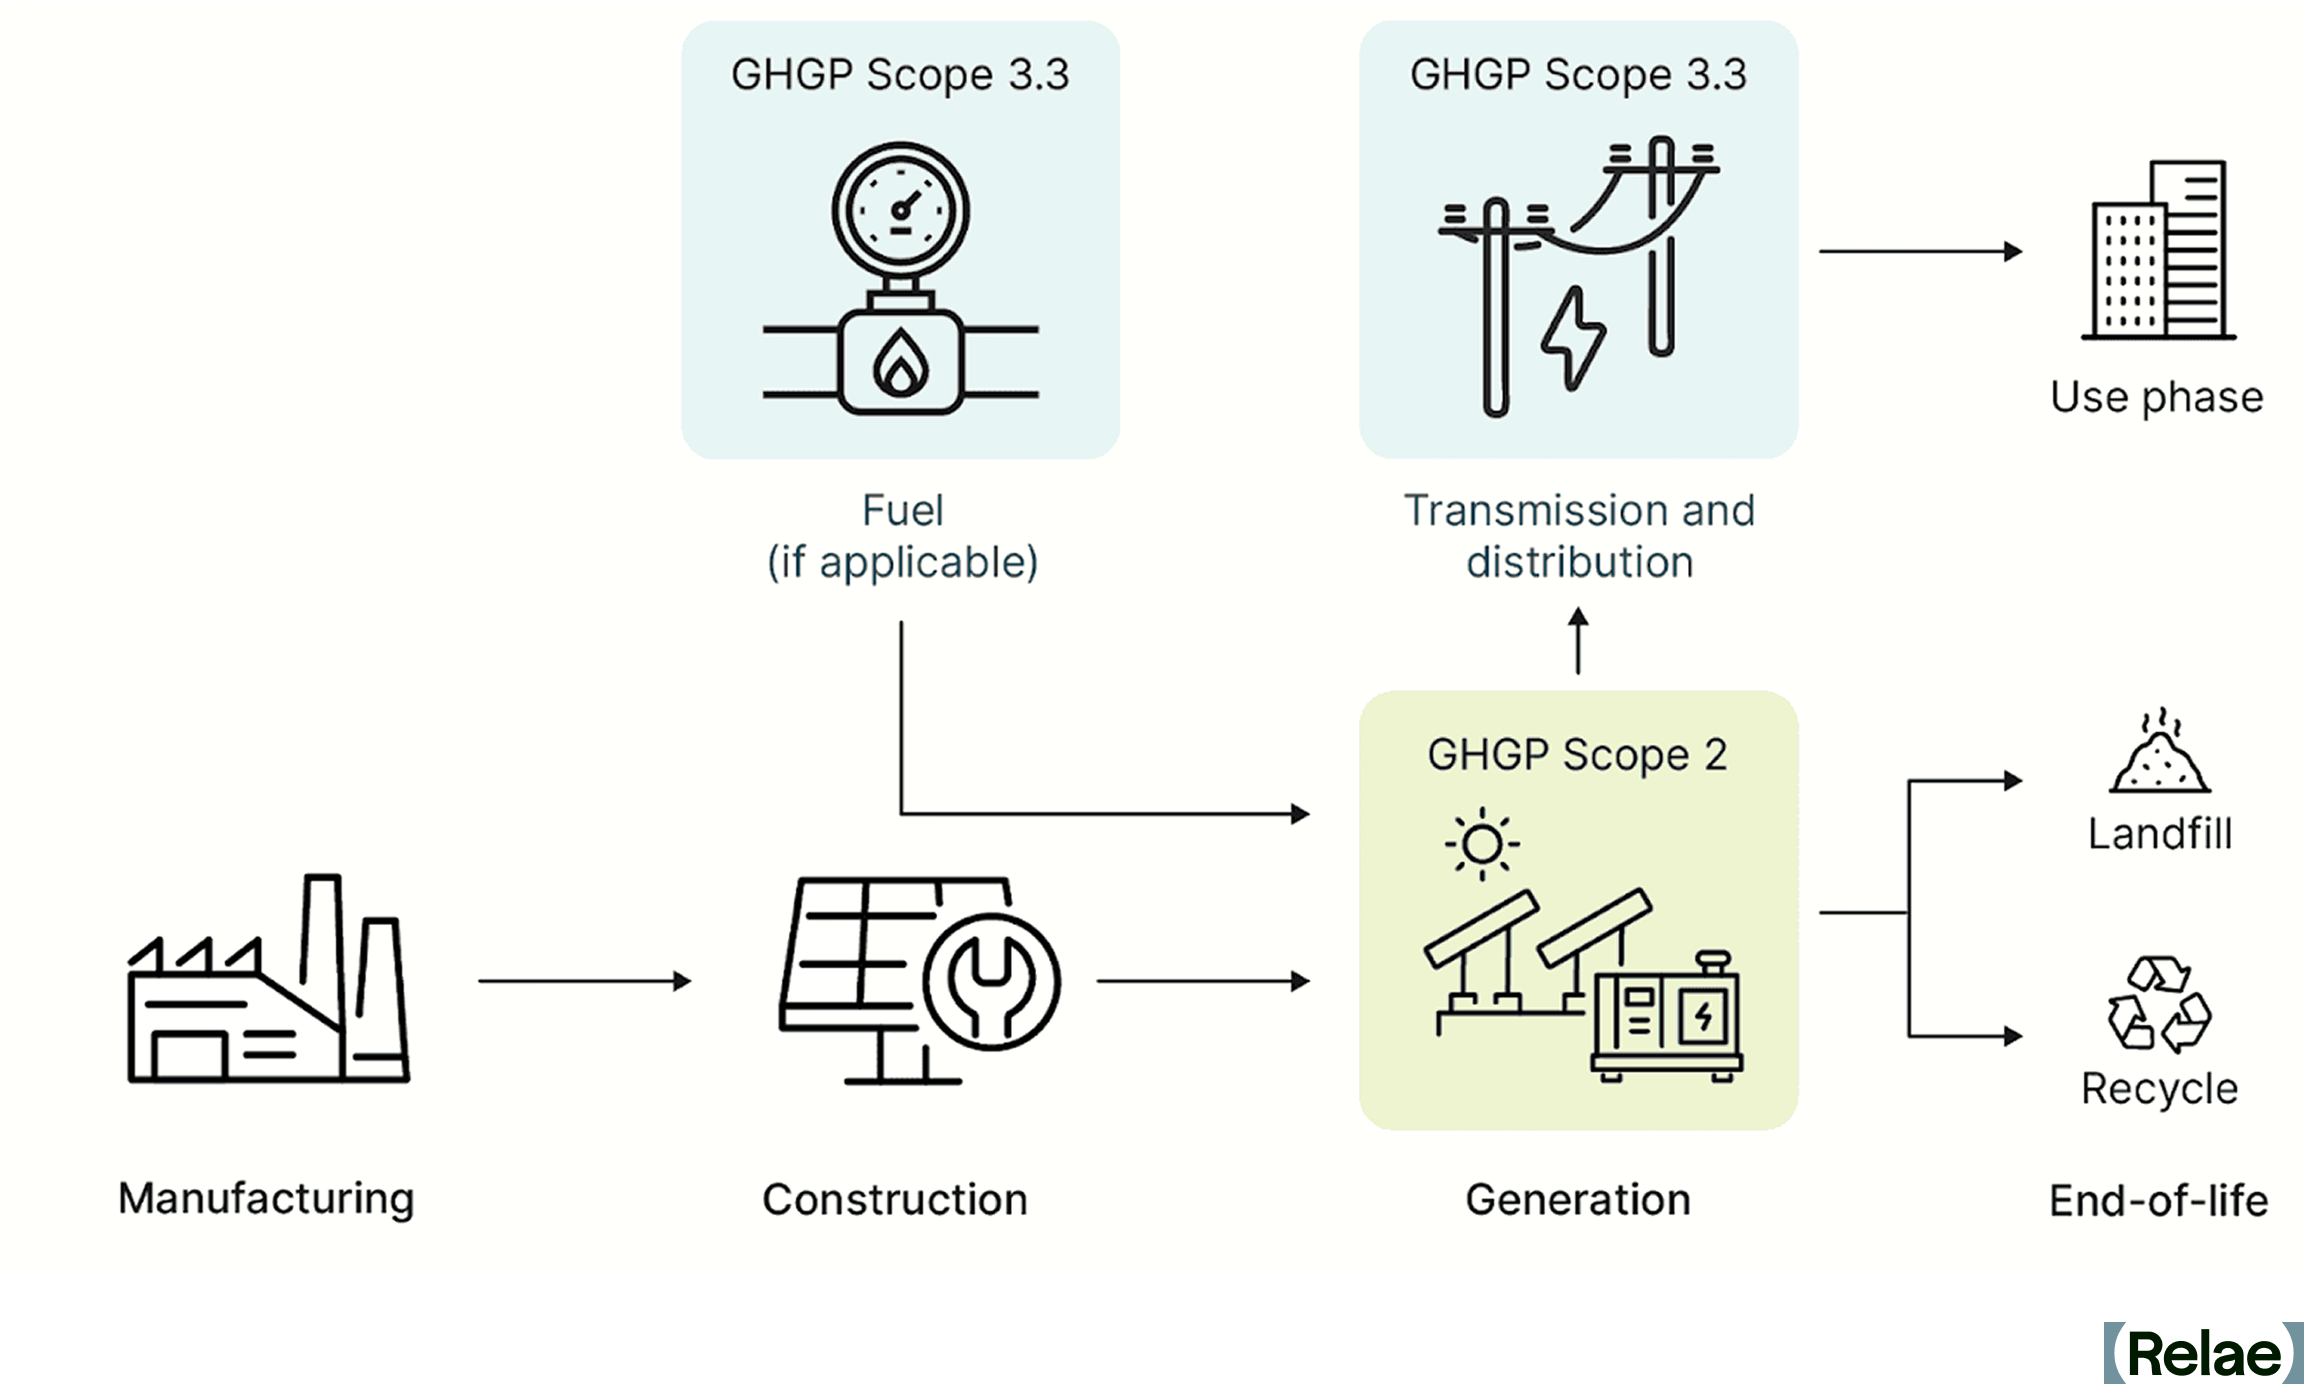
The GHG Protocol Corporate Standard and an LCA (as per ISO standards) generally include different life cycle stages of electricity use when estimating GHG emissions. Therefore, the approaches can result in different reported emissions.
Key Differences in Reporting Electricity-Related Emissions
The GHG Protocol Corporate Standard includes emissions in the following phases:
- Generation (scope 2)
- Transmission and distribution losses (scope 3: category 3)
- Fuel, if applicable (scope 3: category 3)
A “cradle-to-grave” LCA considers emissions from all activities associated with power generation, including:
- Manufacturing
- Construction
- Generation
- Fuel, if applicable
- Use-phase, if applicable
- End-of-life
Use-phase electricity-related emissions are emissions generated by electricity-consuming equipment used or sold by the reporting company (representing additional scope 1 or scope 3 emissions, respectively). Examples include sulfur hexafluoride (SF6) emissions from electrical transformers or refrigerant leakage from air conditioners with high global warming potential. Please note that both the ISO and GHG Protocol Corporate Standard provide guidelines for reporting these emissions. However, due to the equipment-specific nature of these emissions, they are excluded from the following table. The table compares electricity-related emissions associated with different electricity sources using the GHG Protocol Corporate Standard approach and the LCA approach.
Reporting Electricity-Related Emissions
* US average transportation and distribution loss rate (4.2%) times US average grid carbon intensity (410 gCO2e/kWh). Note: gCO2e/kWh = grams of carbon dioxide equivalent per kilowatt-hour. Source: GREET 2024 (US grid average. 10% fuel- and energy-related activities; 1% construction, facilities, maintenance, and end-of-life; 89% fuel combustion).
Reducing Electricity Emissions with Renewable Energy
Renewable Energy Mechanisms Under the GHG Protocol
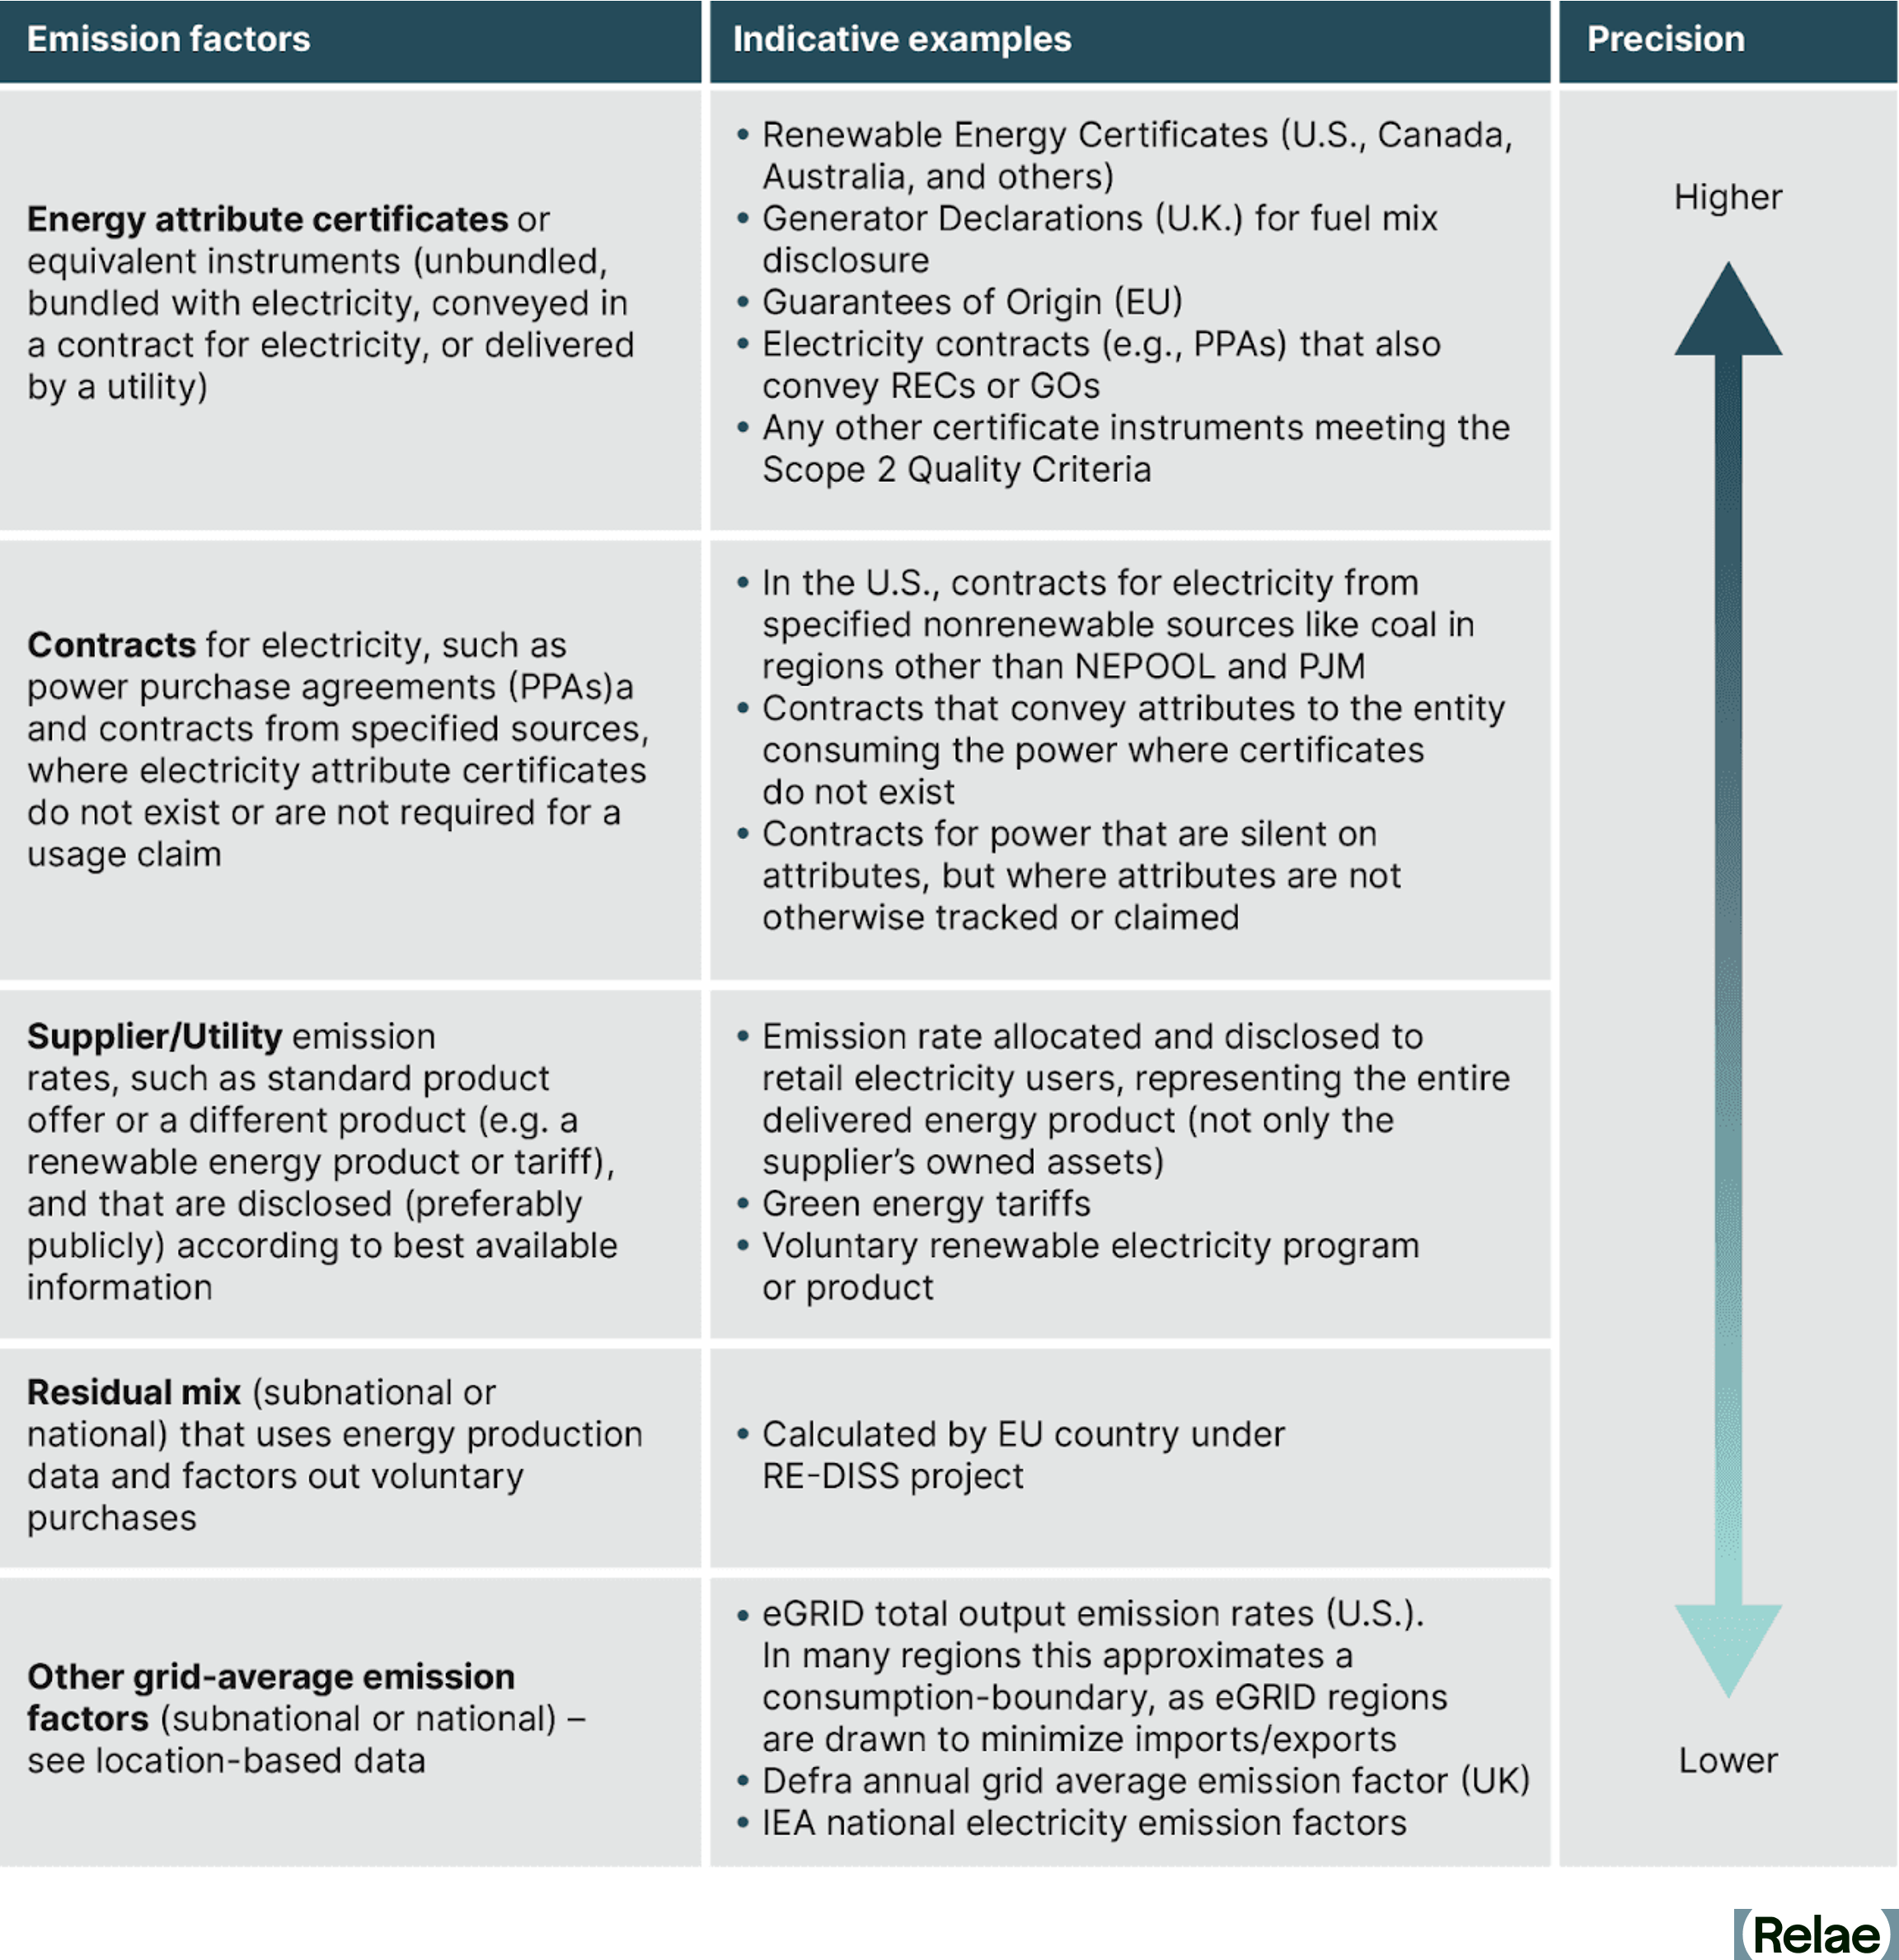
The GHG Protocol Corporate Standard allows companies to contract for renewable electricity as a mechanism to reduce reported emissions. The GHG Protocol Corporate Standard defines allowable energy contracts that can be used to reduce emissions associated with electricity consumption (market-based reporting).
In North America, one of these allowable contracts is RECs, each of which represent one megawatt-hour of renewable generation. Analogous instruments used in other locations, such as Guarantees of Origin in Europe and green electricity certificates in China, are also permissible under the GHG Protocol Corporate Standard.
RECs were developed as a contractual mechanism for renewable electricity in response to the fundamental structure of "a power grid." In a power grid, it is impossible to link a single generator to a single load. Power is injected at a point in the grid and withdrawn at a different point in the grid; there is no traceable pathway.
RECs were created to track the attributes of electricity generation entering into a power grid for the entity that consumes the power at a different point. The GHG Protocol Corporate Standard allows buyers to claim exclusive use of renewable electricity with RECs even if they are actually consuming a mixture of electricity from the grid.
Renewable Energy Mechanisms Under the LCA ISO Standard
The ISO 14040 standard does not address the use of renewable electricity contracts. However, the ISO 14044 standard provides the following guidance:
"When determining the elementary flows associated with production, the actual production mix should be used whenever possible, in order to reflect the various types of resources that are consumed. As an example, for the production and delivery of electricity, account shall be taken of the electricity mix, the efficiencies of fuel combustion, conversion, transmission and distribution losses."
It does not explicitly define whether RECs can or cannot be used in the determination of the "actual production mix." In the event an organization does procure a renewable energy contract to reduce the emissions reported within the LCA, it should disclose that clearly in order to communicate the impact of the contract on the carbon intensity of the LCA with and without the use of RECs.
Powerful Tools for Different Use Cases
The GHG Protocol Corporate Standard and LCAs following the ISO Standard are both powerful tools that can provide insight into emissions associated with electricity use. The GHG Protocol Corporate Standard allows companies to use a standardized framework to report emissions associated with electricity use and interventions on an annual basis. The LCA ISO standard is a detail-driven analysis that allows a deep dive into specific processes, projects, or products. This detailed analysis allows for deeper insights into areas where a company may have more ability to address specific interventions for emission hot spots. Using these tools together, while understanding the boundaries of each, can provide companies with a more effective and impactful approach to decarbonization.
Frequently Asked Questions
What are the differences between the GHG Protocol Corporate Standard and LCA?
The GHG Protocol is an annual corporate reporting framework covering scope 2 (generation) and scope 3: category 3 (transmission and distribution losses, fuel), while a cradle-to-grave LCA is a detailed analysis governed by ISO 14040/14044 standards that also includes manufacturing, construction, use-phase, and end-of-life emissions. LCA can also be applied to any product or process and multiple environmental impacts, not just greenhouse gas emissions.
Why do they result in different emissions for the same type and amount of electricity?
They include different life cycle stages. The GHG Protocol excludes manufacturing, construction, and end-of-life emissions of generation equipment, while an LCA includes them.
Can renewable energy contracts reduce reported electricity-related emissions under both methods?
Under the GHG Protocol, renewable energy contracts (e.g., RECs, PPAs) are explicitly allowed to report zero market-based scope 2 emissions, though scope 3 FERA emissions remain. Under ISO LCA standards, these contracts aren't explicitly addressed. Organizations may choose to apply them, but should transparently disclose LCA results both with and without the contract's impact.
When should you use the GHG Protocol vs an LCA?
Use the GHG Protocol for standardized, annual corporate-wide emissions reporting and tracking procurement interventions; use an LCA for a detailed, process- or product-specific deep dive to identify specific emissions hotspots. Relae recommends using both together for a more complete, strategic view of electricity-related emissions.
Why AI Data Centers Are Being Blocked: A Project-Level Examination
Key Takeaways
- Community opposition has blocked, withdrawn, or stalled more than $170 billion in announced AI data center investment across 20 US states since January 2024. The pace is accelerating: 6 cancellations in 2024, 25 in 2025, and more than 20 additional cancellations by May 15, 2026.
- Data center opposition is bipartisan. It spans red and blue counties, every region, and multiple grid operators, with nearly two-thirds of the blocked investment sitting in counties that voted for Donald Trump in 2024.
- Process and transparency, more than resource concerns alone, drive the fastest and most durable opposition. How a developer runs the engagement process shapes both community sentiment and the project’s ultimate success.
How Many AI Data Center Projects Have Been Cancelled?
Between January 1, 2024, and May 15, 2026, community opposition blocked, withdrew, or stalled 46 announced AI data center projects across 20 US states, representing more than $170 billion in announced investment. These values are disclosed or derived for 35 of the 46 projects; the remaining 11 carry no public figure.
[stat]
The pace of successful opposition has accelerated sharply. Cancellations rose from 6 in 2024 to 25 in 2025. The first five months of 2026 added more than 20 additional cancellations, the fastest stretch on record.
Virginia leads the state count with 11 blocked projects, followed by Indiana with 7 and Texas with 5. Together, those three states account for roughly half of all cancellations in the dataset. The PJM grid region carries the largest single share of blocked investment at $70 billion across 13 projects, followed by MISO at $37 billion.
Is Opposition to Data Centers Bipartisan?
Yes. The opposition wave crosses party lines on every measure we examined. Republican-leaning counties hosted 28 of the 46 host counties (61%), Democratic-leaning counties hosted 16 (35%), and 2 fell within five points.
Weighted by announced investment, about two-thirds of blocked dollars sat in Republican-voting counties. Strong Republican counties (those Trump won by more than 15 points) account for $99 billion across 23 projects. Strong Democratic counties account for $29 billion across 9 projects. The remaining $44 billion spans Lean Republican, Tossup, and Lean Democratic counties.
Why Are Communities Opposing Data Centers?
Communities raise a consistent set of concerns across the country: water demand, electricity rates, air quality where developers propose gas co-generation, rural character, and a lack of transparency in the development process.
Across the seven cases that we studied in depth, process, and transparency concerns were the most consistently cited factors associated with opposition. Non-disclosure agreements between developers and local officials, ownership structures in which the ultimate end-user was not publicly identified, and closed-door pre-application negotiations produce opposition faster and more durably than any other concern.
The pattern holds across very different communities: a diffuse civic mobilization in rural Georgia, an NGO water coalition in a Texas college town, a conservation coalition anchored by the Southern Environmental Law Center in Southside, Virginia, and an institutional civic organization with legal-expert and celebrity support in northern Virginia. Each produced the same outcome, and each flagged process and transparency as a dominant or top-three concern in the public record.
By the time a project reaches its first public hearing against organized community opposition, the political path of the project is largely set. Late-stage benefits packages consistently fail to reverse that trajectory. Communities read them as concessions, not commitments.
Assess Community Opposition Risk Before You Site
Community opposition is now a structural feature of the AI data center siting environment. The patterns are clear enough to act on now. Relae's Community Impacts team helps developers and capital partners implement responsible development standards through pre-siting community intelligence, calibration of benefits design to specific community contexts, and building the verification scaffolding that turns commitments into outcomes.
[cta]
Frequently Asked Questions
Which states are banning data centers in the US?
The first statewide moratoriums on data centers have arrived. In July 2026, Governor Hochul signed the country's first statewide moratorium, an executive order pausing state environmental permits for up to one year for new data centers of 50 MW or more. Texas followed weeks later, halting approvals of new data center grid connections until state regulators audit their power, water, tax, and ownership details. This is a snapshot from August 2026, and we will likely see additional changes in the months ahead.
The local picture is more developed. Individual municipalities and counties have adopted moratoria and zoning ordinance amendments that block or restrict data centers within their jurisdictions. The City of Peculiar, Missouri, removed data centers from its light-industrial zoning entirely. Monroe County, Georgia, and Jones County, Georgia, both adopted moratoria after project denials in 2025. Cassville Township, Wisconsin, and San Marcos, Texas adopted zoning and code amendments in 2026. State legislatures in Virginia, Indiana, Texas, and Missouri have taken up data center siting, ratepayer, and permitting legislation, though most bills remain in progress rather than enacted.
How much data center investment has been blocked in the US?
More than $170 billion in announced AI data center investment has been blocked, withdrawn, or stalled by community opposition across 46 projects and 20 US states between January 1, 2024 and May 15, 2026.
Relae arrived at this figure from data on 35 of the 46 projects; 11 have no publicly disclosed investment value. The pace has accelerated sharply: 6 cancellations in 2024, 25 in 2025, and more than 20 additional cancellations in the first five months of 2026 alone. Virginia leads the state count with 11 projects. The PJM grid region carries the largest single share of blocked capacity at $70 billion across 13 projects.
What causes a data center project to be cancelled by community opposition?
As of August 2026, communities cite a consistent set of concerns across cancelled projects: water demand, grid strain and residential rate impacts, air quality where developers propose gas-fired co-generation, rural character and farmland conversion, and lack of transparency in the development process.
In the seven cases we studied in depth, process and transparency were together the most consistent driver of opposition. Non-disclosure agreements between developers and local officials, shell LLC ownership structures that conceal the end-user, and closed-door pre-application negotiations produce faster and more durable opposition than any single resource concern. Late-stage benefits packages consistently fail once that transparency-driven frame has formed.
From Capture-Ready to Capture-Committed: Decarbonizing Natural Gas with CCS
Key Takeaways
- Data centers are driving surging demand for new, firm electricity supply, accelerating natural gas-fired power generation.
- Carbon capture and storage (CCS) offers a practical way to balance long-term climate commitments with the need for new electricity generation in the near term.
- New natural gas-fired power plants must be capture-committed, not just capture-ready, potentially delivering power in 18 months and decarbonized power 18-24 months later.
- Capture-committed plants integrate planning and finance for the CO₂ capture, transport, and storage value chain from the start.
- Relae believes early investment in engineering, infrastructure, and community engagement is essential to meet capture commitments.
A New Era of Electricity Demand and Climate Pressure
The US and much of the developed world are experiencing profound growth in electricity demand. Two main forces are driving this trend: (1) the push to electrify existing uses, such as vehicles and heating, to improve energy security, enhance system efficiency, and reduce air pollution; and (2) the growth of energy-intensive sectors like manufacturing, telecommunications, and AI data centers.
Among these drivers, AI is creating unique demands that catalyze specific investments in electric power generation. Astonishing AI data center buildout, led by a handful of large technology firms (sometimes called “hyperscalers”) and their utility and construction partners, is accelerating energy consumption. These firms prioritize speed. When asked for their top five criteria for bringing new AI infrastructure online, one executive responded: “Speed, speed, speed, cost, and carbon emissions.”
Data centers require reliable, always-on power (referred to as “firm power”). This differs from other use cases, such as residential or commercial, which do not need the same amount of power across all hours. While hyperscalers and their partners are investing in renewables, nuclear, and geothermal energy at a remarkable pace, renewable resources alone do not yet meet the exploding demand for firm power.
Natural Gas Provides Firm Power but Drives Emissions Higher
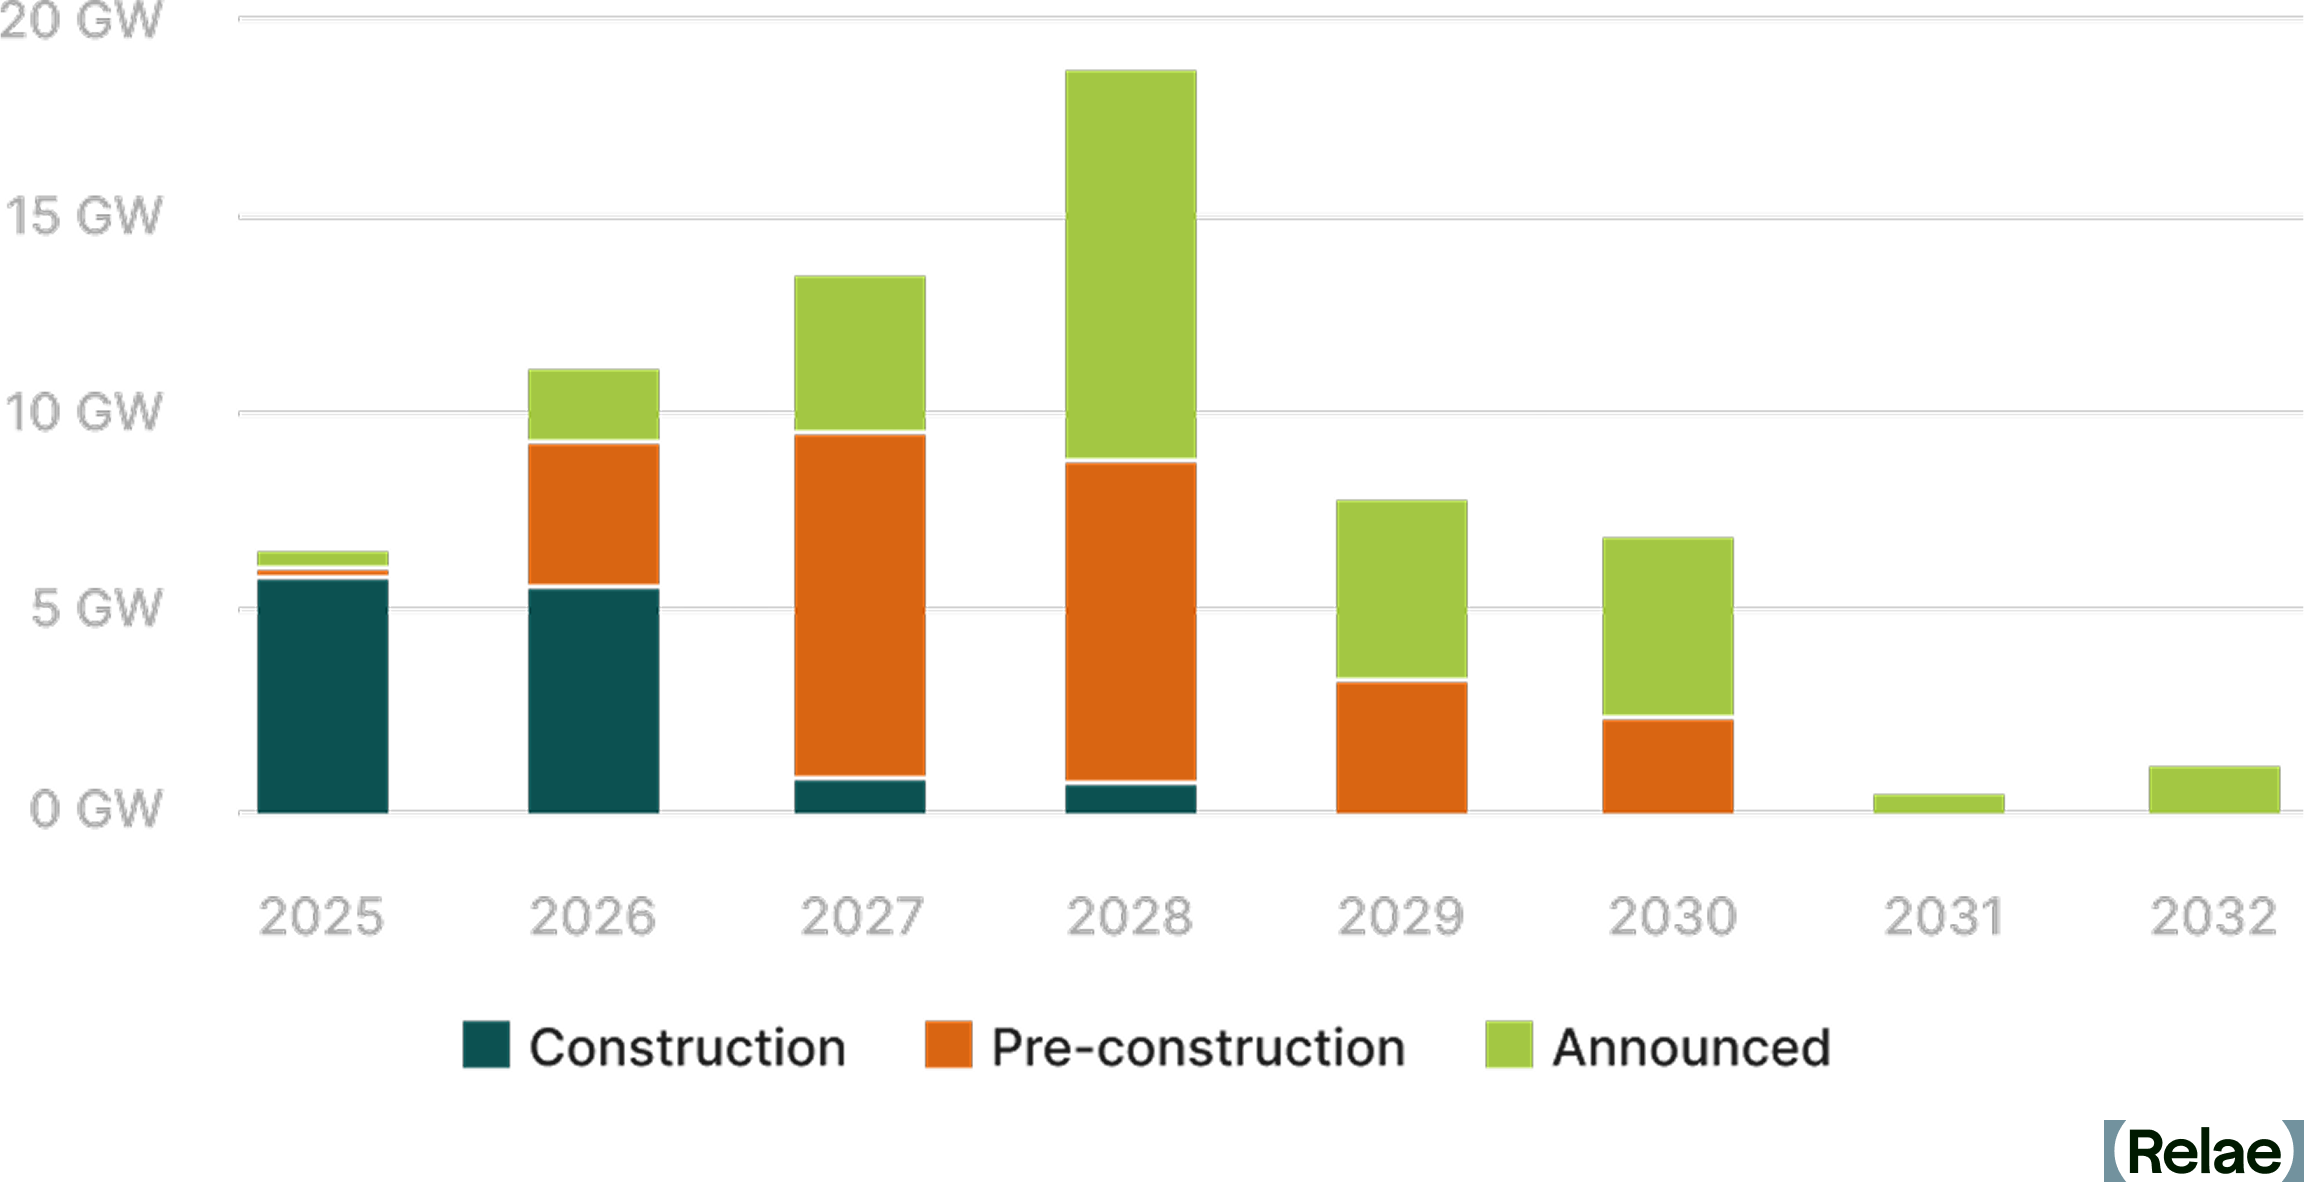
The mismatch between data center power needs and variable renewable generation is fueling a boom in natural gas-fired power generation. The pipeline of new natural gas-fired power plants is enormous. Plants under construction in 2025 would, by themselves, add roughly 25 million tonnes of greenhouse gases each year to the air and oceans. The full suite of plants in planning is at least 10 times larger. Existing gas plants are also being used more and staying online longer.
This rapid buildout is creating tension with corporate climate goals. Hyperscalers remain seriously committed to reducing emissions, but their ability to hit those targets is undermined by the need to procure new, large-scale electricity generation quickly.
Carbon Capture Aligns with Data Center Energy Demands
Carbon capture and storage is one way to bridge the gap. Data centers operate continuously and may have the ability to shift or curtail load. This demand profile suits the duty cycles of natural gas turbines and CCS facilities well. The potential to reduce direct emissions is profound: today’s CCS technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
This has led to a resurging interest in the concept of capture-ready gas power generation. New natural gas power plants can be built and brought online in 18 months. In a capture-ready plant, the developers integrate the necessary interfaces and reserve additional land, water, and energy to enable a carbon capture project to be built at a future date. In favorable locations, carbon capture can be added to a capture-ready plant in 18-24 months.
However, past experience shows that capture-ready plants rarely deliver. The ambition and commitment of the developers were contingent on policy and market signals that were either too small or never materialized. While the base plant may have made economic sense in terms of energy value for investment, it does not appear anyone was willing to pay the climate premium for CCS.
As David Hawkins of the Natural Resource Defense Council famously said, “If your plant is capture ready, my driveway is Ferrari ready.” To bring David’s humorous analogy back to the specifics here: don’t build a new driveway without at least a downpayment on the car.
How to Build Capture-Committed Power Plants for CCS
A better approach is building capture-committed plants, namely facilities that integrate CCS from the start. To be capture-committed, project developers must:
- Identify geologic storage for the many millions of metric tons of CO2 that these plants will produce each year over the next 20-30 years.
- Plan reliable CO₂ transportation from power generation to geologic storage by pipeline, rail, barge, or truck.
- Engage credible vendors of carbon capture technology that serve their needs and fit their goals.
- Fund front-end engineering design (FEED) studies.
- Arrange, or help to arrange, financing for the construction, commissioning, and operation of all necessary components in the CO₂ capture, transportation, and storage value chain.
- Ensure natural gas supply has near-zero fugitive methane emissions.
- Partner with local and frontline stakeholders to incorporate community impact into project planning, design, and financing.
Capture-committed plants send strong market signals. They help build the permitting pathways and develop the workforce, infrastructure, and community acceptance needed to avoid extra expense and delays. Done well, early commitments and investments will likely create repeatable models that reduce build times and costs.
A Path Toward Power That’s Clean Firm and Future-Ready
Eventually more carbon-free power in the form of renewables, nuclear, and geothermal energy will be deployed to serve national and international electric load growth for all types of electrification. Over time, these resources will likely displace natural gas. Until then, hundreds of millions of tons of CO₂ will be emitted each year unless commitments are made to take tangible action now.
Capture-committed natural gas-fired plants offer a pragmatic solution. With the right planning, financing, and community engagement, they can provide reliable power without locking in emissions, and they can deliver enormous benefits compared to uncontrolled operation. Federal and state governments can accelerate this transition by honoring and increasing CCS grants, supporting shared infrastructure, and streamlining permitting for CCS plants as they have for other clean energy supplies. These investments will enable the construction of cleaner, more resilient power infrastructure for the industries driving demand, from AI data centers to heavy industry.
[cta]
Frequently Asked Questions
What is the difference between a capture-ready and a capture-committed power plant?
A capture-ready plant creates an option to add carbon capture in the future, whereas a capture-committed plant treats capture as part of the project from day one. In a capture-ready plant, developers install the right interfaces and reserve extra land, water, and energy, but nothing obligates them to build the capture project, ever. A capture-committed developer secures options for CO₂ transportation and geologic storage, relationships with capture equipment vendors, funding for engineering studies, and financing across the full value chain before the base plant comes online.
Why have capture-ready plants historically failed to add carbon capture?
Nobody was willing to pay the climate premium. Capture-ready developers built plants that made economic sense on energy value alone, then waited for policy and market signals to justify carbon capture. Those signals were either too weak or never arrived, so the option went unexercised and no capture project was ever designed. The base plant runs uncontrolled for decades while the reserved land sits empty. David Hawkins of the Natural Resources Defense Council captured the problem well: "If your plant is capture ready, my driveway is Ferrari ready." Preserving an option costs very little. Exercising it costs a great deal, and capture-ready facilities rarely came with the funding to do so.
If renewables, nuclear, and geothermal will eventually displace gas, why invest in CCS for gas plants now?
Because greenhouse gas emissions happen in the meantime. Gas plants being built today will operate for 20 to 30 years, long before carbon-free resources scale enough to displace them. Left uncontrolled, they will emit hundreds of millions of tons of CO₂ over that span. Capture on those plants avoids most of it. Today's technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
What can federal and state governments do to accelerate capture-committed projects?
Three kinds of support matter most: funding, infrastructure, and permitting. Governments should honor and extend existing CCS incentives. Developers make capture commitments years before any revenue arrives, so uncertainty in government funding undermines the confidence these projects require. Governments should also support shared CO₂ transport and storage infrastructure. Common pipelines, rail terminals, and storage hubs make it easier for developers to secure physical CO2 offtake. Finally, permitting for CCS should be streamlined the way it has been for other clean energy supplies. Permitting delay is a leading cause of cost overruns, and a capture-committed plant should be able to pursue capture and storage with the same intensity and speed as electricity generation.
Top Questions on FERC's Co-Location Compliance Order for PJM, Answered
Key Takeaways
- On April 16, 2026, two weeks before the Department of Energy’s (DOE) April 30 deadline for action on the Large Load Proceeding, FERC, the Federal Energy Regulatory Commission, provided a significant update:
- FERC issued its compliance order on PJM's Bring Your Own Generation (BYOG) tariff; the order approved four interconnection paths, rejected two PJM proposals, and directed PJM to refile by May 18.
- FERC's June 2026 order settled a key question around enforcement mechanisms for co-located projects. FERC rejected PJM's Two-Strike proposal (which would have terminated contracts on second violation), allowing only penalties and suspension from the three new transmission services, materially reducing developer downside risk.
- Notably, BYOG arrangements built on the rejected elements of the compliance filing face restructuring risk before that refile. For deals that clear it, however, energization could begin as early as this summer.
- These proceedings reflect the underlying industry concerns about speed, reliability, and cost equity, shifting the risks and costs of new generation from ratepayers to the large loads, such as data centers, themselves.
- Developers, investors, and project teams can use quantitative grid and load modeling to navigate these risks successfully, converting regulatory exposure into priced engineering decisions.
A New Rulebook for Bring Your Own Generation in PJM
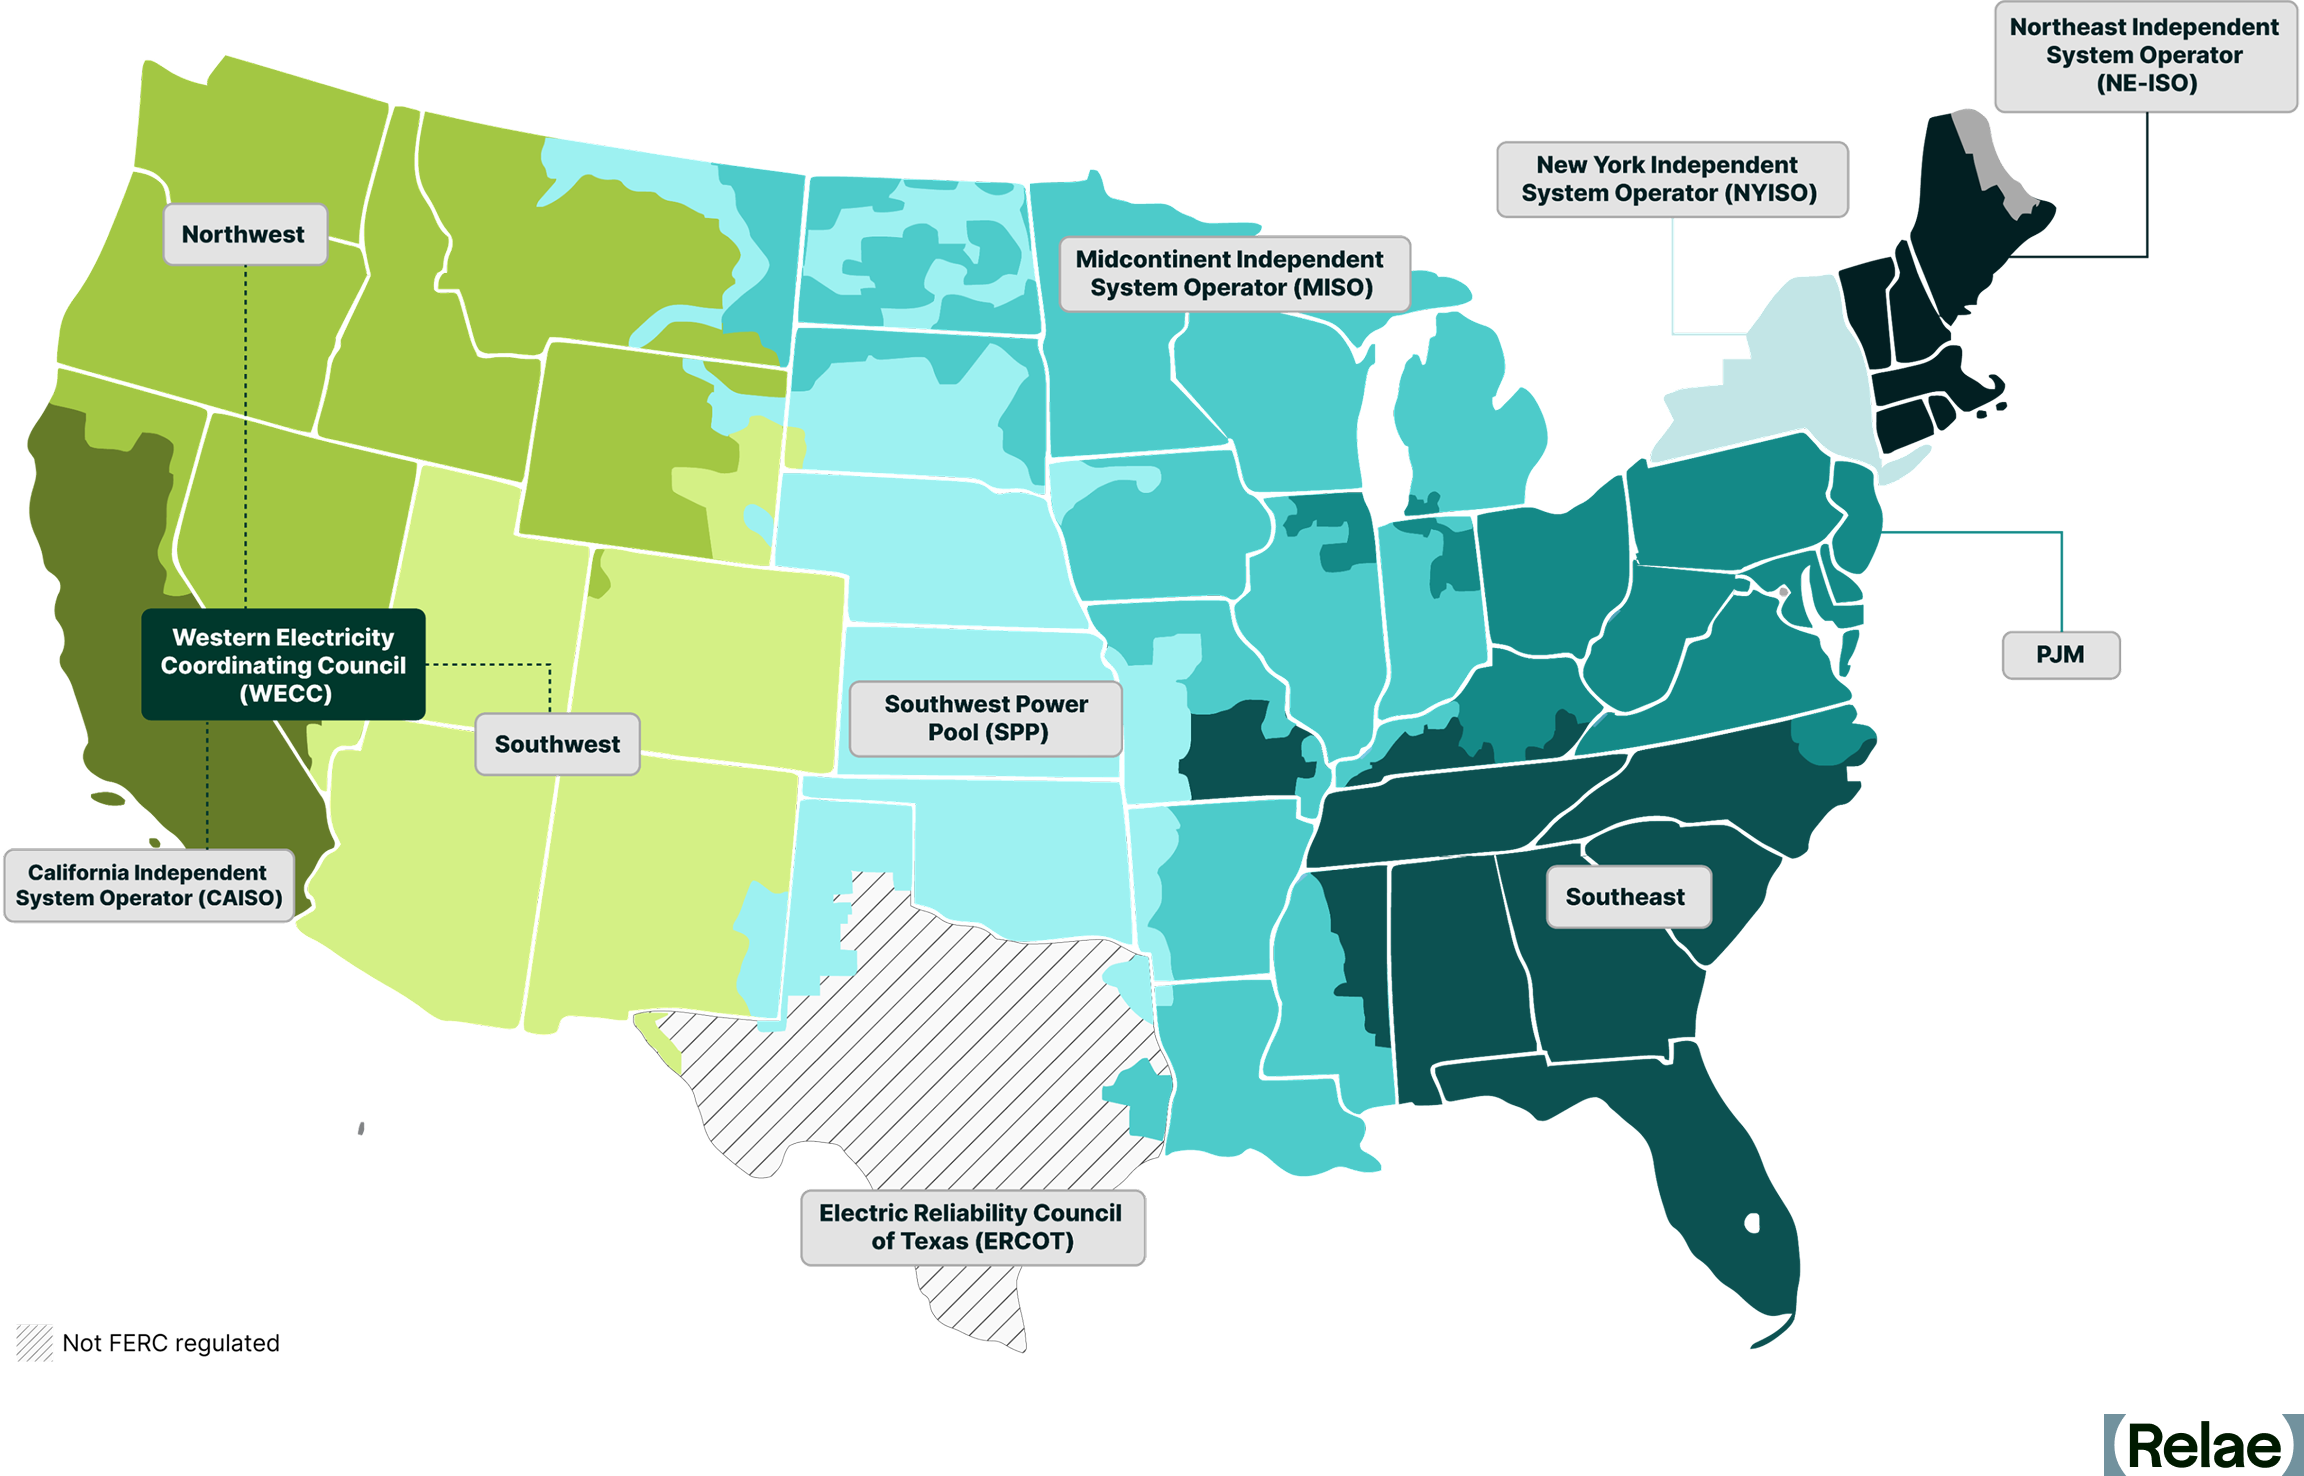
PJM Interconnection (PJM) hosts the highest concentration of data center load growth in the US, managing regional transmission across 13 states in the Eastern US, and commercial operation dates for new generation projects in its current interconnection queue stretch into the early 2030s. Bring Your Own Generation (BYOG) has become the fastest speed-to-power path around that bottleneck.
BYOG allows large loads, such as data centers, to draw power directly from a co-located generation source connected to the bulk power grid, enabling developers to avoid lengthy interconnection queues and costly transmission upgrades, while drawing limited to no power from the bulk power grid.
The Federal Energy Regulatory Commission’s (FERC) April 16 order is now the rulebook that governs the tariffs that facilitate these BYOG arrangements. Any deal built on the paths FERC closed off must now find a way to align with one of the four approved mechanics before PJM's May 18 compliance refile. Deals that clear the refile could begin to energize as early as this summer.
Below are the top questions the Relae power advisory team is fielding most from hyperscalers, large commercial power buyers, and power producers navigating the mechanics of PJM’s BYOG tariff and the engineering realities of running a co-located project.
What Is Co-Location?
Co-location refers to a power generation facility sited in close proximity to a large load, such as a data center, that interconnects directly to the bulk power grid. The generator serves that load contractually via a power purchase agreement (PPA), with power flowing through the meter.
BYOG is the predominant co-location model in PJM. Under a typical BYOG arrangement, on-site generation covers the majority of the data center's load (~90%), with only a small residual portion (~10%) supplied from the grid. Each co-located project effectively functions as its own mini-grid, with explicit operational obligations that are less forgiving than standard transmission service (NITS).
Why Did FERC Keep Behind-the-Meter (BTM) and Co-Location Separate?
While BTM and co-location may look similar, they sit in different regulatory buckets. That said, the line between them is less clear-cut than it once was. FERC found existing BTM rules inadequate to address the grid impacts of large co-located loads and directed PJM to treat co-location as a distinct framework.
At the same time, BTM rules, including how tariffs and distribution charges are applied, remain under revision in a separate PJM proceeding. The two tracks moving in parallel have contributed to the conflation of the frameworks in industry discussion.
How Does Co-Location Differ from BTM Generation?
- Co-location, as this order defines it, is a bulk grid-interconnected arrangement. The host generator remains on the same interstate grid, maintains its interconnection service agreement, and continues exporting power to the grid. The co-located load connects through an approved interconnection mechanic and takes transmission service under a PJM tariff product.
- BTM is a distinct arrangement. The generator sits on the consumer's side of the utility meter and serves the load through a private line, without an interconnection agreement. The load may typically have a grid connection; however, in some circumstances, the generation may be fully off-grid or islanded. By setting a megawatt (MW) threshold for BTM, larger loads with co-located generation may no longer net out their load to reduce transmission and grid charges. FERC's jurisdiction over a BTM arrangement is narrower, and the tariff mechanics that apply to co-location do not apply in the same way.
FERC's rejection of PJM's proposed BTM rule changes illustrates this distinction. The commission is keeping the two categories separate on purpose. Ultimately, FERC’s intention seems to signal that large loads co-located with generation may not be adequately reflected in grid and transmission upgrade costs when these assets are behind the meter. Historically, BTM assets were exempt from these costs because their relatively insignificant power contributions had no meaningful financial impact on the bulk power grid.
That said, the BTM track is still moving. PJM's BTM application rules, including the netting-off mechanism that lets BTM loads avoid utility tariffs, remain under review in parallel proceedings.
For developers, regulatory clarity on co-location and BTM is increasingly critical. In April 2025, FERC upheld its rejection of the Talen-Amazon Susquehanna nuclear BTM interconnection agreement proposal, declining to rehear arguments on the initial decision. To many experts, the split ruling signaled that the structure of PJM’s interconnection service agreement (ISA) is inadequate for large loads operating behind the meter.
However, in the initial challenge to the Talen-Amazon proposal, utility companies argued that the arrangement would unjustifiably shift transmission costs to other PJM customers. Ultimately, in June 2025, Talen Energy entered into a 1,920 MW, front-of-the-meter power purchase agreement with Amazon Web Services, which does not require FERC’s approval.
FERC Has Always Regulated Generators, Not Loads. What Changed?
The April 16 order lands inside a larger jurisdictional shift. FERC does not typically regulate load interconnection; its authority sits with the bulk power grid. Under Orders 888 and 2003, FERC has regulated how generators connect to that system (with standardized study deposits, readiness requirements, and withdrawal penalties) while load interconnection has historically been regulated at the distribution level under state jurisdiction.
That generation-only approach to FERC regulation worked for three decades. Now, the scale of AI data centers and other large loads creates interstate impacts that state-level load regulation cannot fully address. Generation co-location breaks the pattern by routing the load through a FERC-regulated generator interconnection agreement rather than a state-regulated load-serving entity, pulling it into federal jurisdiction.
In December 2025, FERC declared PJM's existing interconnection rules (tariff) unjust and unreasonable in the PJM Co-Location Order and directed PJM to revise the tariff. The April 16 order is FERC's review of that rewrite.
As FERC Commissioner David Rosner wrote in his concurrence to the December 2025 PJM Co-Location Order: "We are trying to meet surging demand while upholding two fundamental values that underpin the electric industry in our country: first, that all customers have a right to receive electric service on a timely basis, and second, that electric service should be reliable and affordable for all customers. Given the scale of new large loads putting demand on our grid today, it is clear that fostering both of these values requires intervention."
Which Four Interconnection Mechanics Did FERC Approve?
The April 16 order (Docket ER26-1088-000, 195 FERC ¶ 61,030) approves four ways for a data center to plug into the PJM grid. Each solves a different bottleneck: available capacity, queue position, study timing, or pre-studied capacity. All four rely on existing PJM and FERC tariff mechanics rather than new constructs, a deliberate choice to reduce legal exposure and speed up adoption.
- Sub-full-capacity interconnection service (available capacity). The data center co-locates with an existing host generator, and interconnects at less than the host generator's full capacity, using the portion of the existing interconnection rights the generator does not need.
- Request acceleration at Decision Points I and II (queue position). Co-located load applications can move ahead of the standard queue at defined checkpoints, subject to PJM's study results. Co-located loads place less demand on the bulk power grid than new large loads without co-located generation, justifying the accelerated treatment. To qualify, projects must demonstrate there will be no significant network updates required or network impact, among other readiness milestones.
- Provisional Interconnection Service, or PIS (study timing). Interim interconnection services are provided during the full study, giving developers a bridge to early operations.
- Surplus Interconnection Service, or SIS (pre-studied capacity). Use of unused capacity at an already-studied generator’s interconnection point, without triggering a new full study.
The four mechanics are different ways of answering the same operational question—how a co-located data center plugs into the grid without triggering a multi-year re-study of the host generator's interconnection—enabling faster speed-to-power.
Which Generators Gain Most From Surplus Interconnection Service?
SIS is the most commercially interesting of the four mechanics for existing generator owners because it monetizes previously stranded capacity.
The generators that benefit most include:
- Retiring or derated thermal units with unused megawatts of interconnection rights at high-value points (for example, retiring coal plants in PJM's eastern and mid-Atlantic footprint).
- Existing nuclear and large thermal plants near concentrated load growth, particularly in Dominion, American Electric Power (AEP), and ComEd territory (the Northern Virginia, Columbus, and Chicago metro zones), where PJM load is most concentrated.
- Storage-paired assets where the underlying generator has capacity headroom that the storage does not fully use (for example, solar-plus-storage or gas-plus-storage sites where the battery sits below the full interconnection rights).
For illustration, a host generator running at roughly 85% of its interconnection rights with a forced outage rate near 5% has material surplus capacity (10%) available to a co-located load, depending on how PJM studies the combined profile.
Owners of underutilized interconnection rights now have an approved tariff path to extract value from them by attracting data centers to co-locate with these generators.
What Transmission Service Does a Co-Located Load Receive?
Connecting to the bulk power grid and taking service from it are two separate decisions. PJM's default transmission service for any load on the system is the Network Integration Transmission Service (NITS), the standard contract for firm power year-round. NITS commits PJM to serve a customer’s full load at any and all times, meaning that PJM may need to wait for generation and/or transmission upgrades before offering it to a large load.
Recently, PJM reopened its generation interconnection queue after pausing to study its backlog of proposed projects. With 800 proposed projects representing approximately 220 GW in new capacity in 2026, this growth signals progress, but it does not address the underlying permitting and financing challenges that have prevented projects already in the queue from being built.
The BYOG mechanics are variations that waive or defer parts of NITS for faster speed-to-power. PJM delivers the resulting service through three tariff product types:
- Firm contract demand: The co-located load holds firm transmission service (consistent with most aspects of NITS) and operates like any other firm load on the system. Availability is site-specific, depending on the point of interconnection. Unlike other NITS customers, entities contracting firm contract demand transmission on behalf of co-located loads cannot exceed the contracted demand level, and loads would be subject to a penalty if they withdraw additional energy beyond the contracted demand capacity.
- Non-firm contract demand: The load accepts interruption risk in exchange for faster interconnection or lower-cost service, making it better suited to loads with operational flexibility. It is available at more interconnection points than firm service, but power delivery is subject to curtailment based on real-time grid conditions. This service intends to provide brief and intermittent energy access from the bulk power grid, during available periods, under unanticipated circumstances, such as downtime for the co-located generator.
- Interim NITS: A bridge product that provides firm service on an interim basis while the co-located generator is still under construction. The load energizes early; once the generator and any transmission upgrades are complete, the project transitions to a standard NITS arrangement, and the generator can participate in the broader PJM market. However, while the load pays the NITS rate, the load is subject to curtailment under system emergency conditions, posing reliability challenges.
In practice, a 1,000 MW data center co-located with a 900 MW on-site generator would request 100 MW from PJM under one of these three products.
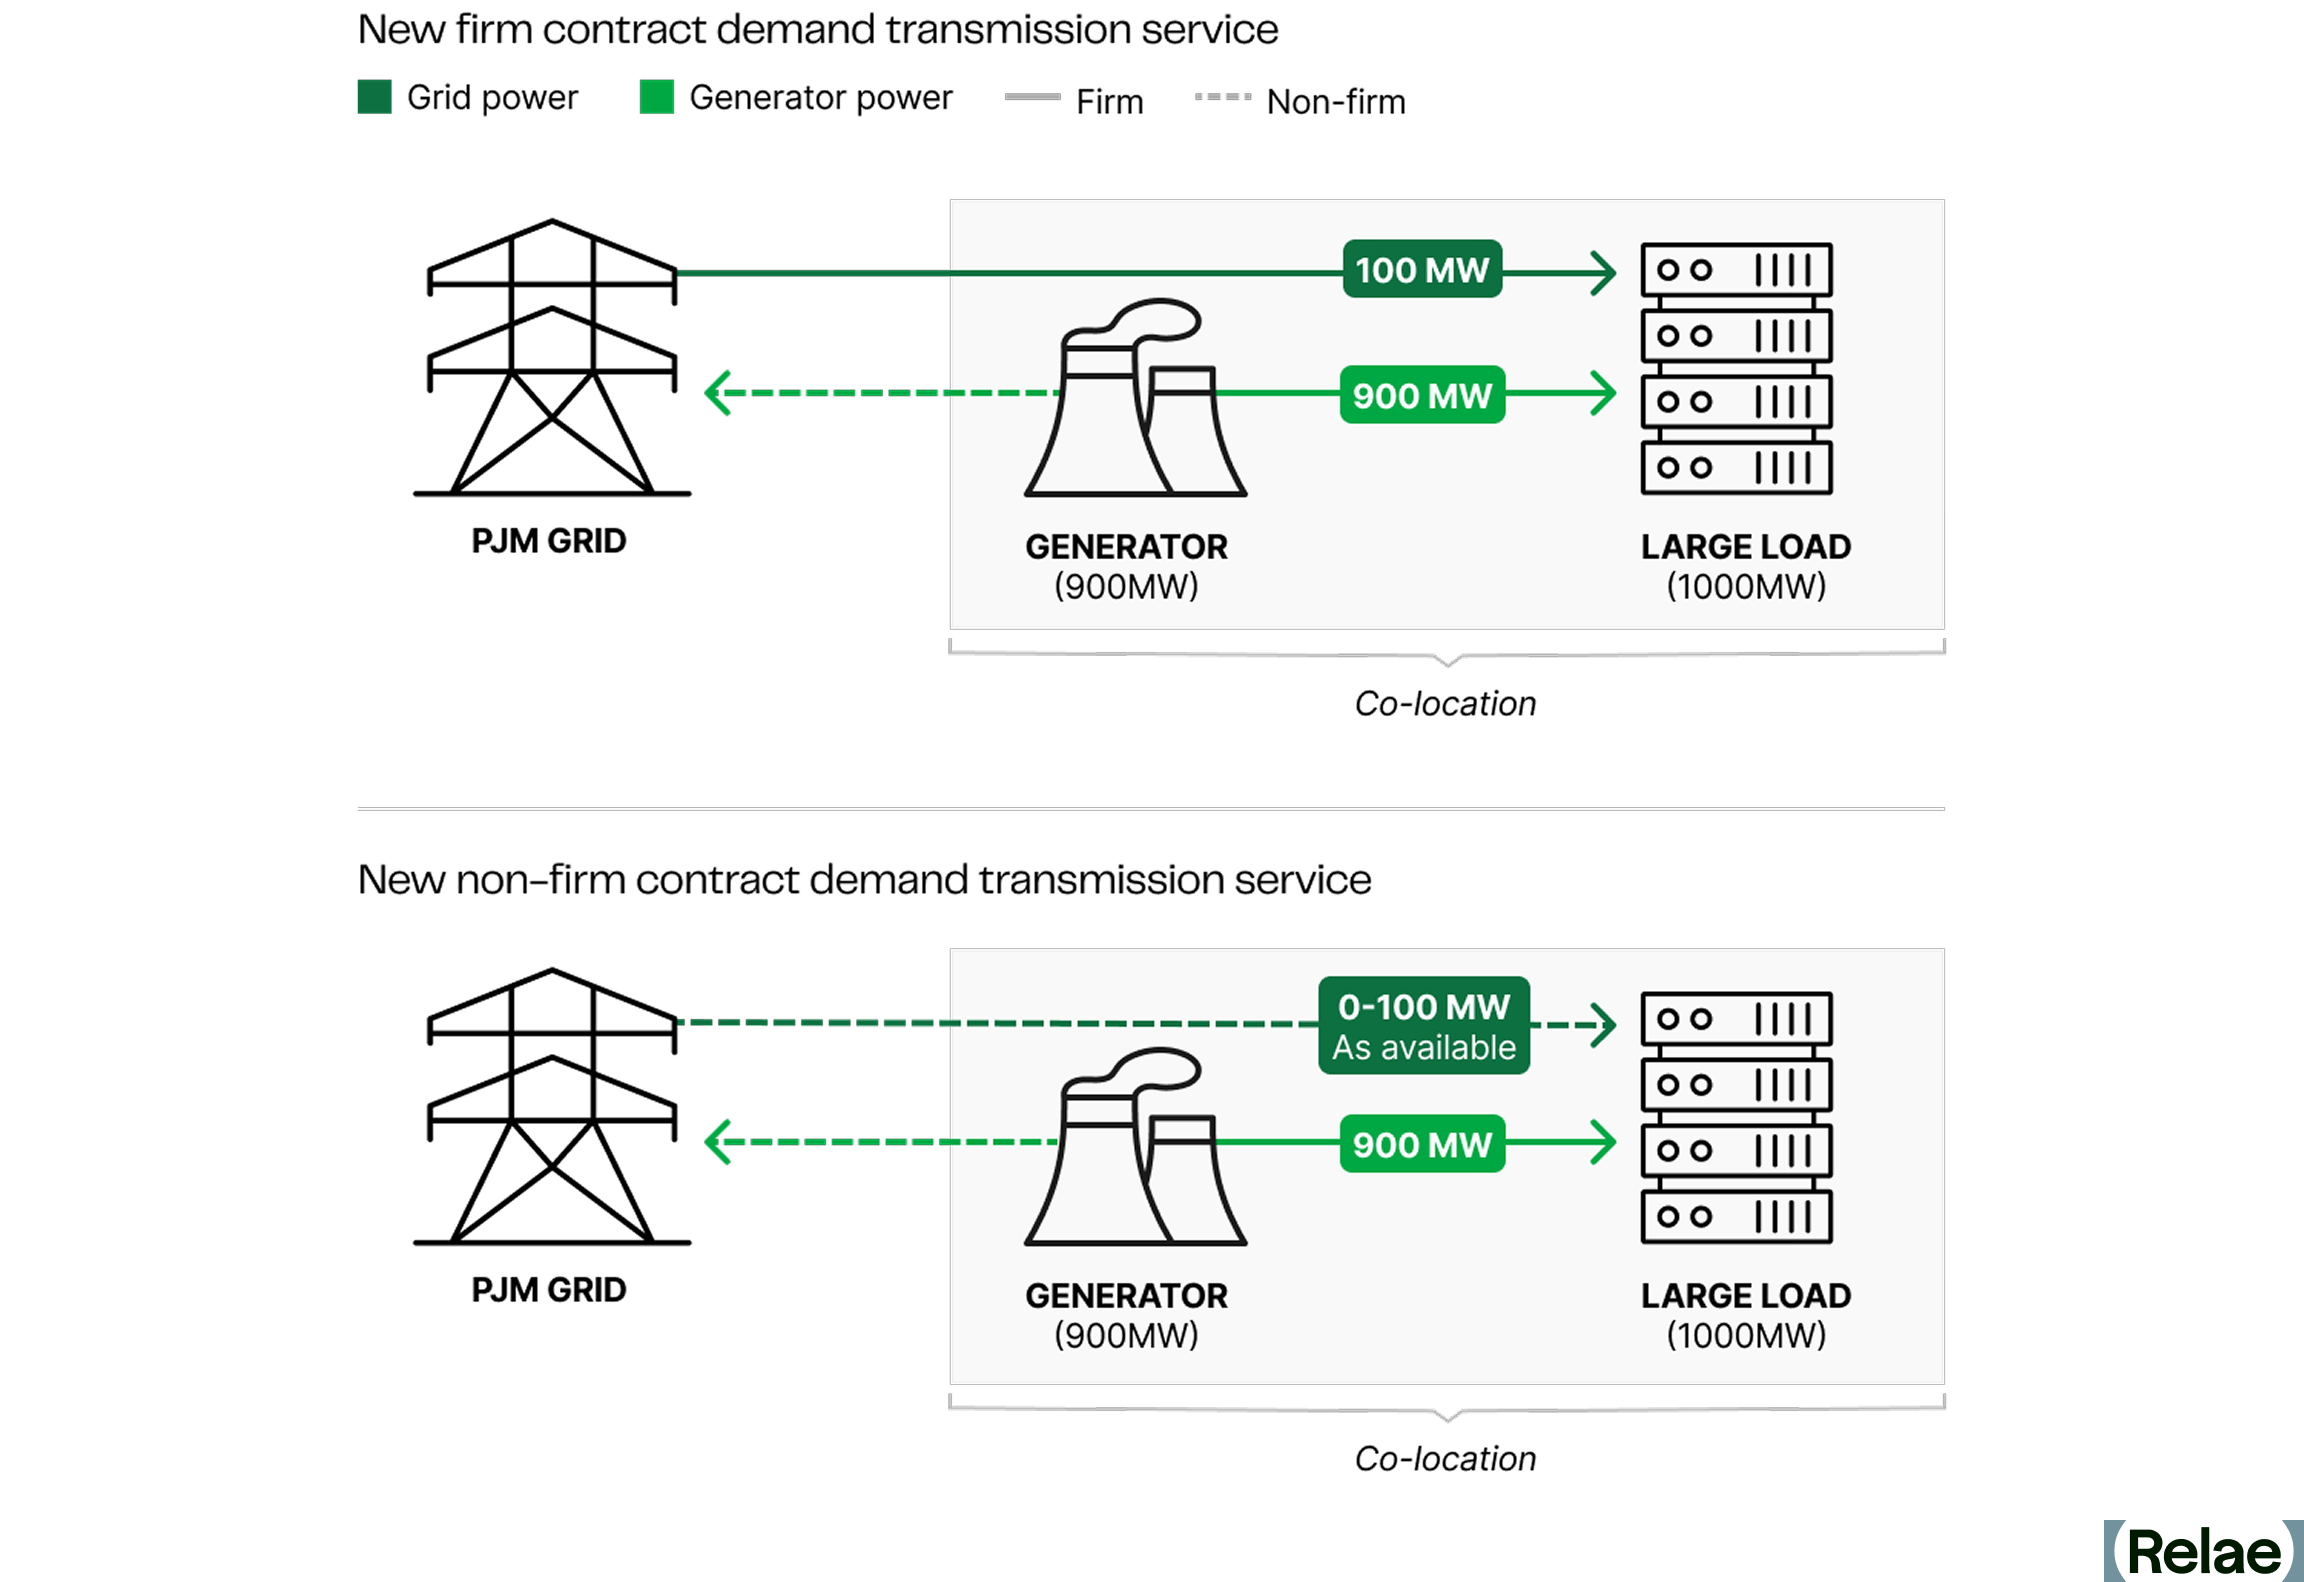
The interconnection mechanic (how the load connects) and the tariff product (what service the load receives) are two distinct decisions. For example, in the case of an interim NITS, a data center and co-located load could connect through a Provisional Interconnection Service (PIS). Other co-located loads may connect by submitting a request for acceleration at Decision Points I and II to secure firm contract demand service. The connection mechanism and tariff will vary based on each co-located load’s unique characteristics and project configuration.
For clients evaluating specific sites, the right path depends on how much of the host generator's interconnection capacity is available, how sensitive the load is to interruption, and how fast the site needs to energize. Grid modeling allows project teams to quantitatively assess their risk exposure before committing to a tariff product.
Which Two PJM Proposals Did FERC Reject?
Two elements of PJM's original filing did not make it through the April 16 order.
- Point of Change in Ownership substitution: PJM proposed swapping in "Point of Change in Ownership" for FERC’s mandated term "Point of Interconnection" in the definition of Co-Located Load. FERC rejected the swap as an unexplained deviation from the Co-Location Order's definition and because it could let transmission owners delay or effectively veto the Point of Change in Ownership location, creating uncertainty for co-located projects.
- BTM application-rule changes: PJM tried to fold changes to its BTM application rules into this same compliance package. FERC rejected that on the ground the changes did not fall within the scope of the initial order. BTM remains a separate regulatory track; the April 16 order does not settle it.
Project configurations built on either rejected proposal need restructuring before PJM's May 18 refile.
The order also directs PJM to add the PIS definition to the Open Access Transmission Tariff (OATT), Part I, section 1 (paragraph 26), and flags items in paragraph 29, including assessment of the reliability of co-located loads paired with electric storage, as out of scope.
These determinations should not be seen as FERC rejecting these tariff changes, but rather deeming them outside the scope of the order. They are open questions that belong in a separate docket. The direction to include PIS while declining to address issues not included in the compliance proceeding demonstrates FERC’s focus on speed-to-power, clarifying the rules for new co-located generators to connect to the grid more quickly.
What Is the Two-Strike Reliability Rule, and Why Does it Matter?
The rules for violating a co-location interconnection service agreement are still being developed, but FERC has urged PJM to issue robust protections to maintain reliability and cost allocation equity.
For both firm and non-firm contract demand transmission service, PJM will apply a penalty rate to transmission service customers who withdraw more energy from the grid than was contracted. The precise design of these rates for unreserved use is scheduled for a paper hearing this spring; however, developers should cautiously size and appropriately model load and generation sizes, as the penalties for jeopardizing PJM’s reliability are not limited to rates.
While penalty rate design for unreserved use is underway, PJM proposed a strict Two-Strike reliability rule for co-located projects. If a co-located customer failed to adequately implement automated loadshedding or generator tripping mechanisms during unusual grid conditions, PJM has previewed severe consequences:
- First strike: a 120-day operational pause for review.
- Second strike: termination of the transmission service contract and return to the NITS interconnection waitlist.
The entire purpose of pursuing a co-located large load configuration is to ensure speed-to-power while maintaining reliability. In a June 2026 order, FERC conceded that there are legitimate reliability concerns with co-located generation misoperation; however, PJM’s proposal to disqualify customers with multiple misoperations is unnecessarily strict. FERC ultimately agreed PJM has the authority to charge penalties to and temporarily suspend services for customers that fail to shed load or curtail, but cannot disqualify customers for misoperation. Data centers will need to rigorously model and design their co-located load and generator facilities with the understanding that multiple reliability violations could strand billion-dollar assets for multiple years.
Which BYOG Deals Need Restructuring Before the May 18 Refile?
Any deal built around the Point of Change in Ownership substitution or the BTM application-rule changes that FERC rejected needs restructuring.
In addition, co-located projects that relied on one of the four approved mechanics, but used PJM tariff language from the original December filing, may also need re-papering against the language PJM submits in its forthcoming May 18 compliance filing. Until PJM files that package and FERC accepts it, the operative document is the April 16 order itself.
Counterparties should confirm that operational controls, curtailment rights, and dispute mechanisms in the contract align with the proposed Two-Strike regime and the approved mechanics the project uses.
What Does Grid Modeling Reveal for a Co-Located Project?
Non-firm service is the lowest-cost tariff product for the portion of load the co-located generator does not serve, but availability depends on real-time grid conditions. Grid modeling is how developers size that exposure before signing.
Take the same 1,000 MW data center paired with a 900 MW on-site generator, contracting 100 MW of non-firm service for the residual load. Grid modeling might show non-firm power dropping out in roughly 15% of hours during the summer peak.
If the on-site generator also carries a 5% forced outage rate, the developer faces a meaningful probability of a compound event: grid supply drops out at the same moment the on-site unit trips offline.
In that window, the data center has three options, none of them free:
- Curtail load.
- Shift the load to another site.
- Draw more from the grid than the contract allows, which triggers a Two-Strike violation.
Grid modeling converts that risk into decisions the developer can price. A developer can test whether adding 50 MW of battery storage, contracting 150 MW of firm service instead of 100 MW of non-firm, or adding a smaller backup generator delivers the best risk-adjusted return.
Who Pays for AI? The Hidden Cost of Rising Data Center Demand
Key Takeaways
- AI data centers are driving the fastest electricity demand growth in decades: US data centers consume an estimated 4 to 5% of US electricity today, projected to reach as much as 9 to 17% by 2030 (EPRI).
- Without deliberate cost allocation, residential and small-business ratepayers subsidize private AI infrastructure.
- Peer-reviewed modeling projects data center growth could raise US power costs 6 to 29% nationally by 2030, and up to 57% in the hardest-hit regions.
- Utility commissioners, state regulators, and policymakers now have working models to draw from, including large-load tariffs, dedicated rate classes, and direct assignment of transmission costs.
AI Data Center Energy Demand Is Testing the Limits of the Grid
AI is driving electricity demand at a pace the US grid has not seen in decades. US data centers already consume an estimated 4 to 5% of the nation's electricity, and EPRI projects that share could reach 9 to 17% by 2030. Behind nearly every AI model and digital product is the invisible infrastructure that powers it: data centers. These facilities are resource-intensive, requiring massive amounts of electricity to power servers, substantial water for cooling, and extensive new grid infrastructure.
In the race to decarbonize the grid, data centers are emerging as a critical pressure point. This infrastructure sits at the intersection of digital growth and climate action, forcing a difficult question: who pays to power AI?
Legacy Utility Models Weren’t Built for this Growth
Utilities must upgrade aging grid infrastructure to meet this new surge in electricity demand, while maintaining reliability. Under legacy utility frameworks, it's often ratepayers who foot the bill for those upgrades. And the costs are not distributed equitably.
Traditional utility planning assumes that increased demand justifies expanded investment in generation and transmission infrastructure. When a new type of large customer, like a tech company, moves into a utility’s service territory, utilities plan new infrastructure to meet that projected demand.
Utilities typically recover the cost of new infrastructure through a process called rate base cost recovery. This allows utilities to charge all customers in the “rate base” for the expenses incurred, including thousands of individuals, families, and small businesses, even when those costs stem from the demands of just a few large users.
This legacy model struggles to keep pace in the AI boom era, where massive new electricity demand can double within a few years, a scale of growth that used to take decades. Additionally, while data centers create short-term construction jobs, there are almost no lasting employment benefits for local communities.
It's clearly inequitable for all ratepayers to bear the costs of upgrading the grid to benefit just a small number of massive data centers. But that's not the only problem. If utilities decide to meet new power demand from large data centers with new fossil fuel generation, such as gas peaker plants, they risk creating stranded assets: infrastructure that becomes obsolete or uneconomical as climate targets, clean energy mandates, or the cost-effectiveness of renewables accelerates. Once built, ratepayers will have to continue paying for these long-lived investments for years, even if they are underutilized or retired early due to policy shifts. This risk is no longer hypothetical: to serve projected data center load, Georgia regulators approved a plan to extend the lives of two massive coal plants to as late as 2038, and Virginia regulators stripped roughly $350 million tied to speculative early-stage data center projects out of Dominion Energy's revenue forecast.
If utilities are locking in decades of new fossil fuel generation to meet short-term data center growth, ratepayers may be left holding the bag for infrastructure that contradicts their climate goals and state mandates, with little ratepayer or community input into the decision. Effectively, local communities may be subsidizing a technology that they did not directly ask for in the first place and has little to no direct community benefits. The result is a long-term misalignment between utility investment strategy and the public interest.
Ratepayers Bear the Cost of Private AI Expansion
The economic burden of data center expansion can fall disproportionately on households and small businesses. But data centers, as the largest and fastest-growing users, often negotiate bespoke contracts, subsidized rates, or fixed-price electricity agreements that shield them from long-term cost volatility.
This can result in other customers, especially residential and low-income ratepayers, bearing a disproportionate share of the infrastructure and maintenance costs. In many states, residential and low-income customers already experience energy cost burdens that exceed affordability thresholds. Adding the weight of infrastructure investments to serve energy-intensive data centers, without sharing those costs equitably, exacerbates an already regressive utility cost allocation system.
Georgia shows how these costs reach ratepayers even when regulators act. Georgia Power customers absorbed six rate increases totaling roughly $43 per month between 2023 and 2025, and while regulators approved a base-rate freeze through 2028, the freeze excluded fuel and storm costs. In 2026 fuel-cost proceedings, testimony showed that large industrial and data center customers raise other customers' monthly fuel costs by 5 to 11%, prompting the Georgia Public Service Commission to open an investigation into how fuel costs are allocated between large loads and residential customers. Ratepayers noticed: in November 2025, both Georgia PSC seats flipped in elections run explicitly on utility bills and data center cost-shifting. In Virginia, regulators approved a rate increase of roughly $16 per month for typical Dominion Energy residential customers amid surging data center demand.
These examples are not anomalies. A peer-reviewed study in Environmental Research Letters projects that data center growth could raise US power costs 6 to 29% nationally by 2030, and up to 57% in the hardest-hit regions, with Virginia among the steepest. This is a systemic shift in energy demand, one that places a growing burden on communities and lacks clear public benefits.
Environmental and Community Impacts Are Mounting
Beyond economic impacts, the geography of data center development reveals another layer of inequity: environmental justice. Data center siting often prioritizes affordable land, low resource costs (e.g., electricity, water), and climate considerations like heat variability. They also rely on proximity to pre-existing fossil fuel generation and transmission infrastructure. Research now confirms the pattern this creates: an analysis of 550 EPA-regulated data centers found that air pollution burdens near data centers rise with the share of people of color living nearby, and a 2026 Washington state study found more than half the state's data centers sit in census tracts with the highest concentrations of people of color.
These communities often absorb the negative externalities beyond their electricity bills, including increased air pollution from peaker plants and on-site diesel or gas backup generators, traffic and construction noise, water stress, and land use changes. Simultaneously, they do not receive direct net positive benefits. Frontline communities are paying attention to this trend, and opposition has become a defining force in where AI infrastructure gets built. Gallup finds 71% of Americans now oppose a data center in their own area, and Data Center Watch counted roughly $130 billion in projects blocked or delayed in the first quarter of 2026 alone. The stakes of community opposition are increasing and intensifying.
The consequences of ignoring communities are now playing out in federal court. At xAI's Colossus facility in Memphis, developers operated dozens of on-site gas turbines without air permits in a majority-Black area already burdened by industrial pollution. After the Shelby County Health Department granted permits for a subset of turbines in July 2025, the fight moved to xAI's second campus across the state line: in April 2026, the NAACP filed a Clean Air Act lawsuit over roughly 27 unpermitted gas turbines at the Colossus 2 site in Southaven, Mississippi, seeking penalties of more than $100,000 per day. On-site power can help reduce demand on the grid, which can be a benefit. But when that generation runs without permits or oversight, nearby communities bear unmeasured health and environmental impacts from hazardous emissions, and the litigation now underway shows how quickly unpermitted power becomes a legal and reputational liability.
To date, data center developers do not appear to have maximized potential community benefits or engagement. Data centers have not typically employed many local residents beyond construction phases, resulting in limited economic benefits, particularly when facility ownership is distant from the local community or has few local ties. When these same communities already experience high pollution burden or economic precarity, the cumulative impact of a new data center can deepen existing vulnerabilities.
Water use is also a mounting environmental justice concern. Many data centers rely on evaporative cooling systems that draw millions of gallons of water per day, and peer-reviewed research finds significant gaps in how the industry discloses its water footprint. In drought-prone regions, this can stress already-depleted aquifers and heighten tensions over water access.
The result is a high-stakes tradeoff between digital infrastructure and local resource resilience, one that communities should be a part of deciding.
States and Regulators Are Writing the New Rules
Virginia, the "Data Center Capital of the World," is home to 674 data centers that consume an estimated 25% of the state's electricity, a share EPRI projects could reach 39 to 57% by 2030, the highest of any state. After legislators considered but did not pass data center bills in the 2025 session, the 2026 General Assembly passed roughly 15 data center bills, including legislation, signed in May 2026, directing regulators to ensure data center costs are not subsidized by other customers, along with new requirements for site impact assessments and water-use reporting. Virginia's State Corporation Commission had already created a dedicated rate class for high energy use customers, with 14-year contract terms and minimum charges that apply whether or not the projected load materializes, and in August 2026 it went further, ordering Dominion to develop a tariff that directly assigns transmission costs to the data centers that trigger them.
Virginia is not alone. Ohio regulators approved a landmark tariff requiring large data centers to pay for 85% of the capacity they request, whether or not they use it. Oregon's POWER Act created the nation's first legislated rate class for data centers. Texas gave its grid operator authority to curtail large loads during emergencies. Minnesota, California, Alabama, Tennessee, South Dakota, Nebraska, and Florida have all enacted their own ratepayer-protection measures, and at the federal level, FERC ordered the nation's largest grid operator to write new rules for data centers that co-locate with power plants, citing the need for consumer protection and clear cost allocation. State energy officials are also proactively planning for data center expansion.
The direction is clear. The unresolved question is whether these reforms move faster than the costs already flowing to ratepayers.
What Is the Public Good of Data Centers?
AI infrastructure powers innovation, job creation, research, and the technologies we rely on every day. But it may also bring inequitable social and direct financial costs. Like highways, factories, and pipelines before them, the question remains: What is the public good of AI data centers? How should we hold data center developers accountable to the public interest, which values a clean energy future? We need clear-eyed assessments of how data centers impact energy affordability, climate progress, and environmental equity.
Yesterday's utility policy frameworks were not designed for hyperscale AI data centers. The reforms now underway are a start, but without sustained attention they may still force the public to subsidize private expansion, through economic and environmental costs, often without equitable community engagement, climate accountability, or local benefit.
AI Data Center Growth Needs Accountability, Equity, and Reform
To align data center growth with the public interest, the stakeholders involved now have proven models to build on:
- Utilities and regulators can require large customers to pay an equitable share of new infrastructure costs, as Ohio's minimum-take tariff and Virginia's dedicated rate class now do.
- Public Utility Commissions can mandate equity and community impact assessments during siting and permitting, following Virginia's new site assessment requirements.
- States can condition tax incentives and zoning approvals on local hiring, emissions reductions, and community benefits agreements.
- Data center developers can prioritize clean power and commit to transparent, equitable community engagement and benefits plans before opposition, litigation, and cancellations decide the outcome for them.
As we build the digital backbone of the next century, we must avoid repeating injustices of the past. A just energy transition requires more than megawatts: it demands equity, policy interventions, and real climate progress.
[cta]
Frequently Asked Questions
How do utilities typically recover the cost of infrastructure built to serve large data center customers, and why does this burden fall on other ratepayers?
Utilities recover infrastructure investments through rate base cost recovery: regulators approve new generation, transmission, and distribution spending, and the costs are spread across all customers in the rate base through their monthly bills. That model worked when demand growth was gradual and diffuse, but when a single data center campus drives hundreds of megawatts of new investment, standard cost allocation spreads those costs across households and small businesses unless regulators adopt a special tariff or rate class that assigns them to the customer who caused them.
What are stranded assets in the context of data center power demand, and how do they create long-term risk for utilities and ratepayers?
Stranded assets are long-lived infrastructure investments, like new gas plants built for projected data center load, that become underused or uneconomical before they are paid off, whether because demand never materializes or because policy and market shifts overtake them. Because utilities recover those costs through rates over decades, ratepayers keep paying even if the asset sits idle. The risk is acute today because data center demand forecasts are highly uncertain: Virginia regulators removed roughly $350 million tied to speculative data center projects from one utility's revenue forecast in 2025.
Why do data centers often locate in rural or low-income communities, and what are the environmental justice implications?
Data center siting favors cheap land, fast permitting, low-cost power and water, and proximity to existing generation and transmission, conditions most common in rural, low-income, and historically marginalized communities. Research confirms the consequences: analysis of 550 EPA-regulated data centers found air pollution burdens rise with the share of people of color living nearby. These communities absorb the air pollution, water stress, noise, and land use impacts while receiving few lasting jobs or direct benefits.
What regulatory or policy tools can states and Public Utility Commissions use to ensure data center growth doesn't unfairly shift costs to residential and small-business ratepayers?
The toolkit has expanded rapidly since 2025. Commissions can create dedicated large-load rate classes and tariffs with minimum take-or-pay provisions, long contract terms, collateral requirements, and exit fees, as Ohio and Virginia have done; directly assign infrastructure enhancement costs to the customers that trigger them; and require site impact assessments during permitting. Legislatures can codify ratepayer protections, require water and load-forecast transparency, and condition tax incentives on community benefits, models now in place in at least eight states.
This commentary reflects public policy analysis and opinion, not legal advice or regulatory determinations.