Understanding the Carbon Footprint of AI and How to Reduce It
Key Takeaways
- AI's carbon footprint has two distinct parts: embodied emissions from building data centers and operational emissions from running them, both accelerating as global data center electricity use is set to double by 2030, and AI-focused use to triple.
- Managing that footprint will require deliberately steering technology architecture, power sourcing, and materials choices, instead of leaving them to react to demand after the fact.
- Eight concrete strategies, from smarter chip design to firm clean power and carbon removal, can cut AI's footprint today, without waiting on new regulation.
- US data centers used 4% of the USA's total electricity in 2024, and are projected to use as much as 15% by 2030.
Introduction
The rapid growth of artificial intelligence (AI), particularly large-language models (LLM) and generative AI, has taken many by surprise. This surge has led to escalating electricity demands at data centers and raised concerns about the strain on the power grid. It has also sparked the construction of new, larger data centers, resulting in growing embodied emissions tied to building and maintaining AI physical infrastructure.
Managing the risks of increased greenhouse gas (GHG) emissions from AI requires investment, expertise, and new approaches to building and operating many aspects of AI operation and supply chains. The immediate task is to understand these risks, gather the necessary information, and to avoid poor outcomes by proactively managing construction, operation, and emissions associated with the growth in AI. In parallel to that work, it's important to recognize that AI can itself be a real force to reduce emissions incrementally and dramatically across a wide range of sectors.
What Is the Carbon Footprint of AI?
The carbon footprint of AI consists of two main parts: "embodied" emissions that come from manufacturing IT equipment and constructing data centers, and "operational" emissions that come from electricity consumed by servers, memory and networking equipment as they perform AI-related calculations. Both of these aspects of emissions are growing as more data centers are built and existing data centers increase their share of power-hungry AI applications like generative LLM searches, AI agents, and AI image generation.
Understanding Electricity Demand for Data Centers
Today, the electricity demand from AI-specific applications is estimated to be less than 1% of global electricity use. To understand this number, it helps to start with the electricity consumed by the 12,000+ data centers worldwide, which was about 1.5% of global electricity consumption in 2024. (This excludes another 0.4% from cryptocurrency mining.) However, most of the computation at these data centers is not AI; instead, it's more conventional applications like e-commerce, video streaming, social media, and online gaming.
The amount of AI-based computation at data centers is hard to determine, but AI-dedicated accelerated servers consumed about one third of overall data center electricity in 2025, or roughly 0.5% of global electricity. Notably, this is projected to grow at 30% annually, much faster than conventional (non-AI) data center electricity use. However, that electricity use results in a relatively small share of greenhouse gas emissions: about 0.5% of global fuel combustion emissions, with AI data centers representing only a small portion of that value.
Still, the demand for AI applications is rapidly growing, and this is likely to drive up the electricity used by data centers and the associated greenhouse gas emissions. The most important implications of this trend are in the US, which hosts about half the world's data centers. Currently, data centers use about 4% of US electricity, but projections for the future range from a low of 9.5% to a high of 15.3% in 2030.
[cta]
How Electricity Sources Impact Data Center Emissions
A large increase in electricity use doesn't necessarily result in a similarly large increase in greenhouse gas emissions. Currently, a significant portion of the electricity powering data centers comes from zero-carbon sources such as wind and solar. This is partly because of large, corporate power-purchase agreements (PPAs) signed by leading data center operators, particularly Amazon, Meta and Google.
US technology companies have been buying renewable energy for years. Global corporate clean energy procurement hit a record 62 GW in 2024, then fell to 55.9 GW in 2025, the first annual decline in nearly a decade, as elevated power prices and policy uncertainty made even large buyers more selective. Meta, Amazon, Google, and Microsoft still accounted for roughly 49% of global clean energy procurement in 2025, with Meta and Amazon alone securing 20.4 GW combined, including 4.7 GW of nuclear power.
The use of low-carbon power means that the net emissions from these data centers is smaller than the electricity consumption numbers might suggest. Of course, a crucial consideration is whether this low-carbon power is truly "additional," meaning that it is being added to the grid and not simply taken away from other uses. Data center operators are also expanding beyond their traditional wind and solar PPAs by exploring novel approaches to try to meet this standard, including geothermal projects in the US and Taiwan.
However, the projected electricity demand from AI applications at data centers will be difficult to meet entirely with low-carbon power, at least in the near term. Despite installing over 43.2 GW of wind, solar and battery projects in the US in 2025, these generators face a long wait for interconnection approval in many parts of the country. Geothermal and hydro power, which offer steady ("baseload") low-carbon electricity, remain constrained in the near term. And the interest in scaling up nuclear power, from restarting full-scale reactors to novel small modular reactors (SMRs), faces significant regulatory, cost, and supply chain hurdles.
One important source of low-carbon electricity that has not received enough attention is natural gas-fired power equipped with carbon capture and storage (CCS). This technology has the potential to significantly reduce emissions from existing power plants and enable new projects to achieve near-zero emissions.
The Role of Embodied Emissions in Data Center Construction
Embodied emissions include all emissions associated with the extraction, production, transportation, construction, and disposal of materials used in construction.
The embodied emissions from constructing data centers are substantial, and include concrete, steel, and IT hardware. Scope 3 GHG emissions for data centers—which include embodied emissions—range from approximately one-third to two-thirds of overall lifetime emissions. At Microsoft, Scope 3 emissions made up about 86% of the company's total FY2025 footprint and grew roughly 12% year over year, with capital goods driving most of that increase. In FY2024, capital goods alone accounted for about 41% of Microsoft's Scope 3 emissions, and purchased goods and services (including IT hardware) accounted for another 34%. In response, Microsoft has started using wood in some data center construction to reduce this impact. While using wood offers a partial solution, it cannot fully offset the emissions of even a single facility, and wood supply chains remain limited.
Major data center operators are working hard to address this challenge, including emphasizing the need for standardized emissions measurements and disclosures for key building materials. Ultimately, achieving deeper decarbonization will require further action to address both operational and embodied emissions.
Eight Strategies to Reduce the Carbon Footprint of AI
1. Adapt Technology Architecture
Efficiency is the foundational strategy in any clean energy approach. As such, chipmakers are developing ways to cut energy use from the outset, such as incorporating more memory directly onto computer chips or hard-wiring basic calculations. These innovations have already reduced energy consumption in new computer chips substantially, in some cases a 96% improvement. Examples of this include NVIDIA's Blackwell platform and the company's newer Rubin platform, launched in 2026, continues that trajectory. Likewise, servers are being designed with new architectures that minimize internal data transfers, delivering additional efficiencies. Even more efficiency gains may be possible with emerging technologies like photonic computing.
2. Optimize Training Geography
There are also significant opportunities to manage AI's energy use through time and space optimization. For example, a large portion of the energy consumption for LLMs occurs during the training phase, prior to a model's deployment for inference. Because these training tasks are not location-dependent, they can be carried out in regions with abundant, low-cost, low-carbon electricity, as part of broader efforts to dynamically move computing tasks to reduce emissions, known as carbon-aware computing. Additionally, server requests for generative AI tasks, like ChatGPT searches, can potentially be routed through systems powered by low-carbon electricity. Although this may add only a few milliseconds of latency, it could substantially reduce emissions from computing operations.
3. Select Appropriately-Sized Models
Not all generative AI tasks, like ChatGPT queries, are equal in terms of energy demand. Leading AI companies are increasingly focusing on using smaller, more efficient AI models to perform these tasks, achieving nearly equivalent quality for far less energy consumption. A notable recent test of that idea came in January 2025, when China's DeepSeek released a model with competitive performance that was trained using less powerful chips and far fewer computing hours than its established rivals. Similarly, many AI applications, such as digital twinning and satellite-based pattern recognition, consume far less electricity than generative LLMs, because of their specialized, relatively efficient models. This can even save energy compared to non-AI approaches: for example, some of the most advanced AI-driven weather prediction models require far less energy than traditional weather simulations, running on a laptop rather than a supercomputer.
4. Address Fugitive Methane Emissions
As data center operators increasingly plan on using natural gas for new electricity supply, reducing upstream emissions from gas production and transmission will be crucial. In the U.S., the Environmental Protection Agency (EPA) 2024 Methane Rule was designed to cut these non-carbon dioxide greenhouse gas emissions by approximately 80%. However, Congress repealed the rule's methane fee in 2025 and barred the EPA from collecting it until 2034. The EPA has since extended compliance deadlines and loosened flare and vent-gas requirements, with litigation over those changes still ongoing. Meanwhile, tools from companies like Kayrros and organizations like Carbon Mapper help detect methane leaks and attribute them to specific operators. The best actors in the industry emit minimal methane, less than 0.5% of what is produced. This standard is achievable for nearly all gas producers.
5. Use Carbon Capture on Power Plants
For both new and existing natural gas-fired power plants, carbon capture and storage technology offers the potential for generating firm, low-carbon power. While many plants currently in operation continue to emit unchecked, this doesn't have to be the case: their emissions can be captured and securely stored geologically. Hyperscalers and project developers should pursue new investments and business models for CCS to reduce existing emissions by 95% or more. For new generation projects, options like NetPower, Arbor, and CES will soon enable emissions abatement of 100%, or even more if combined with biopower to deliver carbon dioxide removal as well. Achieving this will require the development of carbon dioxide pipelines, barges, and storage facilities, which face their own challenges, such as permitting and community approval, that must be addressed directly.
6. Add More Zero-Carbon Power to the Grid
Roughly 8,200 solar, wind, and battery projects in the U.S. are seeking grid interconnection. By the end of 2025, the interconnection queue held roughly 2,060 GW of proposed generation and storage across thousands of projects, and its composition shifted meaningfully. Solar, wind, and storage volumes in the queue all declined year over year (although remained at high absolute levels) while natural gas capacity in the queue grew by 86%. Our blog post, The $5.5 Billion-Dollar Case for Enabling Data Center Load Flexibility, covers one way hyperscalers are working around the wait rather than simply enduring it. These delays need to be addressed, and permitting reform remains an unresolved, live debate. The Manchin-Barrasso bill, which once looked likely to pass, was tabled in December 2024 and never became law. As of 2026, no comprehensive federal permitting law has replaced it. One potential innovation is to use AI to accelerate the development of power flow models and streamline the paperwork required to complete the regulatory process.
7. Invest in Low-Carbon Building Materials
While wood is a promising low-carbon building material, we'll also need glass, concrete, steel, aluminum, and computer chips with minimal embodied carbon emissions. Hyperscalers currently face significant challenges accessing low-carbon versions of these materials, which will eventually be produced using low-carbon hydrogen, carbon capture and storage, and low-carbon electricity. However, these systems require significant investment, workforce development, and permitting to be built. Without these advancements, the embodied emissions from data centers will increase rapidly and significantly in the US, Europe, and globally.
8. Increase Carbon Dioxide Removals
It's already clear that AI applications at data centers will generate emissions from electricity use and embodied carbon that cannot be avoided in the near term. Estimates of current greenhouse gas emissions exceed 300 million tons per year and are likely to grow this decade. These emissions should be measured using full life-cycle analysis and then offset through high-quality carbon removal projects, preferably those with high durability.
To effectively reduce the environmental impact of AI, all eight strategies discussed must prioritize the communities most affected: frontline communities near new infrastructure, consumers facing price increases, and tribal authorities with limited legal protections. Our own research on community opposition to AI data centers found that transparency, not cost or environmental impact alone, is the dominant driver of pushback across 46 stalled or blocked projects. We explore this concern further in our blog, Who Pays for the AI? The Hidden Costs of Rising Data Center Demand, including how ratepayers, not just data center operators, often absorb the cost of new grid infrastructure. Planning should begin by understanding the needs of these communities, ensuring that efforts focus on minimizing harm while maximizing benefits. Equity and justice must be embedded in every stage of planning, production, and permitting across all strategies.
AI's Power Demand Is Indicative of Broader Electricity Demand
AI is just one part of a broader trend of rapidly growing electricity demands, including from electric vehicles, heat pumps, industrial electrification, green hydrogen, and various e-fuels. The challenges AI presents to hyperscalers, communities, regulators, and investors serve as a preview of the complex, far-reaching impacts emerging in other sectors. The same questions keep recurring. Who secures reliable, affordable power fast enough? Who ends up carrying the cost and emissions burden of getting there the wrong way?
Managing AI's power demand will require building the technology architecture, clean firm power supply, and materials strategy to meet that demand deliberately, rather than reactively. AI's carbon footprint underscores the critical need for expertise in clean electricity, grid management, decarbonization, and carbon removal—expertise that will become increasingly vital as more companies realize the complexity and cost of the journey ahead.
Fortunately, AI itself can be part of the solution. With applications in grid management, material science, and advanced manufacturing, AI has the potential to play a powerful role in the climate response.
Read the full 2025 report: ICEF Sustainable Data Centers.
Frequently Asked Questions
How much electricity do AI data centers actually use?
AI-specific computation likely accounts for around 0.04% of global electricity use today, but data centers overall (most of it non-AI computation) used about 1.5% of global electricity in 2024. In the US, which hosts roughly half the world's data centers, Lawrence Berkeley National Laboratory puts current usage at 4% of US electricity, projected to reach 9.5-15.3% by 2030 as AI-specific demand grows.
Will more efficient AI models like DeepSeek reduce data center energy demand?
Not necessarily. DeepSeek's 2025 debut showed that competitive models can be trained with less powerful chips and fewer computing hours, but whether that translates into lower total energy demand is contested. Historically, efficiency gains in computing have tended to get absorbed by increased usage rather than reducing total consumption, so the honest answer is that it depends on whether demand growth outpaces the efficiency gained.
What is being done about the embodied emissions from building AI data centers?
Embodied emissions, from concrete, steel, and IT hardware, can account for one-third to two-thirds of a data center's lifetime emissions. Strategies include using lower-carbon materials like wood where feasible, developing low-carbon concrete, steel, and chips, and standardizing emissions disclosures for building materials so operators can compare and choose lower-footprint options.
Power & Energy
Relae provides independent advisory for large corporate buyers, power providers, and infrastructure investors making high-stakes decisions about clean firm power, grid constraints, data center energy optimization, and long-term investment strategy. Our insights help you evaluate solutions that can be deployed reliably, responsibly, and affordably, so you can navigate an evolving energy landscape with confidence.
Community Opposition to AI Data Centers: Lessons Learned


Julio Friedmann, PhD
Julio Friedmann, PhD

Dr. Friedmann is one of the most widely known and authoritative experts in the US on carbon removal (CO₂ drawdown from the air and oceans), CO₂ conversion and use (carbon-to-value), hydrogen, industrial decarbonization, green manufacturing, and carbon capture and sequestration.He served as Principal Deputy Assistant Secretary for the Office of Fossil Energy at the Department of Energy during the Obama Administration, where he was responsible for DOE's R&D program in advanced fossil energy systems, carbon capture, and storage (CCS), CO₂ utilization, and advanced power generation. More recently, he was a Senior Research Scholar at the Center on Global Energy Policy at Columbia. He has held positions at Lawrence Livermore National Laboratory, including Chief Energy Technologist.
Greenman Award (Lifetime achievement in CCS), International Energy Agency: IEA
Colin McCormick, PhD
Colin McCormick, PhD
Dr. Colin McCormick directs Relae's work in power and electricity, data center infrastructure, grid reliability, and space technologies. Trained as an optical physicist and data scientist, he conducted research in applied quantum optics and atomic physics at UC Berkeley and NIST. He previously served as the Senior Advisor for R&D at the US Department of Energy, overseeing the applied energy research portfolio in energy efficiency, renewables, energy storage, grid technologies, electric vehicles and related areas. Earlier, he was a Professional Staff Member for the House Science & Technology Committee, focusing on technology and innovation policy, data interoperability, and technical standards development. He is an Adjunct Professor in the Science, Technology and International Affairs program at Georgetown University where he teaches classes on deep decarbonization and AI & autonomous systems. He is also a Commissioner on the District of Columbia Commission on Climate Change and Resiliency. He has worked extensively with the Climate TRACE consortium, and is a member of the Carbon Mapper Science & Measurement Committee. He was previously a member of the WattTime Board of Directors.
Secretary of Energy Achievement Award, Getting to Neutral report (2021)
Secretary of Energy Appreciation Award (2010, 2012)
What to Read Next
Shifting Playbook for Corporate Power Procurement
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s proposed scope 2 revisions would shift many large power buyers from annual renewable energy certificate (REC) accounting to 24/7 hourly matching and reveal a larger emissions gap than most inventories currently report.
- Of all the US grid regions modeled, the emissions gap between annual and 24/7 hourly matching is widest in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the markets where data center load is growing fastest.
- Relae's modeling quantifies the shift from annual to 24/7 hourly matching: serving a 4-gigawatt (GW) data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM, a roughly 800-megawatt premium in PJM that translates directly into cost and siting strategy.
- Closing that gap requires investments in clean, firm generation technologies, like natural gas with carbon capture and storage (CCS), battery storage, and geothermal. The optimal mix varies by market and load profile, which means modeling current and future emissions positions under 24/7 accounting to understand the best procurement options for a specific portfolio.
Annual REC Accounting No Longer Holds at Data Center Scale
For years, large corporate energy buyers have relied on a straightforward approach: purchase renewable energy certificates (RECs) or sign virtual power purchase agreements (VPPAs) to offset market-based scope 2 emissions. Under the current GHG Protocol guidance, these instruments allow companies to claim low or zero emissions regardless of when or where clean energy is actually generated. When corporate clean energy demand was modest, this fueled new renewable project development while aggregate grid emissions were trending down.
That approach worked, until now. Energy demand from data centers and hyperscalers is surging. The Federal Energy Regulatory Commission (FERC) reported more than 50 GW of data center capacity operating in the US at the end of 2025, much of it concentrated in regions where local clean generation cannot keep pace. When corporate clean energy demand was modest, the gap between contractual claims and physical generation was small enough that few questioned this argument. At hyperscaler levels, with load concentrated in a handful of grids, that gap is becoming too large to ignore.
From a climate perspective, well-designed renewable procurement has created real impact by channeling corporate capital into new clean generation, and reducing CO2 emissions anywhere to benefit the climate everywhere. From a grid perspective, power consumption and generation must balance in real time, and the flow of electricity is constrained by the physics of the transmission system. Some regulators, investors, and standard-setters argue that corporate clean energy claims should be grounded in this second, engineering perspective rather than the first. The GHG Protocol's proposed revisions reflect that view, and would force buyers to defend their claims against it.
Relae’s modeling of this 24/7 framework in PJM and ERCOT helps quantify its costs and emissions implications in the markets where the stakes are highest.
What Does 24/7 Hourly Matching Mean for Scope 2 Accounting?
The biggest proposed change to the GHG Protocol’s current Scope 2 Guidance is the move from annual power reporting and matching to a 24/7 approach. Instead of calculating emissions with an annual emissions factor (EF) based on their independent system operator (ISO) or eGRID region for each megawatt-hour (MWh) consumed, companies would need to use hourly-specific EFs.
Companies would still be able to retire RECs to reduce their market-based emissions. However, companies would need to show that these RECs came from clean energy that was generated on the same grid, in the same hour as their facilities consumed power. This makes annual, location-agnostic REC retirement, currently the dominant practice, insufficient for 24/7 market-based accounting.
Both the time restriction (hourly matching) and the location restriction (generation on the same grid as consumption) will make it more difficult for companies to retire RECs. For example, because today's methodology is location-agnostic, a New York-based company can retire RECs from a Texas wind farm (purchased unbundled or via a VPPA) to reduce its reported market-based scope 2 value. This has allowed renewable development to follow the best resource sites rather than the load. Similarly, the time of day that the wind farm generates energy is irrelevant, as long as it is approximately in the same calendar year.
Under the proposed revisions, retiring these RECs would no longer be acceptable for the New York company, since they would fail both location- and hourly-matching requirements. As a result, companies with large REC portfolios today may no longer be able to retire them in order to reduce their market-based scope 2 emissions, if the proposed revisions take effect. These companies may face significant unmatched consumption under 24/7 accounting, especially during evening peaks or grid stress events when fossil-based generation fills the gap.
Annual Matching vs 24/7 Hourly Matching
The figure below illustrates the gap between what a representative large buyer reports under the current annual location- and market-based methodologies, versus what an hourly 24/7 analysis reveals.
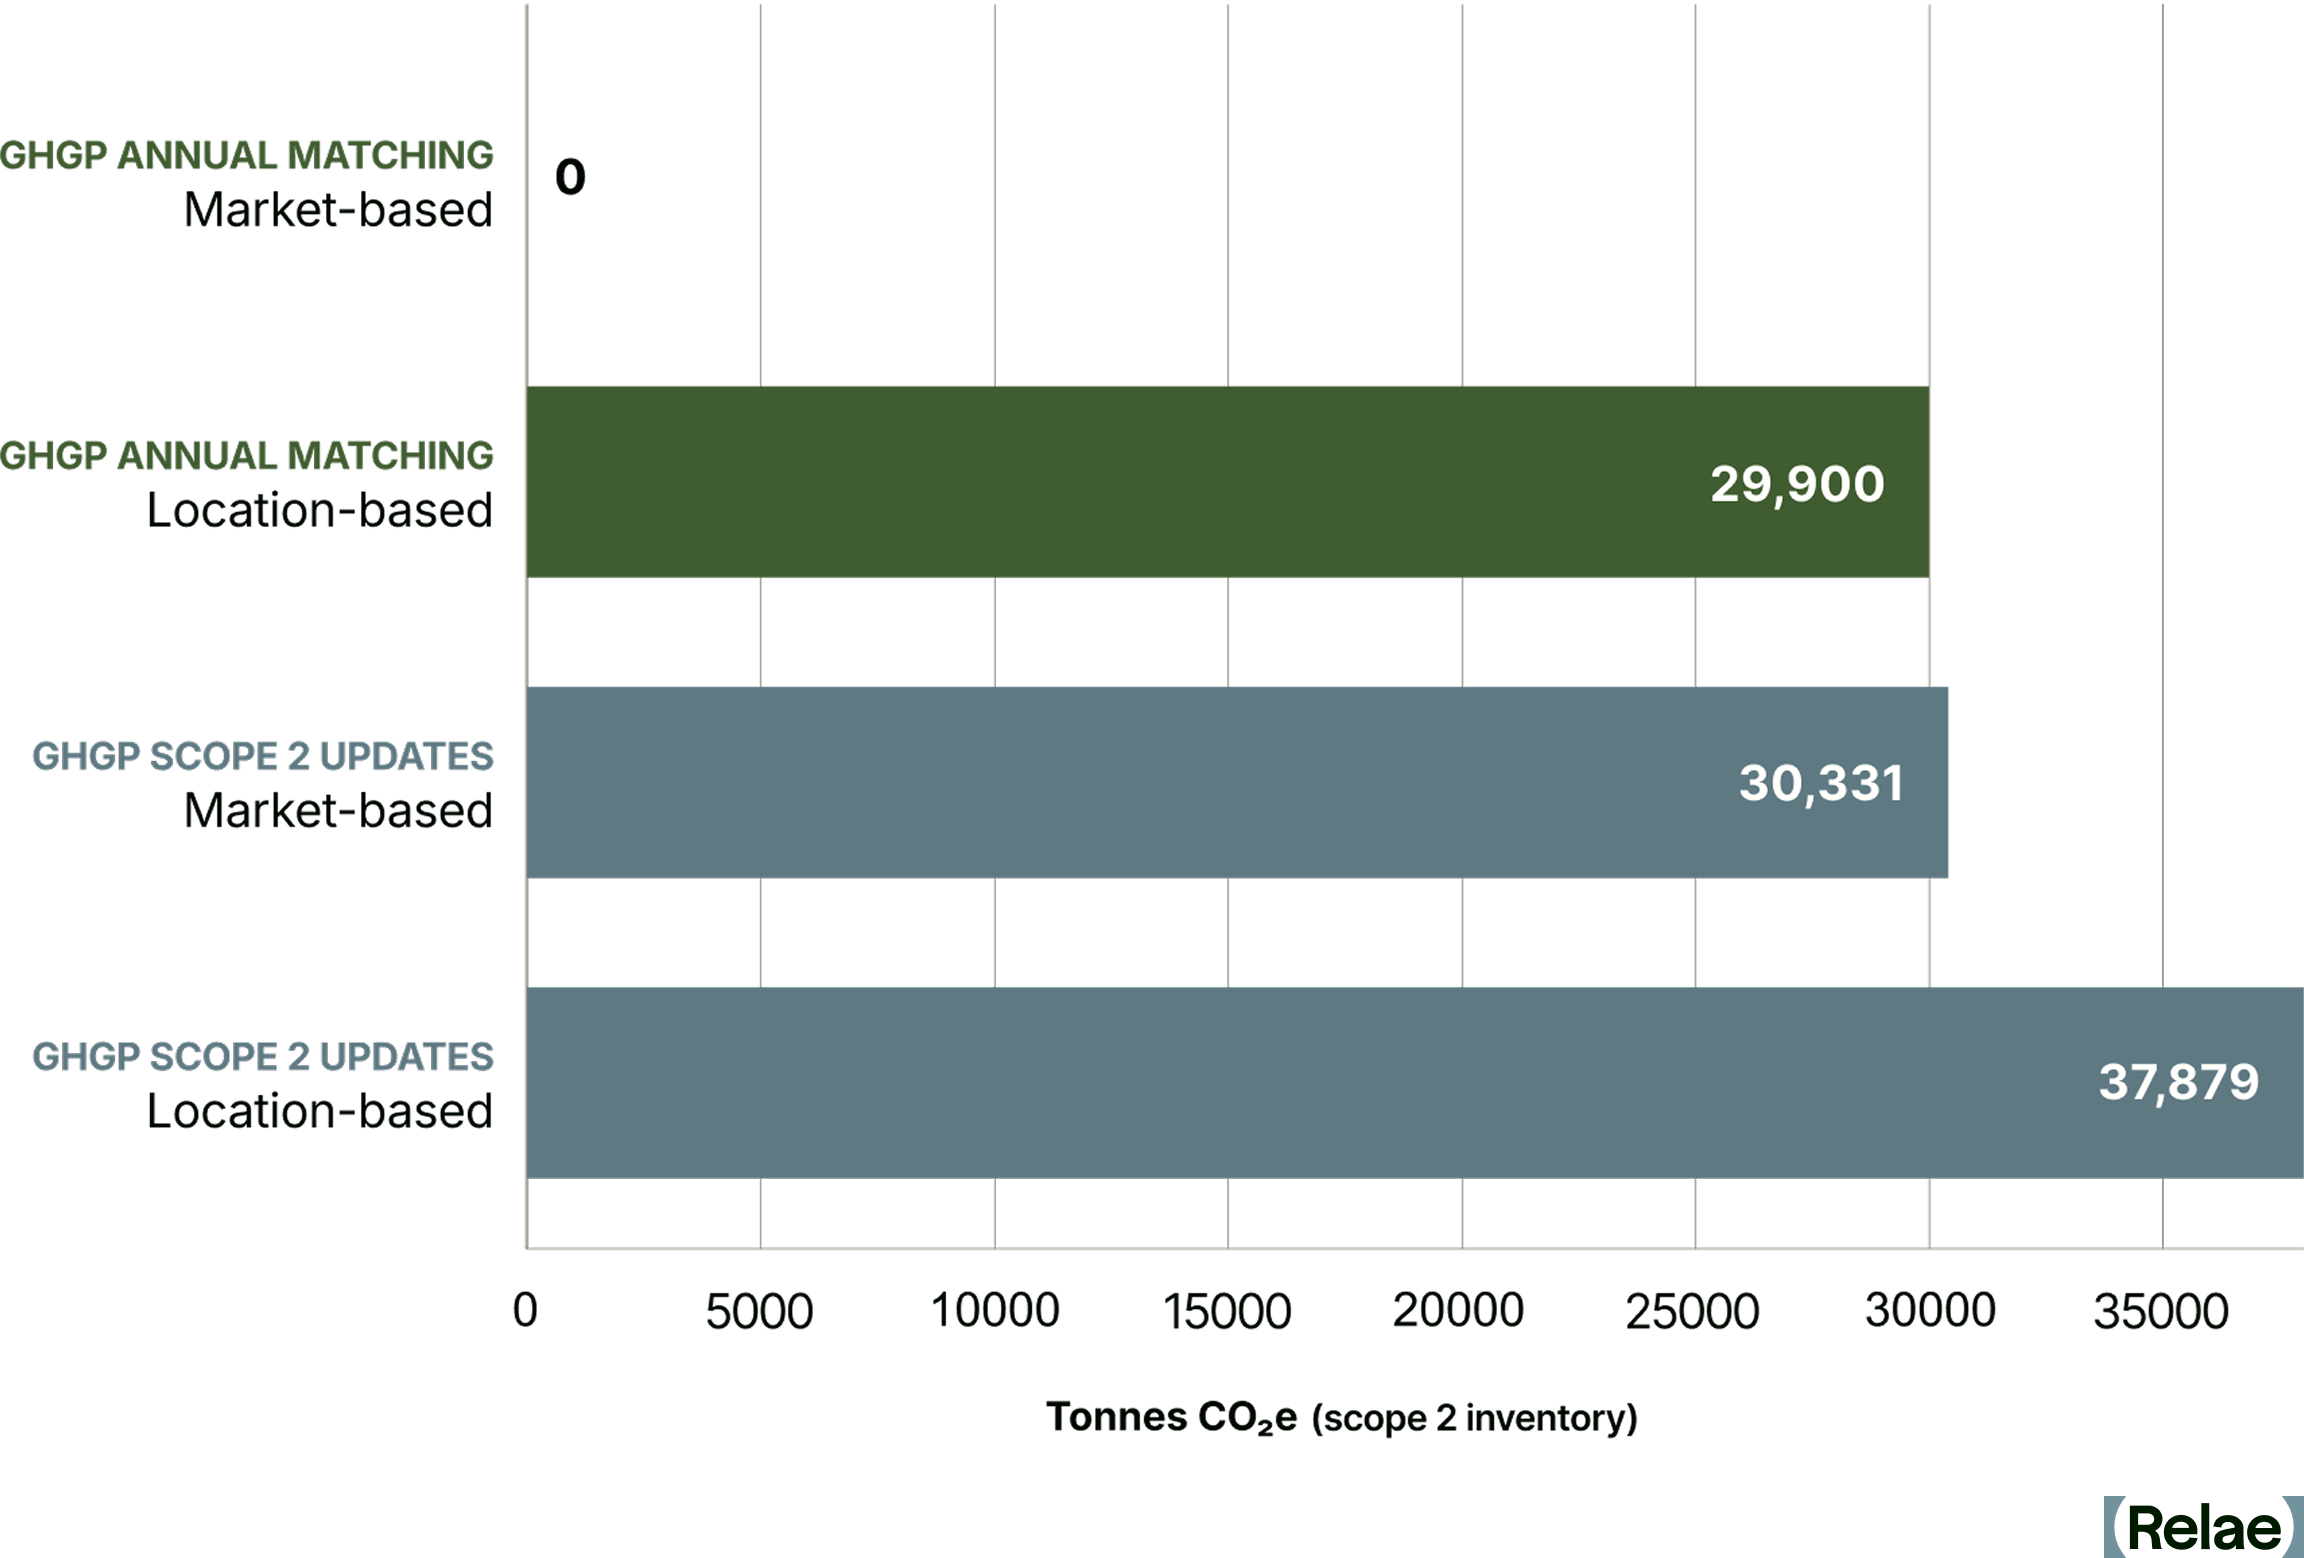
Understanding this emissions gap is the essential first step for buyers to make informed decisions about which instruments to retain, which contracts to renegotiate, and where new investment will matter most. If the proposed scope 2 revisions are enacted, companies procuring clean energy will be disincentivized from buying RECs sourced from variable renewables in distant locations, and instead will find it more favorable to invest in same-grid clean, firm generation, such as geothermal, nuclear, and renewables plus storage. RECs from these projects would qualify to be retired against market-based scope 2 emissions under the proposed revisions, where today's distant-wind or off-peak-solar RECs would not.
Where Pressure Is the Highest: ERCOT and PJM
Two markets stand out for projected hyperscaler load growth: PJM, which covers the extended mid-Atlantic region, and ERCOT in Texas. Both are on track to absorb massive increases in data center demand over the next decade, and both expose the limits of annual REC accounting in ways that will be hard to ignore under the new proposed framework.
PJM: 60% Fossil Generation Means High Marginal Emissions
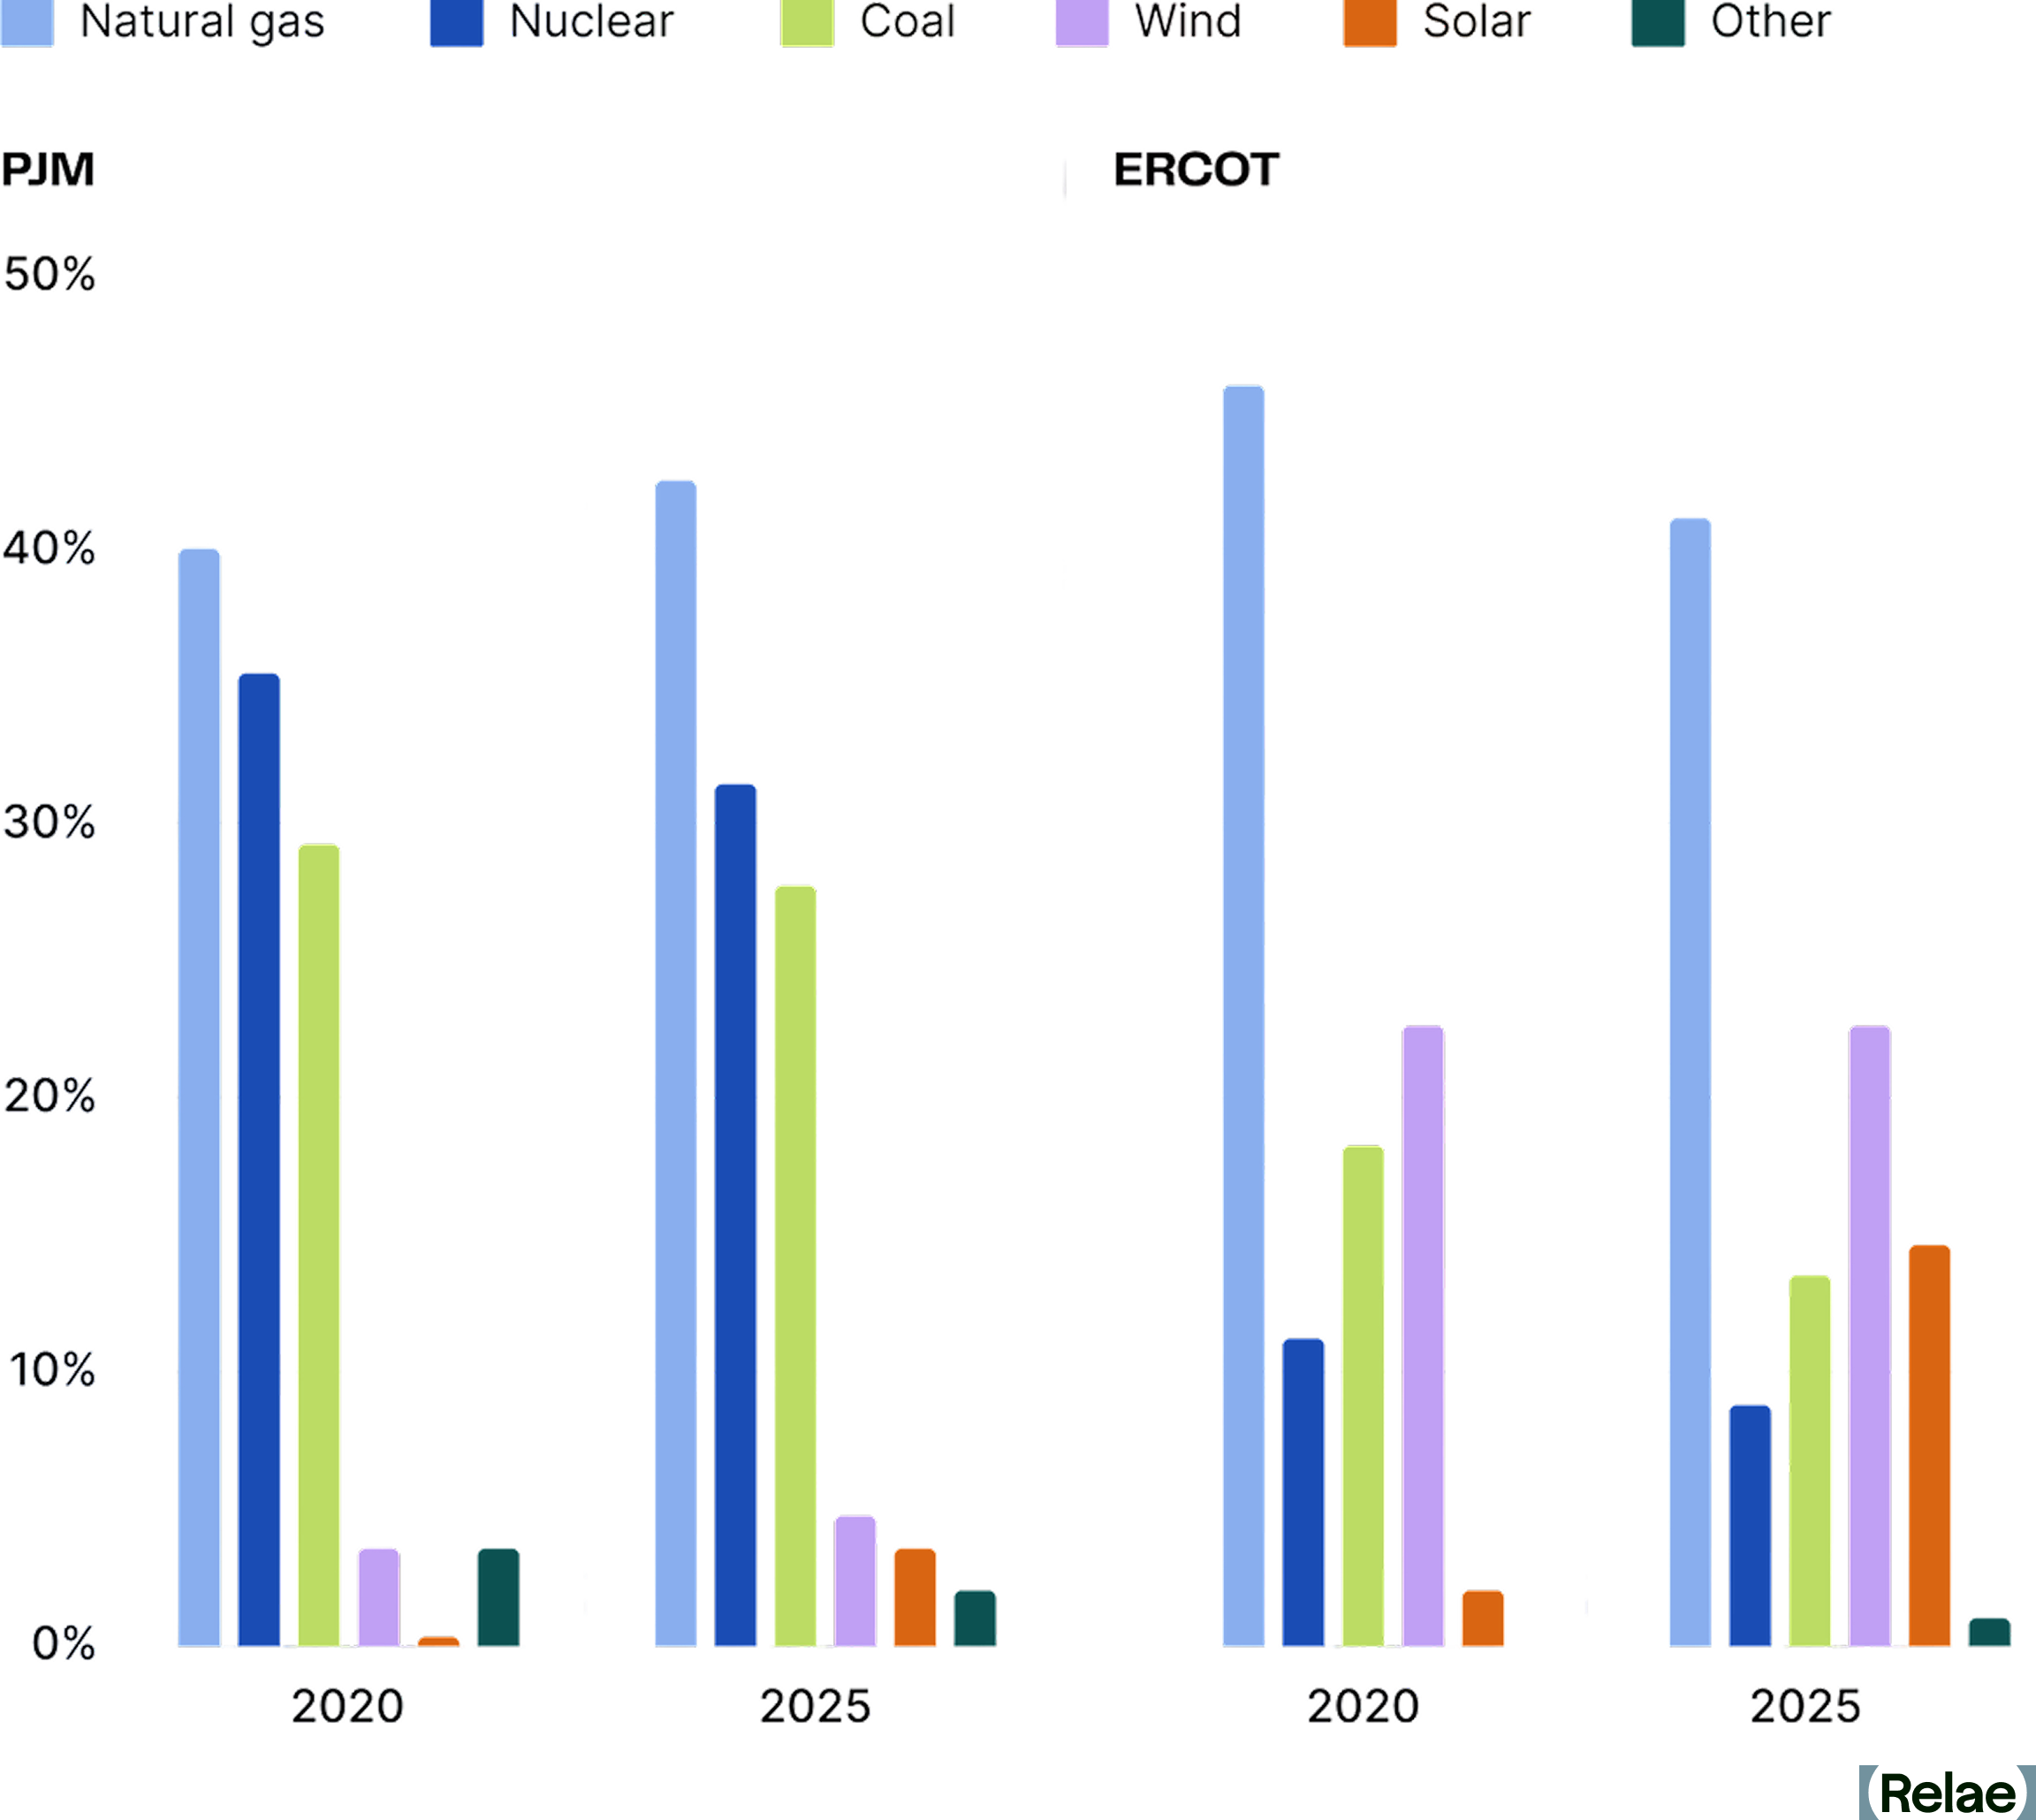
PJM is one of the largest and most complex wholesale electricity markets in the world. Its generation mix still includes 60% coal and natural gas, which means hourly emissions intensity remains high, particularly during evening peaks and grid stress events when fossil generation dominates the dispatch stack.
Buyers relying solely on annual REC retirement may show low market-based scope 2 emissions today, but a 24/7 analysis tells a different story. For PJM-based buyers, this means hourly matching gaps will be largest during evening and overnight hours, when nuclear and storage become disproportionately valuable relative to additional solar.
ERCOT: Solar and Wind Don’t Peak When Demand Does
Texas has abundant wind and solar, with solar generation growing nearly 7x since 2020, but those resources don’t always run when demand peaks. While fossil-based generation has declined since 2020, it still comprises more than half of ERCOT’s generation. Solar dominates midday, wind peaks in the evening, and natural gas fills the gaps, especially during high-demand evenings or extreme weather events.
Buyers with large ERCOT footprints may find that VPPA portfolios, which generate most of their clean energy in off-peak hours, already satisfy the proposed location-based test but fail on hourly matching. Battery storage and demand flexibility could help bridge the gap.
Figure 3 below quantifies that gap in both markets by showcasing the carbon-free energy (CFE) score in ERCOT and PJM, as well as the additional capacity required for a 4 GW load to achieve a 100% CFE target. The CFE score is the share of grid-supplied electricity in a given hour that comes from carbon-free sources, and is the metric the proposed scope 2 revisions would use to evaluate hourly matching. A 100% CFE target means electricity consumption is matched to carbon-free generation in every hour of the year.
In the left panel, a representation1 of each market's 2030 hours are sorted by grid (CFE) score, from the dirtiest hour on the left to the cleanest on the right. Neither grid approaches 100% carbon-free on its own, and the shaded areas represent the unmatched hours a buyer claiming 100% clean energy through annual instruments would actually carry under 24/7 accounting. The gap is the maximum unmatched hours a buyer might be exposed to, as some RECs procured through annual matching may qualify under the new rules, if satisfying the locational and hourly requirements.
The right panel translates that gap into action. The additional co-located clean generation and storage required to serve a representative 4 GW load (roughly 5% of the forecast 2030 C&I load in ERCOT and 4% in PJM) at a 100% hourly CFE target, on top of what the underlying grid already provides.
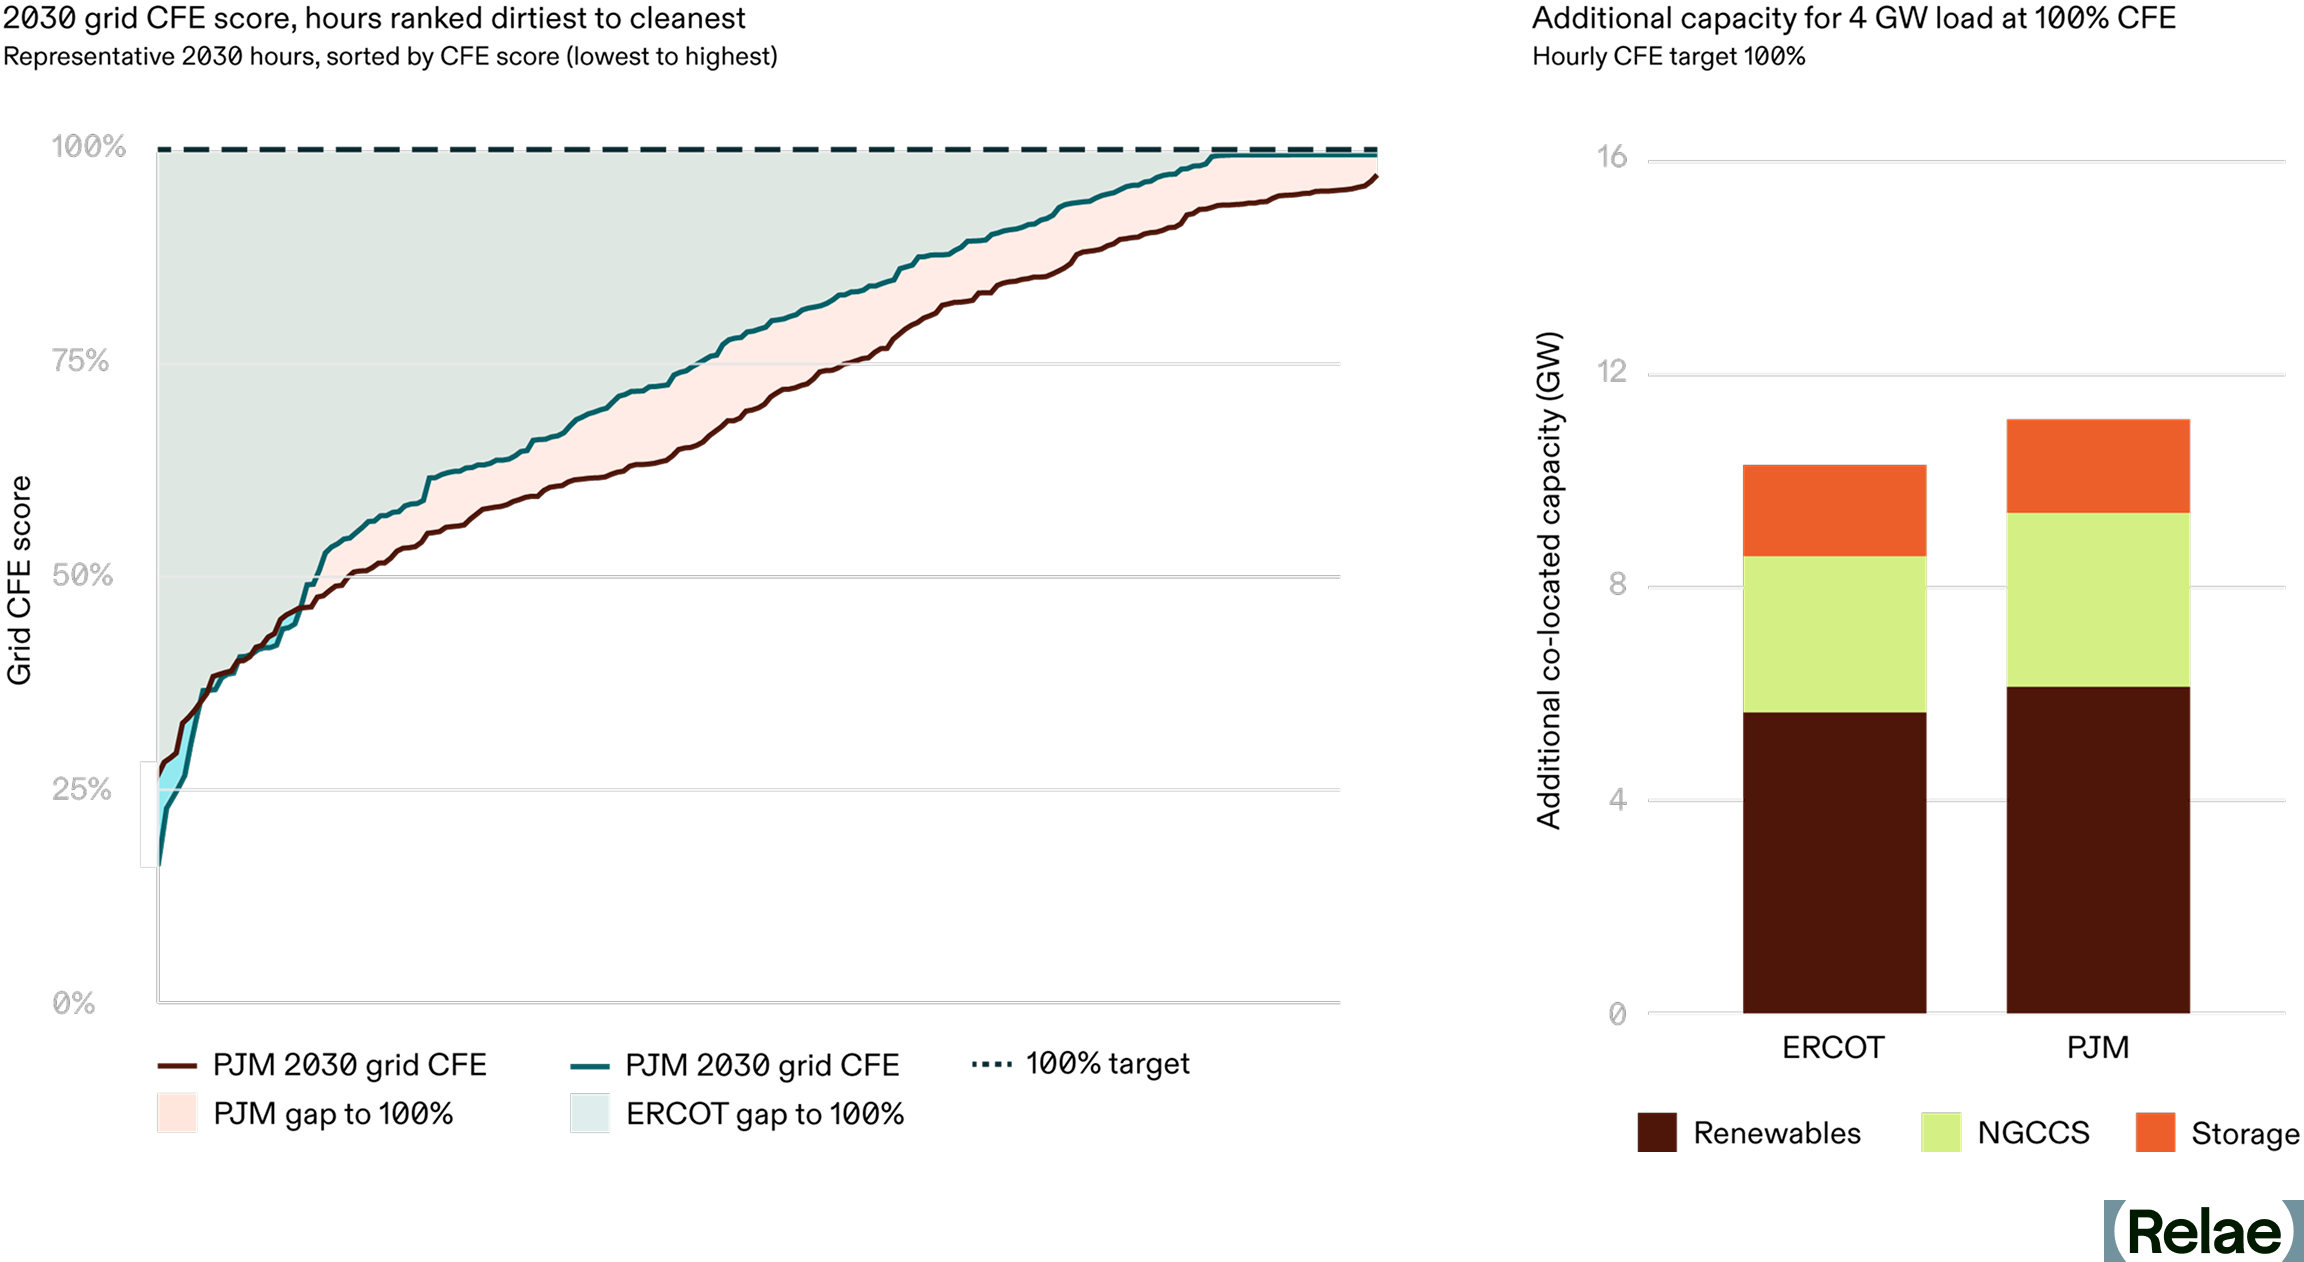
A few patterns are worth highlighting. First, the left panel confirms that PJM’s grid will still spend materially more hours below 100% carbon-free than ERCOT’s in 2030, a direct consequence of the coal- and gas-heavy generation mix described above. Notably, ERCOT's curve reaches 100% in a meaningful share of hours (windows when the grid is running entirely on carbon-free resources), while PJM's never does, meaning some fossil generation is dispatched in every hour.
Second, the ISO a buyer operates in drives a meaningful difference in build-out: hitting 100% hourly CFE for a 4 GW load takes 9.6 GW of additional capacity in ERCOT and closer to 10.5 GW in PJM. This indicates the advantage of achieving hourly and locational matching in already clean grids, which may influence a buyer choosing where to site new workloads.
Renewables have the largest share of the additional capacity in both markets (5-6 GW), paired with significant long-duration energy storage (~2 GW), while natural gas with CCS provides meaningful clean, firm capacity (~3 GW). ERCOT’s storage share of capacity is slightly larger, reflecting the midday-solar/evening-load mismatch, while PJM leans a bit more on natural gas with CCS, where clean, firm generation does more of the heavy lifting due to lower wind speeds and solar irradiance than Texas.
The right panel also illustrates why clean, firm technologies (natural gas with CCS, advanced nuclear, and enhanced geothermal) are likely to be included alongside renewables and batteries in any serious 24/7 portfolio. With only renewables and batteries, hitting the same target requires about double the total generation and storage capacity. In both markets, targets that look achievable today on an annual REC basis will require materially more capital and a different mix of resources, under 24/7 accounting.
Top Questions Large Power Buyers Need to Model Before the Rules Change
The GHG Protocol revisions are not finalized, and the timing of any mandate remains uncertain, which is exactly why modeling cannot wait.
A useful self-test for any large power buyer is: can your team answer the following today with defensible numbers?
- What is your hourly CFE score across your largest load centers, and how far does it sit from your reported market-based emissions?
- Which of your existing VPPAs and REC contracts hold value under 24/7 accounting, and which become effectively stranded?
- What mix of resources delivers the incremental clean, firm capacity that closes your gap in PJM, ERCOT, or wherever your load is concentrated at the lowest cost?
- If your next gigawatt of load were sited in a different ISO, how would your emissions position change?
Clean firm projects do not appear off the shelf. Advanced nuclear, enhanced geothermal, and natural gas with CCS all carry multi-year development timelines, and corporate offtake agreements are often what get these projects financed in the first place. Buyers who engage now help shape the project pipeline that will be available in their target markets in 2030, and can lock in offtake terms before competition for the most valuable sites tightens. Buyers who wait until the methodology is final will be working with shorter lead times, fewer development partners, and less leverage to specify projects that fit their load profiles and hourly matching needs.
Frequently Asked Questions
What is 24/7 hourly matching, and how does it differ from today's REC accounting?
Today's scope 2 accounting lets companies retire renewable energy certificates (RECs) from any grid, at any time of year, to offset their emissions. The GHG Protocol's proposed 24/7 hourly matching would require RECs to come from clean generation on the same grid, in the same hour a facility consumes power, making most of today's location-agnostic RECs ineligible for market-based accounting.
Why are PJM and ERCOT under the most pressure from this shift?
Both markets are absorbing the fastest-growing data center load in the country, and both still lean on fossil generation to meet demand outside peak renewable hours. PJM's generation mix is 60% coal and gas, while ERCOT's solar and wind often don't peak when demand does, so buyers in these markets face the largest gaps between their annual REC claims and their actual hourly carbon-free energy score.
How much additional clean capacity does it take to close the gap?
Relae's modeling finds that serving a 4 GW data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM. That capacity mix leans on renewables and long-duration storage in both markets, with natural gas with CCS playing a larger role in PJM, where wind and solar resources are weaker.
What should power buyers do before the GHG Protocol revisions are finalized?
Start modeling now. Buyers should know their hourly carbon-free energy score, understand which existing VPPAs and REC contracts hold value under 24/7 accounting, and identify the lowest-cost mix of clean, firm resources that closes their gap. Clean firm projects like advanced nuclear, enhanced geothermal, and natural gas with CCS take years to develop, so buyers who engage early have more influence over the project pipeline and better offtake terms.
Modeling the 24/7 Emissions Gap with Relae
For large power buyers assessing what the proposed GHG Protocol revisions mean for their power procurement portfolio, Relae's Advanced Power Emissions Analysis solution models the gap between current market-based reporting and what 24/7 accounting would reveal—by market, load profile, and technology stack.
AI Scale and Climate Commitments: A 2026 Outlook
The AI and Climate Execution Challenge
Data center energy capacity in the US is projected to increase from 25 GW to 120 GW by 2030—a fivefold increase. Hyperscalers are projected to invest $7 trillion globally in data center infrastructure through 2030, with approximately $2.8 trillion invested in the US.
While 2025 was defined by a 'scale at all costs' scramble for compute, in 2026, the new mandate is responsible scale: reconciling voracious power demands with aggressive net-zero commitments and rising energy costs.
Grid constraints determine the geography and velocity of growth, forcing companies into complex trade-offs between speed-to-market and “clean, firm” power, which can take years to develop. Evolving carbon accounting rules are shifting procurement strategies and infrastructure choices at this trillion-dollar scale, creating a “carbon debt”—embodied emissions that will stay on the books for decades. In 2026, the competitive advantage likely belongs to those who integrate power, hardware, and climate strategy from day one.
Powering AI: Grid Reliability, Constraints, and Interconnection
Grid infrastructure faces reliability challenges from aging systems and capacity constraints. Interconnection queues stretch three to five years for renewables, while large electrical load interconnection lacks consistent standards.
Federal Regulatory Response
The federal government is moving to standardize these processes, with a critical decision point in 2026. For companies planning data center deployments in 2026, understanding these regulatory shifts is likely essential to realistic timeline and site selection planning.
On October 30, 2025, the US Department of Energy (DOE) leveraged Section 403(a) of the DOE Organization Act to direct the Federal Energy Regulatory Commission (FERC) to issue a rulemaking to “ensure efficient, timely, and non-discriminatory load interconnections” for large (>20 MW) electrical loads.
By April 30, 2026, FERC is expected to issue a final rule on large electrical load interconnections for grid operators, providing federal regulations for approval pathways, timelines, and rates.
Public comments on DOE’s advanced notice of proposed rulemaking were due on December 5, 2025, and grid operators, utilities, NGOs, and customers submitted over 150 comments reflecting a wide range of perspectives.
While federal standardization should reduce procedural uncertainty, it doesn't create new grid capacity. Even with clearer approval pathways, the underlying supply-demand mismatch remains a primary gating factor for growth.
Bridging the Supply-Demand Gap
Data center energy demand is surging, but new clean electricity generation takes years to build. This mismatch between accelerating demand and slow-building supply is forcing the industry to pursue solutions on two timelines: near-term load flexibility strategies that unlock existing capacity, and long-term generation investments that build new power supply.
Load Flexibility: Near-Term Grid Access
Load flexibility is emerging as a possible path to faster grid connection. Oracle, NVIDIA, Emerald AI, and Salt River Project's joint research demonstrated 25% power reduction during peak hours through workload tiering. The demonstration shows that if data centers reduce consumption during peak times (roughly 1% of the year), it unlocks 126 GW of currently constrained capacity that could be available now.
Large power loads increasingly face incentives or mandates to demonstrate flexibility as part of interconnection agreements, making this an access requirement, not an optional efficiency measure. For example, Senate Bill 6 in Texas mandates that data centers and other large loads must reduce their consumption during certain grid peak times. Many other state legislatures are passing legislation that will impact data centers.
Storage has shifted from smoothing renewables to enabling multiple strategies: making intermittent renewables firmer, providing grid reliability services, and supporting 24/7 matching. Storage may emerge as a solution to allow data centers to reduce grid consumption during peak hours while maintaining operations.
Relae helps clients design load flexibility strategies under evolving regulatory frameworks: evaluating behind-the-meter generation options, sizing storage for peak reduction scenarios, and structuring interconnection configurations that preserve optionality across accounting methodologies.
Clean Firm Power: Long-Term Generation
Hyperscalers remain committed to clean, firm generation that’s reliable: power that's both low-carbon and dispatchable 24/7. Natural gas with carbon capture and storage (CCS) is emerging as a critical bridge technology. Google's 400 MW CCS power agreement with Broadwing, expected online in 2029, demonstrates commercial demand at scale.
In our analysis evaluating CCS pathways, commercial viability depends on rigorous assessment of permitting timelines, capital and operating costs, storage geology, vendor compatibility, and 45Q tax credit optimization. Execution has been most prevalent where technology intersects with regulatory approval and storage access.
Hyperscalers are also investing across geothermal, nuclear, including Small Modular Reactors (SMR), hydrogen, and fusion. Long-duration energy storage has also been an area of focus. Each has different risk profiles and opportunities across technical maturity, permitting, commercial viability, emission accounting methodology, dispatchability, and political support.
Evaluating these pathways requires multi-dimensional frameworks. Each technology faces distinct challenges: SMRs struggle with execution complexity, geothermal with extended development periods, and hydrogen with production-dependent carbon intensity. Tax credit eligibility (particularly 45Q for CCS and 45V for hydrogen) significantly impacts project economics.
Both power generation and data center Infrastructure site selection require integrating environmental and social vulnerability data to avoid community conflicts that delay or stop projects.
Power Accounting Rules Determine Clean Energy Procurement
The Greenhouse Gas (GHG) Protocol extended the public consultation period for proposed scope 2 guidance changes to January 31, 2026. The results will determine clean energy procurement strategies and the carbon value of load flexibility for the next decade.
The proposed shift in electricity emissions accounting could increase clean energy procurement costs for buyers. The accounting methodological debates matter for hyperscalers: 24×7 energy matching versus carbon matching. The issues of deliverability (being located in the same grid region) and additionality (being new, rather than repurposed, generation) are also hotly debated.
These different frameworks strongly influence whether natural gas with CCS, nuclear, geothermal, or battery-backed renewables are considered optimal for a site, and whether load flexibility has carbon value.
Companies need to model scenarios across advanced power emissions methodologies, evaluating portfolio costs and carbon performance before final standards are published in 2027. Companies are also signing forward renewable energy certificate contracts (RECs) and structuring power purchase agreements (PPAs) now to preserve optionality across scenarios.
AI Infrastructure Emissions at Scale
Data center construction creates substantial scope 3 emissions, and their relative importance depends on grid carbon intensity. For facilities powered by average-carbon grids, scope 2 operational emissions dominate. But for data centers powered by very low-carbon electricity (renewables or nuclear), scope 3 embodied emissions can represent 40% of total lifetime greenhouse gas emissions.
In AI data centers, IT equipment drives the majority of embodied emissions. Chips and memory account for 67%, followed by structural materials at 17%, with server power supplies, aluminum, and other components comprising the final 16%.
Direct procurement of low-carbon materials faces constraints: limited supply, geographic concentration, and contracting complexity. Environmental Attribute Credits (EACs) provide an interim pathway by decoupling environmental benefits from physical materials, but require rigorous quality standards and verification to ensure real emissions reductions.
Our high-quality EAC criteria, developed with Microsoft, establish standards that separate market-making from greenwashing. Levelized Cost of Carbon Abatement frameworks make materials decisions comparable to power decisions, treating infrastructure decarbonization as portfolio optimization, not separate workstreams.
Carbon Removal: Addressing Residual Emissions
Complete supply chain decarbonization by 2030 isn't feasible. Despite aggressive efforts to procure clean power and reduce construction emissions, residual emissions will remain significant. For hyperscalers with net-zero commitments, carbon dioxide removal (CDR) has shifted from an optional component to a structural necessity. Microsoft remains the world's largest CDR buyer, and Google increased purchases 14-fold from 2023 to 2024.
CDR credit quality varies widely. Companies must apply science-based principles to evaluate credits. Our Criteria for High-Quality CDR, developed in collaboration with Microsoft, establishes six science-based principles for evaluating credits—critical as emerging hyperscaler and other corporate demand high-integrity supply.
AI and Climate: Looking Ahead
The window for strategic maneuvering is narrow. The AI infrastructure buildout is happening now, and the decisions made in 2026 will impact a company’s cost structure and carbon profile for years.
Companies treating power, infrastructure, and decarbonization as separate workstreams will face compounding constraints. The winners of the AI era will be those who integrate power, infrastructure, and carbon strategy into a single, cohesive system.
Understanding the Carbon Footprint of AI and How to Reduce It
Key Takeaways
- AI's carbon footprint has two distinct parts: embodied emissions from building data centers and operational emissions from running them, both accelerating as global data center electricity use is set to double by 2030, and AI-focused use to triple.
- Managing that footprint will require deliberately steering technology architecture, power sourcing, and materials choices, instead of leaving them to react to demand after the fact.
- Eight concrete strategies, from smarter chip design to firm clean power and carbon removal, can cut AI's footprint today, without waiting on new regulation.
- US data centers used 4% of the USA's total electricity in 2024, and are projected to use as much as 15% by 2030.
Introduction
The rapid growth of artificial intelligence (AI), particularly large-language models (LLM) and generative AI, has taken many by surprise. This surge has led to escalating electricity demands at data centers and raised concerns about the strain on the power grid. It has also sparked the construction of new, larger data centers, resulting in growing embodied emissions tied to building and maintaining AI physical infrastructure.
Managing the risks of increased greenhouse gas (GHG) emissions from AI requires investment, expertise, and new approaches to building and operating many aspects of AI operation and supply chains. The immediate task is to understand these risks, gather the necessary information, and to avoid poor outcomes by proactively managing construction, operation, and emissions associated with the growth in AI. In parallel to that work, it's important to recognize that AI can itself be a real force to reduce emissions incrementally and dramatically across a wide range of sectors.
What Is the Carbon Footprint of AI?
The carbon footprint of AI consists of two main parts: "embodied" emissions that come from manufacturing IT equipment and constructing data centers, and "operational" emissions that come from electricity consumed by servers, memory and networking equipment as they perform AI-related calculations. Both of these aspects of emissions are growing as more data centers are built and existing data centers increase their share of power-hungry AI applications like generative LLM searches, AI agents, and AI image generation.
Understanding Electricity Demand for Data Centers
Today, the electricity demand from AI-specific applications is estimated to be less than 1% of global electricity use. To understand this number, it helps to start with the electricity consumed by the 12,000+ data centers worldwide, which was about 1.5% of global electricity consumption in 2024. (This excludes another 0.4% from cryptocurrency mining.) However, most of the computation at these data centers is not AI; instead, it's more conventional applications like e-commerce, video streaming, social media, and online gaming.
The amount of AI-based computation at data centers is hard to determine, but AI-dedicated accelerated servers consumed about one third of overall data center electricity in 2025, or roughly 0.5% of global electricity. Notably, this is projected to grow at 30% annually, much faster than conventional (non-AI) data center electricity use. However, that electricity use results in a relatively small share of greenhouse gas emissions: about 0.5% of global fuel combustion emissions, with AI data centers representing only a small portion of that value.
Still, the demand for AI applications is rapidly growing, and this is likely to drive up the electricity used by data centers and the associated greenhouse gas emissions. The most important implications of this trend are in the US, which hosts about half the world's data centers. Currently, data centers use about 4% of US electricity, but projections for the future range from a low of 9.5% to a high of 15.3% in 2030.
[cta]
How Electricity Sources Impact Data Center Emissions
A large increase in electricity use doesn't necessarily result in a similarly large increase in greenhouse gas emissions. Currently, a significant portion of the electricity powering data centers comes from zero-carbon sources such as wind and solar. This is partly because of large, corporate power-purchase agreements (PPAs) signed by leading data center operators, particularly Amazon, Meta and Google.
US technology companies have been buying renewable energy for years. Global corporate clean energy procurement hit a record 62 GW in 2024, then fell to 55.9 GW in 2025, the first annual decline in nearly a decade, as elevated power prices and policy uncertainty made even large buyers more selective. Meta, Amazon, Google, and Microsoft still accounted for roughly 49% of global clean energy procurement in 2025, with Meta and Amazon alone securing 20.4 GW combined, including 4.7 GW of nuclear power.
The use of low-carbon power means that the net emissions from these data centers is smaller than the electricity consumption numbers might suggest. Of course, a crucial consideration is whether this low-carbon power is truly "additional," meaning that it is being added to the grid and not simply taken away from other uses. Data center operators are also expanding beyond their traditional wind and solar PPAs by exploring novel approaches to try to meet this standard, including geothermal projects in the US and Taiwan.
However, the projected electricity demand from AI applications at data centers will be difficult to meet entirely with low-carbon power, at least in the near term. Despite installing over 43.2 GW of wind, solar and battery projects in the US in 2025, these generators face a long wait for interconnection approval in many parts of the country. Geothermal and hydro power, which offer steady ("baseload") low-carbon electricity, remain constrained in the near term. And the interest in scaling up nuclear power, from restarting full-scale reactors to novel small modular reactors (SMRs), faces significant regulatory, cost, and supply chain hurdles.
One important source of low-carbon electricity that has not received enough attention is natural gas-fired power equipped with carbon capture and storage (CCS). This technology has the potential to significantly reduce emissions from existing power plants and enable new projects to achieve near-zero emissions.
The Role of Embodied Emissions in Data Center Construction
Embodied emissions include all emissions associated with the extraction, production, transportation, construction, and disposal of materials used in construction.
The embodied emissions from constructing data centers are substantial, and include concrete, steel, and IT hardware. Scope 3 GHG emissions for data centers—which include embodied emissions—range from approximately one-third to two-thirds of overall lifetime emissions. At Microsoft, Scope 3 emissions made up about 86% of the company's total FY2025 footprint and grew roughly 12% year over year, with capital goods driving most of that increase. In FY2024, capital goods alone accounted for about 41% of Microsoft's Scope 3 emissions, and purchased goods and services (including IT hardware) accounted for another 34%. In response, Microsoft has started using wood in some data center construction to reduce this impact. While using wood offers a partial solution, it cannot fully offset the emissions of even a single facility, and wood supply chains remain limited.
Major data center operators are working hard to address this challenge, including emphasizing the need for standardized emissions measurements and disclosures for key building materials. Ultimately, achieving deeper decarbonization will require further action to address both operational and embodied emissions.
Eight Strategies to Reduce the Carbon Footprint of AI
1. Adapt Technology Architecture
Efficiency is the foundational strategy in any clean energy approach. As such, chipmakers are developing ways to cut energy use from the outset, such as incorporating more memory directly onto computer chips or hard-wiring basic calculations. These innovations have already reduced energy consumption in new computer chips substantially, in some cases a 96% improvement. Examples of this include NVIDIA's Blackwell platform and the company's newer Rubin platform, launched in 2026, continues that trajectory. Likewise, servers are being designed with new architectures that minimize internal data transfers, delivering additional efficiencies. Even more efficiency gains may be possible with emerging technologies like photonic computing.
2. Optimize Training Geography
There are also significant opportunities to manage AI's energy use through time and space optimization. For example, a large portion of the energy consumption for LLMs occurs during the training phase, prior to a model's deployment for inference. Because these training tasks are not location-dependent, they can be carried out in regions with abundant, low-cost, low-carbon electricity, as part of broader efforts to dynamically move computing tasks to reduce emissions, known as carbon-aware computing. Additionally, server requests for generative AI tasks, like ChatGPT searches, can potentially be routed through systems powered by low-carbon electricity. Although this may add only a few milliseconds of latency, it could substantially reduce emissions from computing operations.
3. Select Appropriately-Sized Models
Not all generative AI tasks, like ChatGPT queries, are equal in terms of energy demand. Leading AI companies are increasingly focusing on using smaller, more efficient AI models to perform these tasks, achieving nearly equivalent quality for far less energy consumption. A notable recent test of that idea came in January 2025, when China's DeepSeek released a model with competitive performance that was trained using less powerful chips and far fewer computing hours than its established rivals. Similarly, many AI applications, such as digital twinning and satellite-based pattern recognition, consume far less electricity than generative LLMs, because of their specialized, relatively efficient models. This can even save energy compared to non-AI approaches: for example, some of the most advanced AI-driven weather prediction models require far less energy than traditional weather simulations, running on a laptop rather than a supercomputer.
4. Address Fugitive Methane Emissions
As data center operators increasingly plan on using natural gas for new electricity supply, reducing upstream emissions from gas production and transmission will be crucial. In the U.S., the Environmental Protection Agency (EPA) 2024 Methane Rule was designed to cut these non-carbon dioxide greenhouse gas emissions by approximately 80%. However, Congress repealed the rule's methane fee in 2025 and barred the EPA from collecting it until 2034. The EPA has since extended compliance deadlines and loosened flare and vent-gas requirements, with litigation over those changes still ongoing. Meanwhile, tools from companies like Kayrros and organizations like Carbon Mapper help detect methane leaks and attribute them to specific operators. The best actors in the industry emit minimal methane, less than 0.5% of what is produced. This standard is achievable for nearly all gas producers.
5. Use Carbon Capture on Power Plants
For both new and existing natural gas-fired power plants, carbon capture and storage technology offers the potential for generating firm, low-carbon power. While many plants currently in operation continue to emit unchecked, this doesn't have to be the case: their emissions can be captured and securely stored geologically. Hyperscalers and project developers should pursue new investments and business models for CCS to reduce existing emissions by 95% or more. For new generation projects, options like NetPower, Arbor, and CES will soon enable emissions abatement of 100%, or even more if combined with biopower to deliver carbon dioxide removal as well. Achieving this will require the development of carbon dioxide pipelines, barges, and storage facilities, which face their own challenges, such as permitting and community approval, that must be addressed directly.
6. Add More Zero-Carbon Power to the Grid
Roughly 8,200 solar, wind, and battery projects in the U.S. are seeking grid interconnection. By the end of 2025, the interconnection queue held roughly 2,060 GW of proposed generation and storage across thousands of projects, and its composition shifted meaningfully. Solar, wind, and storage volumes in the queue all declined year over year (although remained at high absolute levels) while natural gas capacity in the queue grew by 86%. Our blog post, The $5.5 Billion-Dollar Case for Enabling Data Center Load Flexibility, covers one way hyperscalers are working around the wait rather than simply enduring it. These delays need to be addressed, and permitting reform remains an unresolved, live debate. The Manchin-Barrasso bill, which once looked likely to pass, was tabled in December 2024 and never became law. As of 2026, no comprehensive federal permitting law has replaced it. One potential innovation is to use AI to accelerate the development of power flow models and streamline the paperwork required to complete the regulatory process.
7. Invest in Low-Carbon Building Materials
While wood is a promising low-carbon building material, we'll also need glass, concrete, steel, aluminum, and computer chips with minimal embodied carbon emissions. Hyperscalers currently face significant challenges accessing low-carbon versions of these materials, which will eventually be produced using low-carbon hydrogen, carbon capture and storage, and low-carbon electricity. However, these systems require significant investment, workforce development, and permitting to be built. Without these advancements, the embodied emissions from data centers will increase rapidly and significantly in the US, Europe, and globally.
8. Increase Carbon Dioxide Removals
It's already clear that AI applications at data centers will generate emissions from electricity use and embodied carbon that cannot be avoided in the near term. Estimates of current greenhouse gas emissions exceed 300 million tons per year and are likely to grow this decade. These emissions should be measured using full life-cycle analysis and then offset through high-quality carbon removal projects, preferably those with high durability.
To effectively reduce the environmental impact of AI, all eight strategies discussed must prioritize the communities most affected: frontline communities near new infrastructure, consumers facing price increases, and tribal authorities with limited legal protections. Our own research on community opposition to AI data centers found that transparency, not cost or environmental impact alone, is the dominant driver of pushback across 46 stalled or blocked projects. We explore this concern further in our blog, Who Pays for the AI? The Hidden Costs of Rising Data Center Demand, including how ratepayers, not just data center operators, often absorb the cost of new grid infrastructure. Planning should begin by understanding the needs of these communities, ensuring that efforts focus on minimizing harm while maximizing benefits. Equity and justice must be embedded in every stage of planning, production, and permitting across all strategies.
AI's Power Demand Is Indicative of Broader Electricity Demand
AI is just one part of a broader trend of rapidly growing electricity demands, including from electric vehicles, heat pumps, industrial electrification, green hydrogen, and various e-fuels. The challenges AI presents to hyperscalers, communities, regulators, and investors serve as a preview of the complex, far-reaching impacts emerging in other sectors. The same questions keep recurring. Who secures reliable, affordable power fast enough? Who ends up carrying the cost and emissions burden of getting there the wrong way?
Managing AI's power demand will require building the technology architecture, clean firm power supply, and materials strategy to meet that demand deliberately, rather than reactively. AI's carbon footprint underscores the critical need for expertise in clean electricity, grid management, decarbonization, and carbon removal—expertise that will become increasingly vital as more companies realize the complexity and cost of the journey ahead.
Fortunately, AI itself can be part of the solution. With applications in grid management, material science, and advanced manufacturing, AI has the potential to play a powerful role in the climate response.
Read the full 2025 report: ICEF Sustainable Data Centers.
Frequently Asked Questions
How much electricity do AI data centers actually use?
AI-specific computation likely accounts for around 0.04% of global electricity use today, but data centers overall (most of it non-AI computation) used about 1.5% of global electricity in 2024. In the US, which hosts roughly half the world's data centers, Lawrence Berkeley National Laboratory puts current usage at 4% of US electricity, projected to reach 9.5-15.3% by 2030 as AI-specific demand grows.
Will more efficient AI models like DeepSeek reduce data center energy demand?
Not necessarily. DeepSeek's 2025 debut showed that competitive models can be trained with less powerful chips and fewer computing hours, but whether that translates into lower total energy demand is contested. Historically, efficiency gains in computing have tended to get absorbed by increased usage rather than reducing total consumption, so the honest answer is that it depends on whether demand growth outpaces the efficiency gained.
What is being done about the embodied emissions from building AI data centers?
Embodied emissions, from concrete, steel, and IT hardware, can account for one-third to two-thirds of a data center's lifetime emissions. Strategies include using lower-carbon materials like wood where feasible, developing low-carbon concrete, steel, and chips, and standardizing emissions disclosures for building materials so operators can compare and choose lower-footprint options.
Beyond Backup Generators: Hydrogen as Baseload Power for AI Infrastructure
Key Takeaways
- Speed to operation is the value proposition. While grid interconnection can take 3-5 years in constrained regions, hydrogen fuel cell systems can be deployed in a fraction of that time—a large advantage for operators racing to meet data center capacity demands.
- Hydrogen is moving beyond backup. Fuel cells could supply 6-15% of incremental data center power, functioning as primary or near-primary power rather than emergency standby.
- Higher fuel costs can be rational. When the alternative is a multi-year wait for grid power and the development loss that comes with it, paying a premium for hydrogen is better than falling behind.
The Grid Can’t Keep Up With Data Centers
The data center infrastructure buildout is moving at a pace the US power grid was never designed to accommodate. Cleanview tracks about 63 GW of operating US data center capacity and another 392 GW in planning, roughly six times what exists today. Developers in high-demand corridors—Northern Virginia, Central Texas, Phoenix—are finding that the grid can't deliver new capacity fast enough.
Interconnection queues now stretch 3-5 years in many regions, and that’s before accounting for permitting, transmission upgrades, and substation buildouts. For operators that need power online faster than the grid can deliver it, this timeline gap is a fundamental constraint on the business.
This mismatch between AI deployment, generator bottlenecks, and grid timelines is why hydrogen is entering the conversation as a viable power option for a growing subset of data center deployments, alongside natural gas with carbon capture, geothermal, and long-duration energy storage.
Hydrogen Fuel Cells: From Standby to Primary Power
For most of its history in data centers, hydrogen has been discussed as a cleaner replacement for diesel backup generators. That framing undersells the opportunity.
The shift happening now is more fundamental: hydrogen fuel cells are being evaluated as primary or near-primary power sources for behind-the-meter and facilities that can’t wait for grid connection. Notably, many modern fuel cell systems—including solid oxide fuel cells—can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy's 2024 deal with American Electric Power to provide up to 1 GW of fuel cells for data center power illustrates this approach: the systems will initially run on natural gas, with the capability to switch to 100% hydrogen in the future.
Furthermore, fuel cell systems are modular, can be deployed incrementally as load grows, and provide continuous power output. This is a promising path, and one that will scale only as fast as the fuel cell supply chain can keep up. Unlike solar or wind, fuel cells aren’t weather-dependent. Running on hydrogen, they produce zero direct emissions at the point of use. Running on natural gas, they still emit CO2, but their higher efficiency gives them a lower carbon intensity than a comparable gas turbine.
Goldman Sachs estimates that fuel cells could supply 6-15% of incremental data center power (the estimate doesn't specify fuel mix, though most near-term deployments would run primarily on natural gas). This is a meaningful share of new capacity, driven largely by operators who face years-long waits for both grid connections and new gas turbines. Bloom Energy, whose fuel cell products serve data center applications, has been a notable outlier in an otherwise struggling hydrogen sector, with its stock rising sharply on strong revenue performance and growing investor enthusiasm around data center power demand.
Speed to power depends on the fuel. Solid oxide fuel cells run on pipeline natural gas today, so operators do not wait for a hydrogen supply chain. Bloom states it can deliver onsite power for an entire data center in as little as 90 days, with the ability to add modules as load grows under certain circumstances. In all but a few select locations, hydrogen comes later when the same systems switch fuels as clean supply scales. Projects that need hydrogen from day one face additional challenges. Limited hydrogen availability and supporting infrastructure across much of the US can undermine the potential speed advantage of hydrogen-dependent projects. Nevertheless, locations with suitable hydrogen supply and supporting infrastructure may offer viable near-term opportunities.
The Hydrogen Premium: When Paying More Makes Sense
Hydrogen-generated power is more expensive than other forms of electricity generation in most markets. The logistics penalty (including compression, transport, and storage) can push hydrogen from $4/kg at the production site to $8-16/kg delivered, making the economics look unfavorable on a simple $/MWh comparison. In practical terms, hydrogen at $4-6/kg translates to roughly $120-180/MWh on an energy-content basis (LHV). At a fuel cell electrical efficiency of around 50%—typical for solid oxide systems—the effective cost of electricity rises to approximately $240-360/MWh for co-located production, compared to $40-60/MWh for natural gas fuel cells, $51-129/MWh for gas combined cycle, and $144-276/MWh for gas peakers. Operators can improve hydrogen economics by co-locating with production, avoiding the logistics penalty that can double or quadruple delivered costs.
While expensive, this cost comparison misses the central point. The relevant question is not whether hydrogen is cheaper than grid power, but whether it is better than having no access to power at all.
For an operator with signed contracts and a 100 MW facility sitting idle during a multi-year interconnection queue, the opportunity cost is substantial. At average US wholesale colocation rates (~$196/kW/month - a record high), a facility of that size represents roughly $235 million per year in potential revenue—meaning even a single year of delay can outweigh years of hydrogen fuel premiums.
The Inflation Reduction Act’s 45V Production Tax Credit further compresses the gap, offering up to $3/kg for clean hydrogen production—but projects must begin construction by December 31, 2027, to qualify. That deadline adds urgency to what’s already a time-sensitive calculus.
Reframing the Cost Debate for Speed-to-Power
The debate about whether hydrogen is cost-competitive with grid power misses the strategic challenge facing data center operators today: the fastest path to reliable, clean power. Hydrogen can play a consequential role in that timeline in some markets.
Assessing that requires modeling the full picture: grid interconnection timelines, hydrogen supply chain costs at a specific location, the 45V credit’s impact on project economics, and how hydrogen compares to batteries and other bridging technologies for a data center’s particular load profile.
Relae’s advisory team helps data center operators and technology companies evaluate these tradeoffs with rigorous, independent analysis. If speed to operation is a factor in your energy planning, let’s talk.
Frequently Asked Questions
How much faster is hydrogen fuel cell deployment than waiting for grid interconnection?
Grid interconnection in constrained regions can take 3-5 years once permitting, transmission upgrades, and substation buildouts are factored in. Fuel cell systems, especially those that start on natural gas and then transition to hydrogen, can be deployed in a fraction of that time. They are modular and can be installed and scaled incrementally as a facility’s load grows, though the pace depends on equipment and fuel supply.
If hydrogen costs more than grid power, why would an operator choose it?
For an operator with a 100 MW facility sitting idle during a multi-year interconnection queue, the lost revenue—roughly $235 million a year at average US wholesale colocation rates—can outweigh years of hydrogen’s fuel premium. That makes the higher cost a rational tradeoff against a multi-year wait for grid power, not just an expensive alternative to it.
Do hydrogen fuel cell systems have to run on pure hydrogen from day one?
No. Many modern fuel cell systems, including solid oxide fuel cells, can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy’s up to 1 GW agreement with American Electric Power follows this model: the systems start on natural gas, with the capability to switch to 100% hydrogen as the hydrogen supply chain matures.
From Capture-Ready to Capture-Committed: Decarbonizing Natural Gas with CCS
Key Takeaways
- Data centers are driving surging demand for new, firm electricity supply, accelerating natural gas-fired power generation.
- Carbon capture and storage (CCS) offers a practical way to balance long-term climate commitments with the need for new electricity generation in the near term.
- New natural gas-fired power plants must be capture-committed, not just capture-ready, potentially delivering power in 18 months and decarbonized power 18-24 months later.
- Capture-committed plants integrate planning and finance for the CO₂ capture, transport, and storage value chain from the start.
- Relae believes early investment in engineering, infrastructure, and community engagement is essential to meet capture commitments.
A New Era of Electricity Demand and Climate Pressure
The US and much of the developed world are experiencing profound growth in electricity demand. Two main forces are driving this trend: (1) the push to electrify existing uses, such as vehicles and heating, to improve energy security, enhance system efficiency, and reduce air pollution; and (2) the growth of energy-intensive sectors like manufacturing, telecommunications, and AI data centers.
Among these drivers, AI is creating unique demands that catalyze specific investments in electric power generation. Astonishing AI data center buildout, led by a handful of large technology firms (sometimes called “hyperscalers”) and their utility and construction partners, is accelerating energy consumption. These firms prioritize speed. When asked for their top five criteria for bringing new AI infrastructure online, one executive responded: “Speed, speed, speed, cost, and carbon emissions.”
Data centers require reliable, always-on power (referred to as “firm power”). This differs from other use cases, such as residential or commercial, which do not need the same amount of power across all hours. While hyperscalers and their partners are investing in renewables, nuclear, and geothermal energy at a remarkable pace, renewable resources alone do not yet meet the exploding demand for firm power.
Natural Gas Provides Firm Power but Drives Emissions Higher
The mismatch between data center power needs and variable renewable generation is fueling a boom in natural gas-fired power generation. The pipeline of new natural gas-fired power plants is enormous. Plants under construction in 2025 would, by themselves, add roughly 25 million tonnes of greenhouse gases each year to the air and oceans. The full suite of plants in planning is at least 10 times larger. Existing gas plants are also being used more and staying online longer.
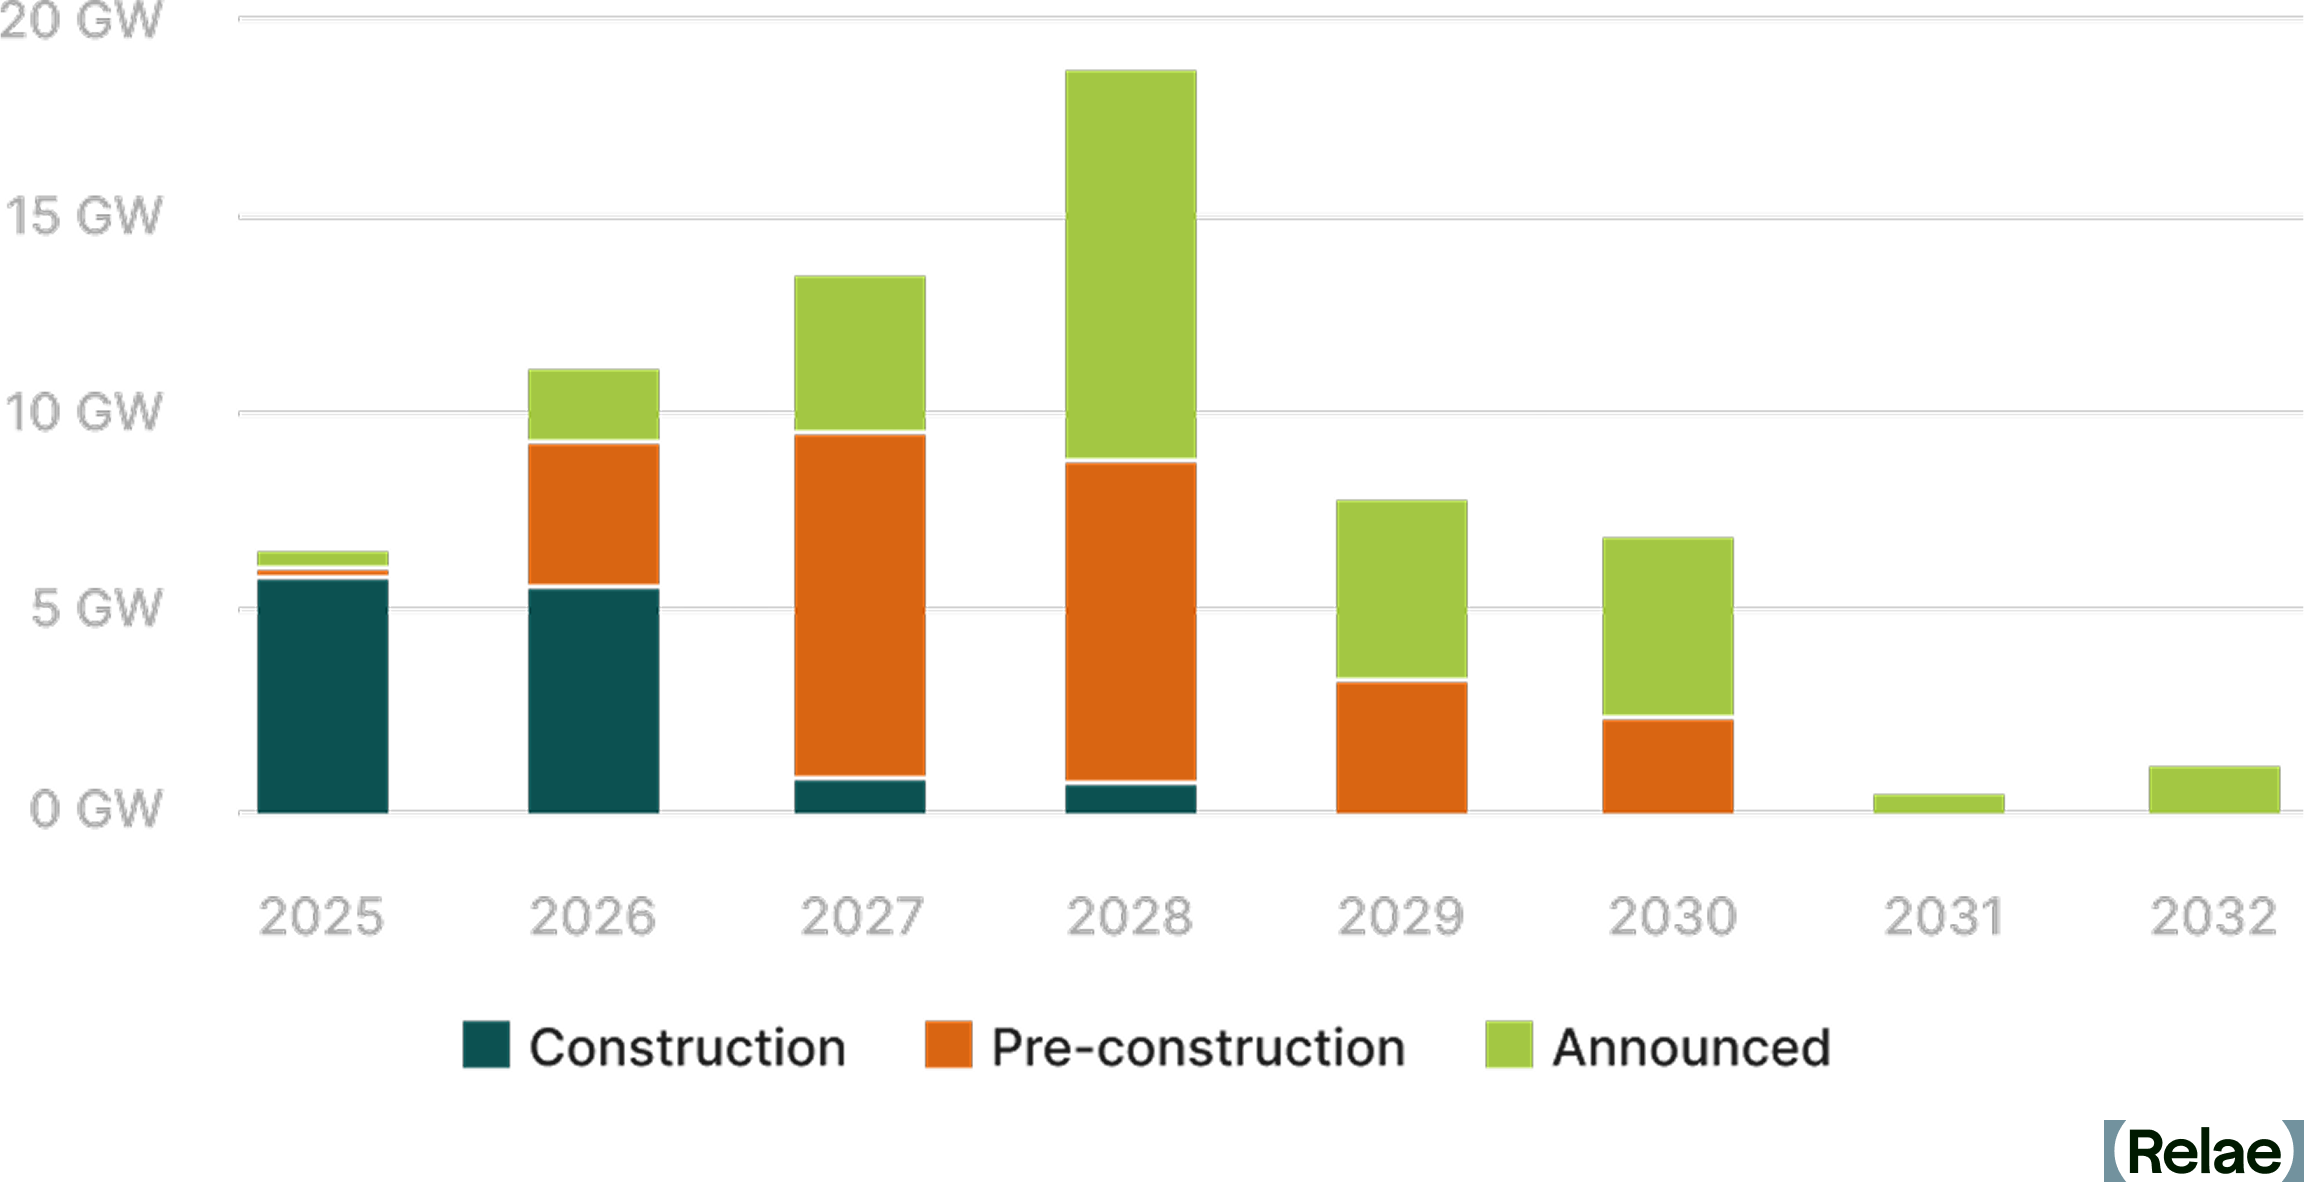
This rapid buildout is creating tension with corporate climate goals. Hyperscalers remain seriously committed to reducing emissions, but their ability to hit those targets is undermined by the need to procure new, large-scale electricity generation quickly.
Carbon Capture Aligns with Data Center Energy Demands
Carbon capture and storage is one way to bridge the gap. Data centers operate continuously and may have the ability to shift or curtail load. This demand profile suits the duty cycles of natural gas turbines and CCS facilities well. The potential to reduce direct emissions is profound: today’s CCS technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
This has led to a resurging interest in the concept of capture-ready gas power generation. New natural gas power plants can be built and brought online in 18 months. In a capture-ready plant, the developers integrate the necessary interfaces and reserve additional land, water, and energy to enable a carbon capture project to be built at a future date. In favorable locations, carbon capture can be added to a capture-ready plant in 18-24 months.
However, past experience shows that capture-ready plants rarely deliver. The ambition and commitment of the developers were contingent on policy and market signals that were either too small or never materialized. While the base plant may have made economic sense in terms of energy value for investment, it does not appear anyone was willing to pay the climate premium for CCS.
As David Hawkins of the Natural Resource Defense Council famously said, “If your plant is capture ready, my driveway is Ferrari ready.” To bring David’s humorous analogy back to the specifics here: don’t build a new driveway without at least a downpayment on the car.
How to Build Capture-Committed Power Plants for CCS
A better approach is building capture-committed plants, namely facilities that integrate CCS from the start. To be capture-committed, project developers must:
- Identify geologic storage for the many millions of metric tons of CO2 that these plants will produce each year over the next 20-30 years.
- Plan reliable CO₂ transportation from power generation to geologic storage by pipeline, rail, barge, or truck.
- Engage credible vendors of carbon capture technology that serve their needs and fit their goals.
- Fund front-end engineering design (FEED) studies.
- Arrange, or help to arrange, financing for the construction, commissioning, and operation of all necessary components in the CO₂ capture, transportation, and storage value chain.
- Ensure natural gas supply has near-zero fugitive methane emissions.
- Partner with local and frontline stakeholders to incorporate community impact into project planning, design, and financing.
Capture-committed plants send strong market signals. They help build the permitting pathways and develop the workforce, infrastructure, and community acceptance needed to avoid extra expense and delays. Done well, early commitments and investments will likely create repeatable models that reduce build times and costs.
A Path Toward Power That’s Clean Firm and Future-Ready
Eventually more carbon-free power in the form of renewables, nuclear, and geothermal energy will be deployed to serve national and international electric load growth for all types of electrification. Over time, these resources will likely displace natural gas. Until then, hundreds of millions of tons of CO₂ will be emitted each year unless commitments are made to take tangible action now.
Capture-committed natural gas-fired plants offer a pragmatic solution. With the right planning, financing, and community engagement, they can provide reliable power without locking in emissions, and they can deliver enormous benefits compared to uncontrolled operation. Federal and state governments can accelerate this transition by honoring and increasing CCS grants, supporting shared infrastructure, and streamlining permitting for CCS plants as they have for other clean energy supplies. These investments will enable the construction of cleaner, more resilient power infrastructure for the industries driving demand, from AI data centers to heavy industry.
[cta]
Frequently Asked Questions
What is the difference between a capture-ready and a capture-committed power plant?
A capture-ready plant creates an option to add carbon capture in the future, whereas a capture-committed plant treats capture as part of the project from day one. In a capture-ready plant, developers install the right interfaces and reserve extra land, water, and energy, but nothing obligates them to build the capture project, ever. A capture-committed developer secures options for CO₂ transportation and geologic storage, relationships with capture equipment vendors, funding for engineering studies, and financing across the full value chain before the base plant comes online.
Why have capture-ready plants historically failed to add carbon capture?
Nobody was willing to pay the climate premium. Capture-ready developers built plants that made economic sense on energy value alone, then waited for policy and market signals to justify carbon capture. Those signals were either too weak or never arrived, so the option went unexercised and no capture project was ever designed. The base plant runs uncontrolled for decades while the reserved land sits empty. David Hawkins of the Natural Resources Defense Council captured the problem well: "If your plant is capture ready, my driveway is Ferrari ready." Preserving an option costs very little. Exercising it costs a great deal, and capture-ready facilities rarely came with the funding to do so.
If renewables, nuclear, and geothermal will eventually displace gas, why invest in CCS for gas plants now?
Because greenhouse gas emissions happen in the meantime. Gas plants being built today will operate for 20 to 30 years, long before carbon-free resources scale enough to displace them. Left uncontrolled, they will emit hundreds of millions of tons of CO₂ over that span. Capture on those plants avoids most of it. Today's technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
What can federal and state governments do to accelerate capture-committed projects?
Three kinds of support matter most: funding, infrastructure, and permitting. Governments should honor and extend existing CCS incentives. Developers make capture commitments years before any revenue arrives, so uncertainty in government funding undermines the confidence these projects require. Governments should also support shared CO₂ transport and storage infrastructure. Common pipelines, rail terminals, and storage hubs make it easier for developers to secure physical CO2 offtake. Finally, permitting for CCS should be streamlined the way it has been for other clean energy supplies. Permitting delay is a leading cause of cost overruns, and a capture-committed plant should be able to pursue capture and storage with the same intensity and speed as electricity generation.
Scope 1 Emissions Explained: How to Track, Report, and Reduce Operational Carbon
Key Takeaways
- Scope 1 emissions are direct and controllable, making them a powerful starting point for decarbonization.
- Reducing scope 1 emissions can improve energy efficiency and lower operating costs.
- Reporting on scope 1 emissions is now required under new climate regulations, and companies that act now will gain an edge.
Why Scope 1 Emissions Matter Now
When we talk about corporate decarbonization, scope 2 and scope 3 emissions tend to take up the headlines, with a focus on renewable energy certificates (RECs) or challenges like complex supply chains. But scope 1 emissions, those produced directly from sources a company owns or controls, don’t get as much airtime. This is a missed opportunity.
As AI data center growth pushes companies towards on-site power, more organizations are confronting scope 1 boundaries for the first time. Scope 1 emissions enable companies to take immediate, tangible action to cut carbon, drive operational efficiencies, and get ahead of growing regulatory pressure.
What Are Scope 1 Emissions?
Scope 1 emissions are the direct greenhouse gas (GHG) emissions from sources that a company owns or controls. They mostly come from activities where fuels are combusted on-site within an organization’s operations. For industries that combust high amounts of fuels within their operations (e.g., oil and gas, chemicals, manufacturing), scope 1 can represent a significant share of the company’s emissions. For industries that outsource most of their production, scope 1 can be a smaller share of the overall footprint.
Scope 1 emissions typically fall into four categories:
- Stationary combustion: Emissions from burning fuels on-site for heating, manufacturing, or electricity generation. This includes boilers, furnaces, and turbines at company facilities.
- Mobile combustion: Emissions from company-owned or operated vehicles and equipment, such as cars, aircraft, delivery fleets, ships, or construction machinery.
- Fugitive emissions: Unintentional leaks or releases of gases, often from refrigeration and air conditioning systems. These can have an outsized impact because many refrigerants have global warming potentials (GWPs) hundreds or even thousands of times greater than carbon dioxide.
- Self-produced energy: Emissions from electricity, heat, or steam generated on-site, such as through natural gas-fired generators or cogeneration plants, even when the energy is used internally.
Identifying and categorizing scope 1 emissions correctly are the first steps toward uncovering potential operational improvements and carbon reduction approaches.
On-Site Power for AI Data Centers
As AI pushes data center operators toward on-site (“behind-the-meter”) power, a high-stakes accounting question follows: are those behind-the-meter emissions scope 1 or scope 2? The answer comes down to control, not location.
Under the GHG Protocol, emissions from on-site generation are scope 1 only when the reporting company owns or financially controls the generating asset (i.e., the self-produced energy category above). In most data center power deals, a third party owns and operates the generator and sells the electricity to the data center. In that structure, the company buying the power reports the emissions as scope 2, and the company generating the power reports the combustion as scope 1. Given the growth in emissions from the scale of AI infrastructure, getting the boundary right matters for corporate credibility.
Why Scope 1 Emissions Are a Strategic Priority
While scope 3 is often talked about as the largest source of emissions for corporations, that isn’t the case for all industries. For heavy sectors like oil and gas, chemicals, and manufacturing, scope 1 emissions aren't just significant - they are the bedrock of the emissions story. Other industries depend on these sectors' outputs to operate their own businesses, meaning that decarbonizing heavy industries’ scope 1 emissions can also drive reductions across other organizations’ scope 3 emissions.
Since scope 1 emissions are typically within a company’s direct operational control, they present a great starting point for decarbonization. Unlike scope 3 emissions, which require influencing suppliers, customers, or partners, companies can take immediate action on scope 1 sources. Even for industries with relatively small scope 1 footprints, reductions can often happen more quickly through internal decisions, such as equipment upgrades, process improvements, or fuel switching.
Regulatory momentum is also making scope 1 management increasingly urgent. Policies like the European Union’s Corporate Sustainability Reporting Directive (CSRD), California’s Climate Corporate Data Accountability Act (SB 253), and global ISSB-aligned frameworks are requiring companies to measure and publicly disclose their scope 1 emissions. Even within voluntary frameworks, reporting on scope 1 emissions is getting tighter. Within the Science-Based Targets Initiative (SBTi)’s new draft Net Zero Standard, scope 1 emissions must now have a separate target from scope 2 emissions, and the boundary must cover 100% of scope 1 emissions whereas previously the boundary was 95% of emissions. These market shifts highlight the importance of reducing scope 1 emissions.
Operationally, reducing scope 1 emissions offers business value. Many scope 1 reduction strategies, such as upgrading to more efficient equipment or reducing fuel waste can lower energy bills, improve asset performance, and reduce maintenance costs. For companies focused on both sustainability and profitability, targeting scope 1 emissions delivers a strong return on investment.
How to Calculate Scope 1 Emissions
To reduce scope 1 emissions, companies need to know exactly what and how much they are emitting. Calculating scope 1 emissions starts with gathering the right data at the facility level and understanding the activities that generate emissions.
What to Measure
Scope 1 emissions come from activities such as fuel combustion in boilers or vehicle fleets, refrigerant leaks from cooling systems, and on-site energy generation. Ideally, companies should collect activity data, like gallons of diesel used, cubic meters of natural gas consumed, or kilograms of refrigerant leaked and replaced. In cases where direct measurement isn’t possible, companies often rely on estimations, using financial spend data or industry intensity metrics as a proxy for fuel consumption.
Where to Find the Data
Facility-level data is the backbone of comprehensive and comparable scope 1 accounting. Much of the required data can be sourced from utility bills, fuel receipts, maintenance logs for HVAC and refrigeration systems, and reports from on-site equipment operators. Increasingly, companies are deploying sensors to capture real-time data on fuel consumption, refrigerant leaks, and on-site energy generation, improving both accuracy and responsiveness.
How to Calculate the Emissions
Emissions are calculated by applying the emissions factors (i.e., the amount of greenhouse gases emitted per the quantity of fuel or refrigerant) to the collected activity data. Many companies use carbon accounting software to automate calculations, track emissions over time, and ensure consistency with recognized standards like the GHG Protocol. Expert support is often critical, especially for sectors with complex operations. Carbon accounting experts help ensure the data is complete, auditable, and aligned with evolving regulatory requirements.
Accurate scope 1 data builds a strong foundation for compliance as well as for setting credible reduction targets and tracking long-term performance.
How to Reduce Scope 1 Emissions
With scope 1 emissions data in hand, companies can begin identifying and implementing reduction strategies. Because these emissions are within the organization’s operational control, companies often have multiple levers they can pull.
Operational Strategies
- Fuel switching: Replacing fossil fuels like natural gas or diesel with lower-carbon alternatives, like green hydrogen or renewable electricity, can significantly reduce direct emissions from stationary and mobile combustion. Depending on the switch, this could result in higher scope 2 emissions, but these can be more readily addressed through market-based instruments, thus lowering the overall footprint.
- Equipment upgrades: Modernizing boilers, generators, fleets, and other combustion-based equipment can improve energy efficiency and cut emissions. Newer technologies often perform better and emit less.
- Process innovation: In emissions-intensive industries like cement and steel production, rethinking industrial processes can yield dramatic reductions. Low-carbon production methods are increasingly becoming commercially viable.
- Leak detection and repair: Methane leaks from oil and gas operations and refrigerant leaks from cooling systems are major contributors to scope 1 emissions. Deploying monitoring technologies and maintaining rapid-response repair programs can fix leaks before they lead to large amounts of emissions.
Strategic Procurement
- Vendor selection: Companies can prioritize suppliers that offer lower-emissions alternatives for fuels, materials, and services.
- Fleet electrification: Procuring electric vehicles for delivery, service, and logistics fleets reduces both emissions and long-term fuel and maintenance costs.
- Equipment design: Working with suppliers to source modular, emissions-efficient machinery can reduce on-site fuel use and improve flexibility over time.
Driving Innovation Through R&D
- Low-carbon products: Research and development teams can design products and processes that inherently require less energy, or lower-carbon energy, to produce, lowering scope 1 emissions at the source.
- Material innovation: Developing new chemistries or alternative materials can avoid high-emission production methods, contributing to broader decarbonization goals.
- Closed-loop systems: Designing circular, waste-reducing systems can minimize both raw material use and the on-site emissions associated with production and disposal.
Reducing scope 1 emissions often requires up-front investment, whether it’s upgrading equipment, switching to alternative fuels, or embedding low-carbon principles into procurement and R&D strategies. While the initial costs can be substantial, they deliver long-term value through improved operational efficiency, reduced regulatory risk, lower energy expenses, and enhanced brand value in a marketplace that increasingly rewards climate leadership.
Frequently Asked Questions
What are the main categories of scope 1 emissions?
Scope 1 emissions fall into four categories: stationary combustion (fuels burned on-site in boilers, furnaces, or turbines), mobile combustion (company-owned or -operated vehicles and equipment), fugitive emissions (leaks of refrigerants or methane, which often carry outsized global warming potential), and self-produced energy (electricity, heat, or steam generated by equipment the company owns or controls).
Which regulations require companies to report scope 1 emissions, and when do they take effect?
The EU’s Corporate Sustainability Reporting Directive (CSRD) already requires scope 1 disclosure for companies in its first reporting waves. In the US, California’s SB 253 requires companies with over $1 billion in annual revenue doing business in California to report scope 1 and scope 2 emissions, with first reports due November 10, 2026. ISSB-aligned disclosure rules are extending similar requirements across other jurisdictions.
What’s the fastest way for a company to start reducing scope 1 emissions?
Start by measuring at the facility level, since this activity data shows where emissions concentrate. From there, the quickest wins are usually operational, such as repairing refrigerant and methane leaks, upgrading inefficient combustion equipment, and electrifying vehicle fleets, because they sit within the company’s direct control and often pay back through lower fuel and maintenance costs.
Is behind-the-meter power scope 1 or scope 2?
It depends on who controls the generating asset. If a company owns or financially controls its on-site generation, the emissions are scope 1. If a third party owns and operates the generator and sells the power- the structure behind most data center power deals- the buyer reports those emissions as scope 2 under the GHG Protocol’s Scope 2 Guidance.



