Navigating Scope 2 Accounting Changes
Key Takeaways
- Voice your opinion: The Greenhouse Gas (GHG) Protocol is updating its scope 2 guidance with final standards expected in 2027, which may require hourly and regional matching of renewable energy certificates (RECs), potentially changing how companies claim their electricity-related emission reductions.
- Act now to secure renewable energy contracts: Companies should move forward with their scope 2 climate commitments today. The GHG Protocol is expected to grandfather in contracts entered into under existing rules.
- Beyond the megawatt hour (MWh): High-impact forward REC contracts measure impact beyond the current annual MWh match requirement, maximizing near-term carbon abatement and social impact for every dollar invested.
Why 2027 Rule Changes Matter for 2030 Targets
Companies racing to meet 2030 climate targets face converging pressures: surging electricity demand, constrained renewable energy supply, and scope 2 accounting rules that could undergo significant changes by 2027.
In a recent webinar, power market experts from Relae (formerly Carbon Direct) and Ever.green explored these changes. Patti Smith, former Electricity Decarbonization Lead at Relae; Julia Millot, Senior Power Decarbonization Manager at Relae; and Liz Pearce, Chief Revenue Officer at Ever.green, unpacked what's changing and how companies can respond.
The stakes are high. Based on GHG Protocol Scope 2 Public Consultation materials, companies may need to match RECs to electricity consumption on an hourly and locational basis as early as 2028. However, we expect the GHG Protocol to grandfather forward REC contracts signed before new rules take effect, enabling companies to continue advancing toward 2030 targets amid rule uncertainty.
Big Changes to the Power Grid
The US power grid is entering sustained demand growth for the first time in decades. "Over the next five years, data centers alone are going to put [the equivalent] of four New York Cities onto the grid," Smith explains, citing forecasts that project around 200 terawatt hours of new data center load through 2030 (i.e. cumulative energy consumption). That demand growth also shows up in near-term grid planning. NERC's January 2026 Long-Term Reliability Assessment forecasts North American summer peak demand rising by 224 gigawatts—a 24% increase—over the next decade, with new data centers cited as the primary driver. These figures highlight that peak capacity and total energy consumption are directly impacted by the data center boom.
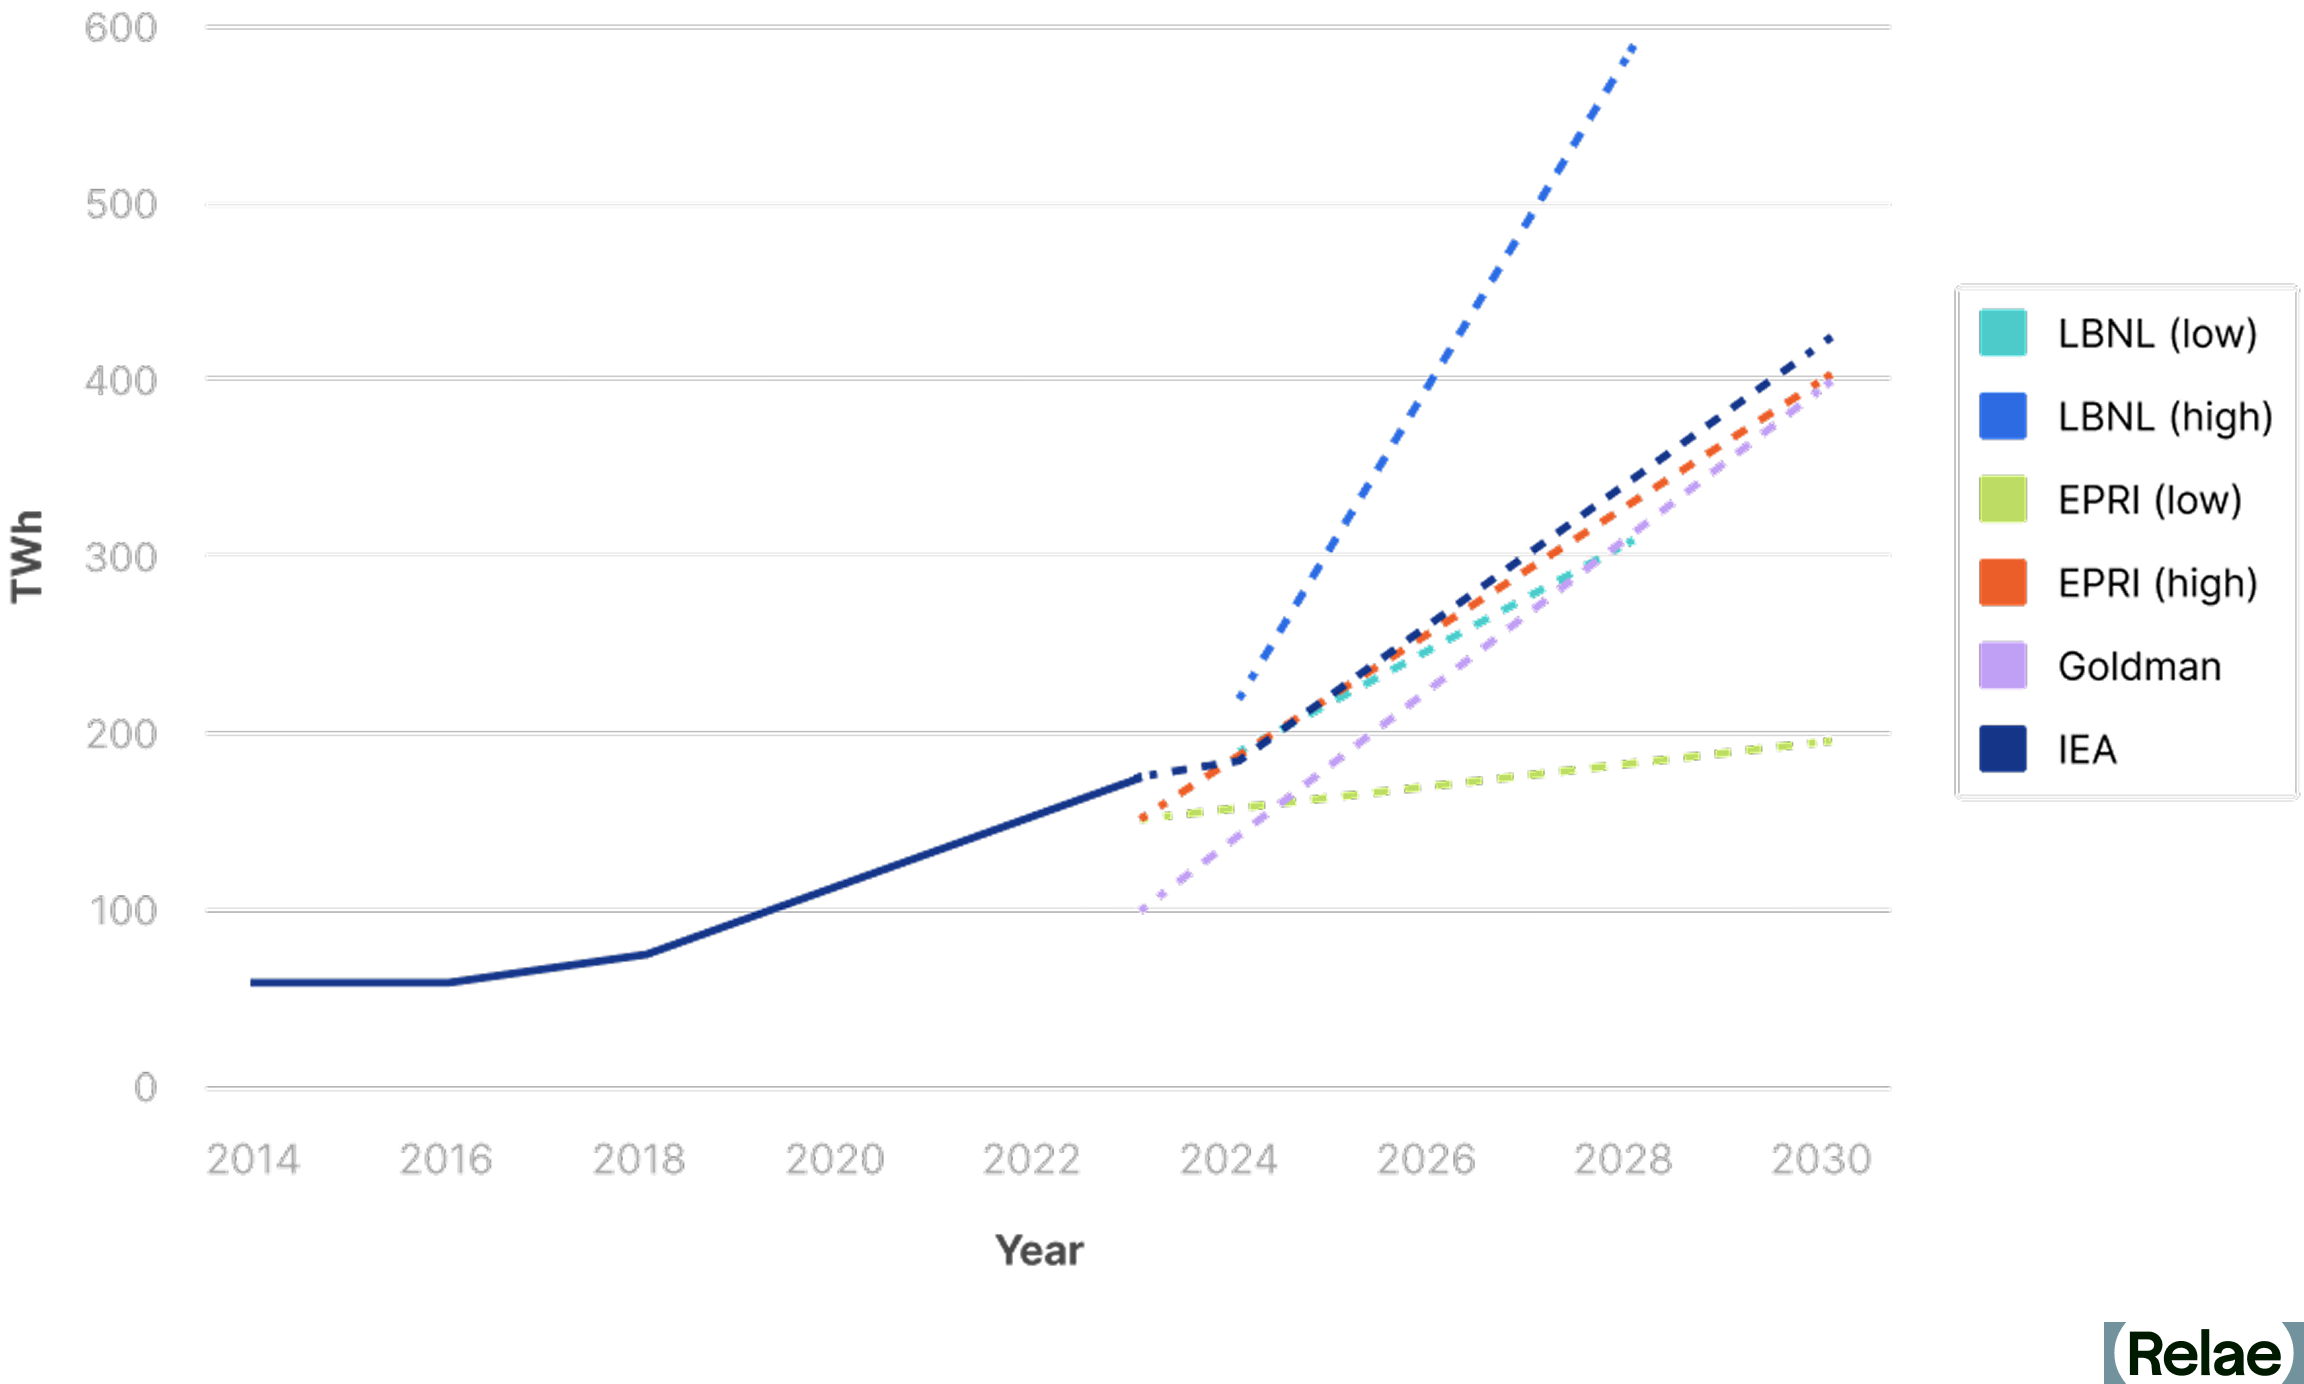
Meanwhile, new renewable projects face headwinds. Smith points to interconnection queue delays: "Solar and battery projects are taking three to five years from initial request to operation." At the same time, clean energy tax credits, which were driving wind and solar expansion, have been curtailed. New restrictions on foreign supply chain materials, which are critical to renewable project development, are further hampering the development of new clean electricity projects.
The result: Power demand is rising while new renewable electricity supply is getting throttled.
The Messy Reality of Electricity Emissions Accounting
Quantifying the emissions from an individual power plant is straightforward. Allocating those emissions to the companies that consume power is far more complicated.
Grid-supplied electricity comes from many generators that shift constantly, sometimes even second to second. Companies can’t directly measure emissions from a grid-connected load because the generators serving it continuously change.
Without direct measurement, companies need rules to estimate the emissions they are responsible for. The GHG Protocol’s Scope 2 Guidance provides that framework, establishing how companies estimate electricity-related emissions and how to reduce them through renewable energy purchases.
How Companies Currently Claim Renewable Energy
For the past decade, companies have used renewable energy purchases to achieve their scope 2 emission reduction goals. The most widely used mechanism is the REC, each representing clean energy attributes for one MWh of renewable electricity generated and added to the grid. Currently, when a company buys RECs equal to its annual electricity consumption, it can claim 100% renewable electricity. Under current rules, companies can use purchased renewable energy from anywhere in North America and apply it to any load in North America at any time during the year.
Importantly, emissions from different power grids vary widely across North America depending on time of day, time of year, and the power grid makeup.
This flexibility allows companies to match a REC from a clean grid against electricity consumption from a dirtier one, creating a potential mismatch between emissions claimed and actual emissions avoided. This gap has drawn scrutiny, contributing to the motivations for the scope 2 rules rewrite.
What's Changing in GHG Protocol Scope 2 Accounting?
On October 19, 2025, after years of consultation, the GHG Protocol released two separate proposals for public consultation:
1. Scope 2 changes: Moving away from annual REC matching to an ‘hourly and regional’ REC matching requirement.
2. New consequential methodology: A new approach to estimating emissions caused by a company’s consumption and avoided by its renewable energy contracts.
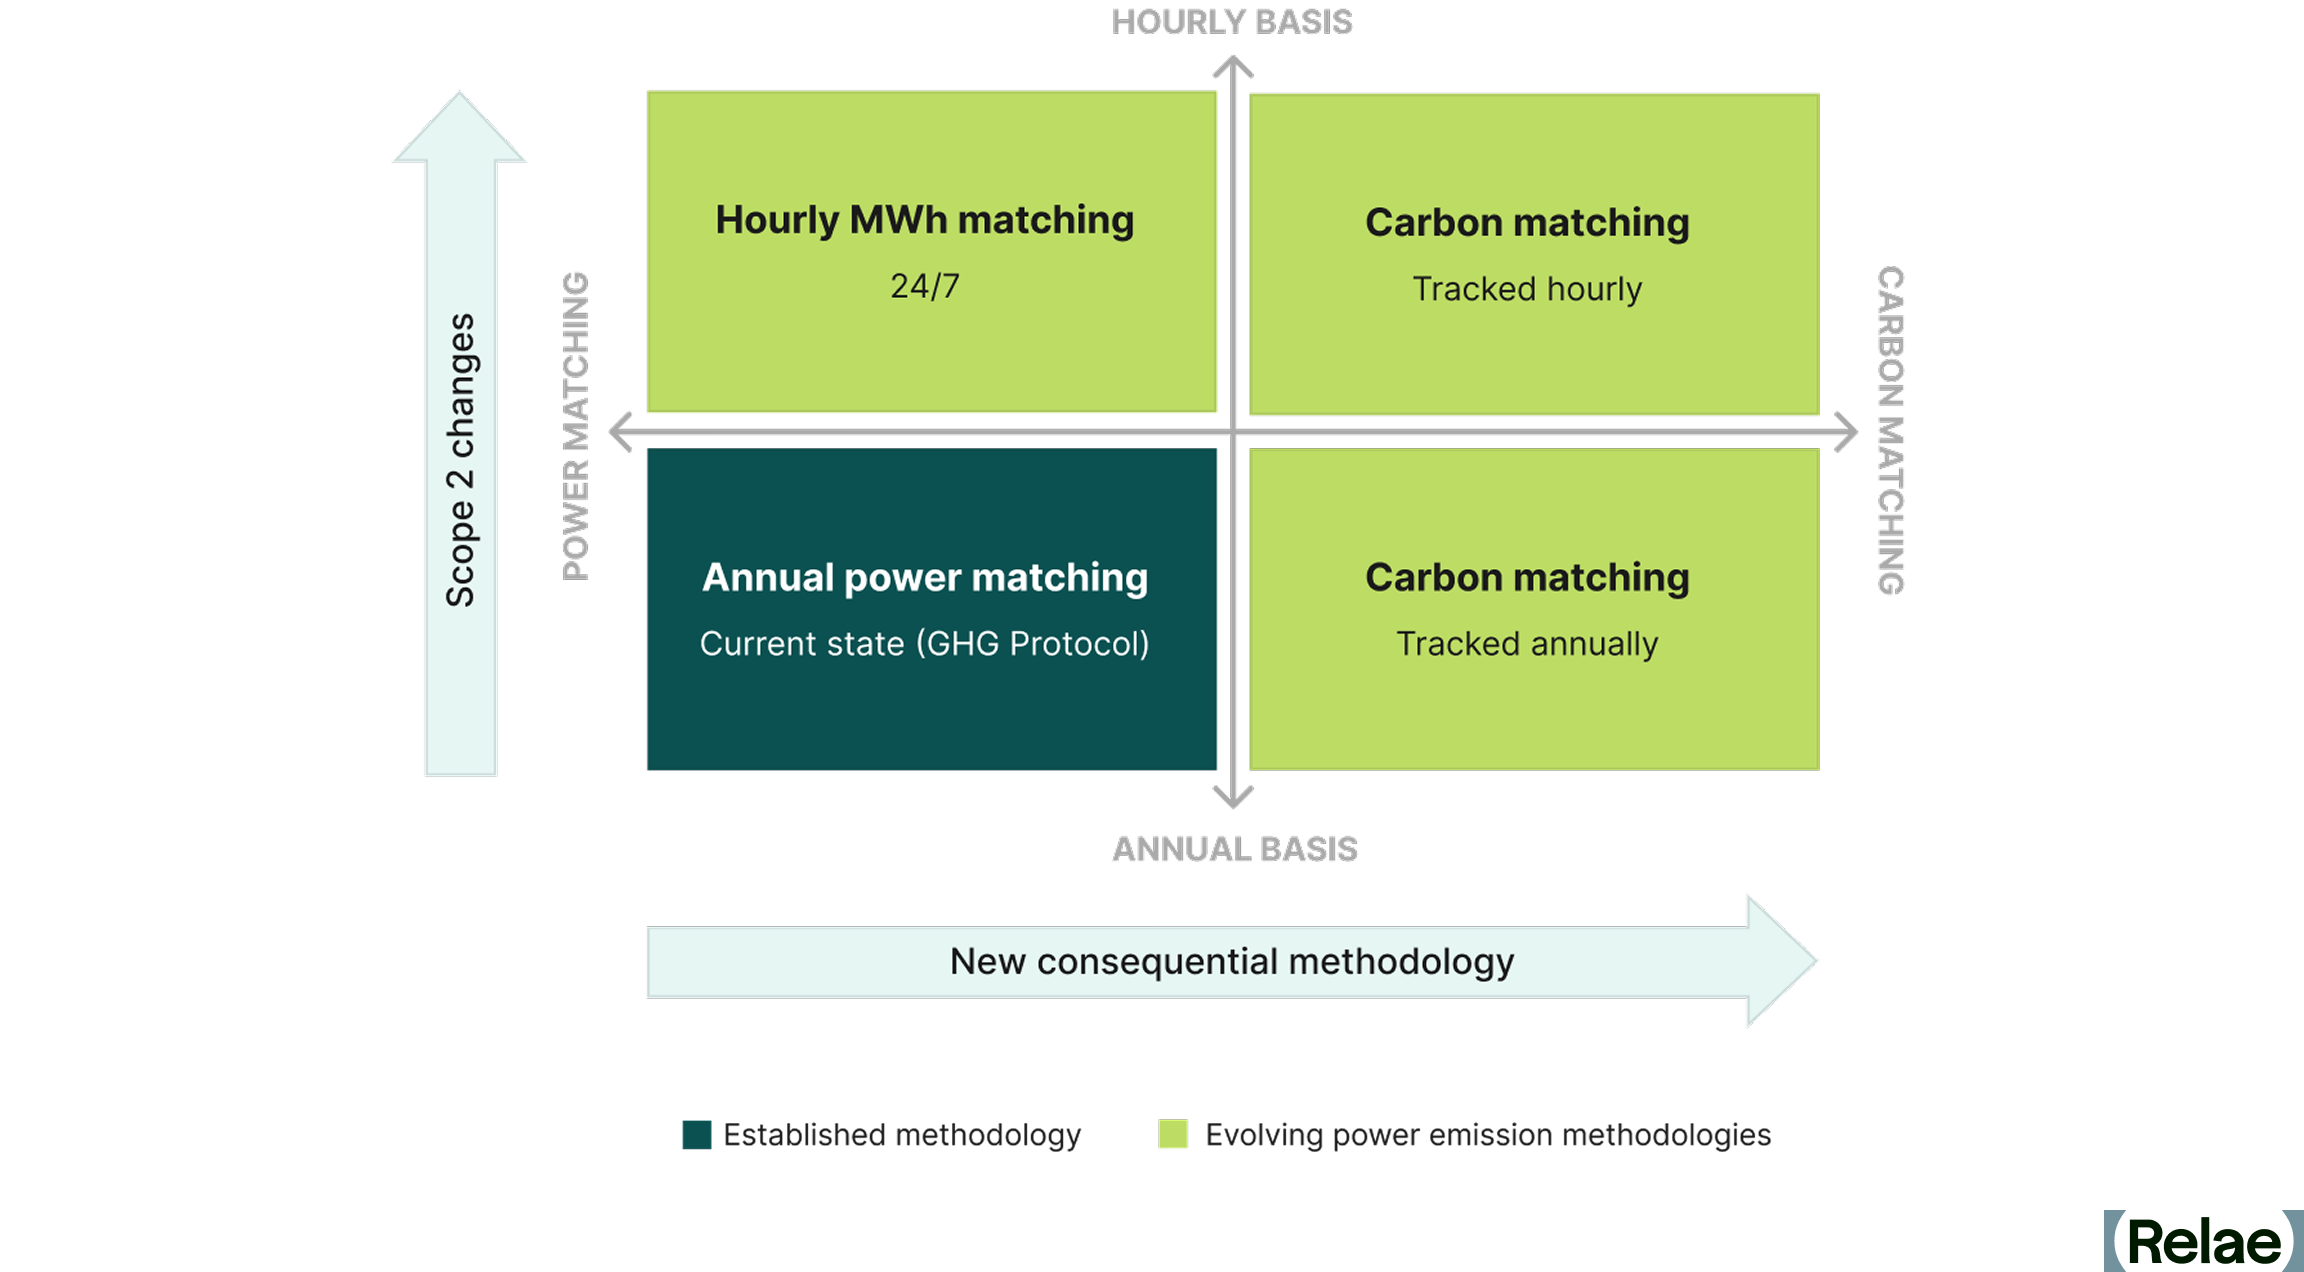
The hourly matching proposal (24/7): Companies would match RECs to consumption hour by hour within the same grid region, rather than annually across any North American grid.
"A REC generated on a Texas wind farm would not be able to be used for electricity consumed in New York," Millot explains.
The consequential approach: This proposes a carbon matching methodology, which estimates emissions caused by a load and estimates the emissions a renewable project displaces.
"Projects in the Carolinas are avoiding 0.6 or 0.7 tons of CO2 per megawatt hour, whereas a California project is probably closer to 0.2 or 0.3," Smith explains.
Projects in the Carolinas deliver more than double the climate impact per REC under the consequential rules. In this methodology, the load and generator do not need to be located in the same region.
While the proposed rules and new methodologies work through the public consultation process, it will be important for companies to start to anticipate the potential impacts on their climate goals and strategies.
Timeline for Scope 2 Accounting Changes
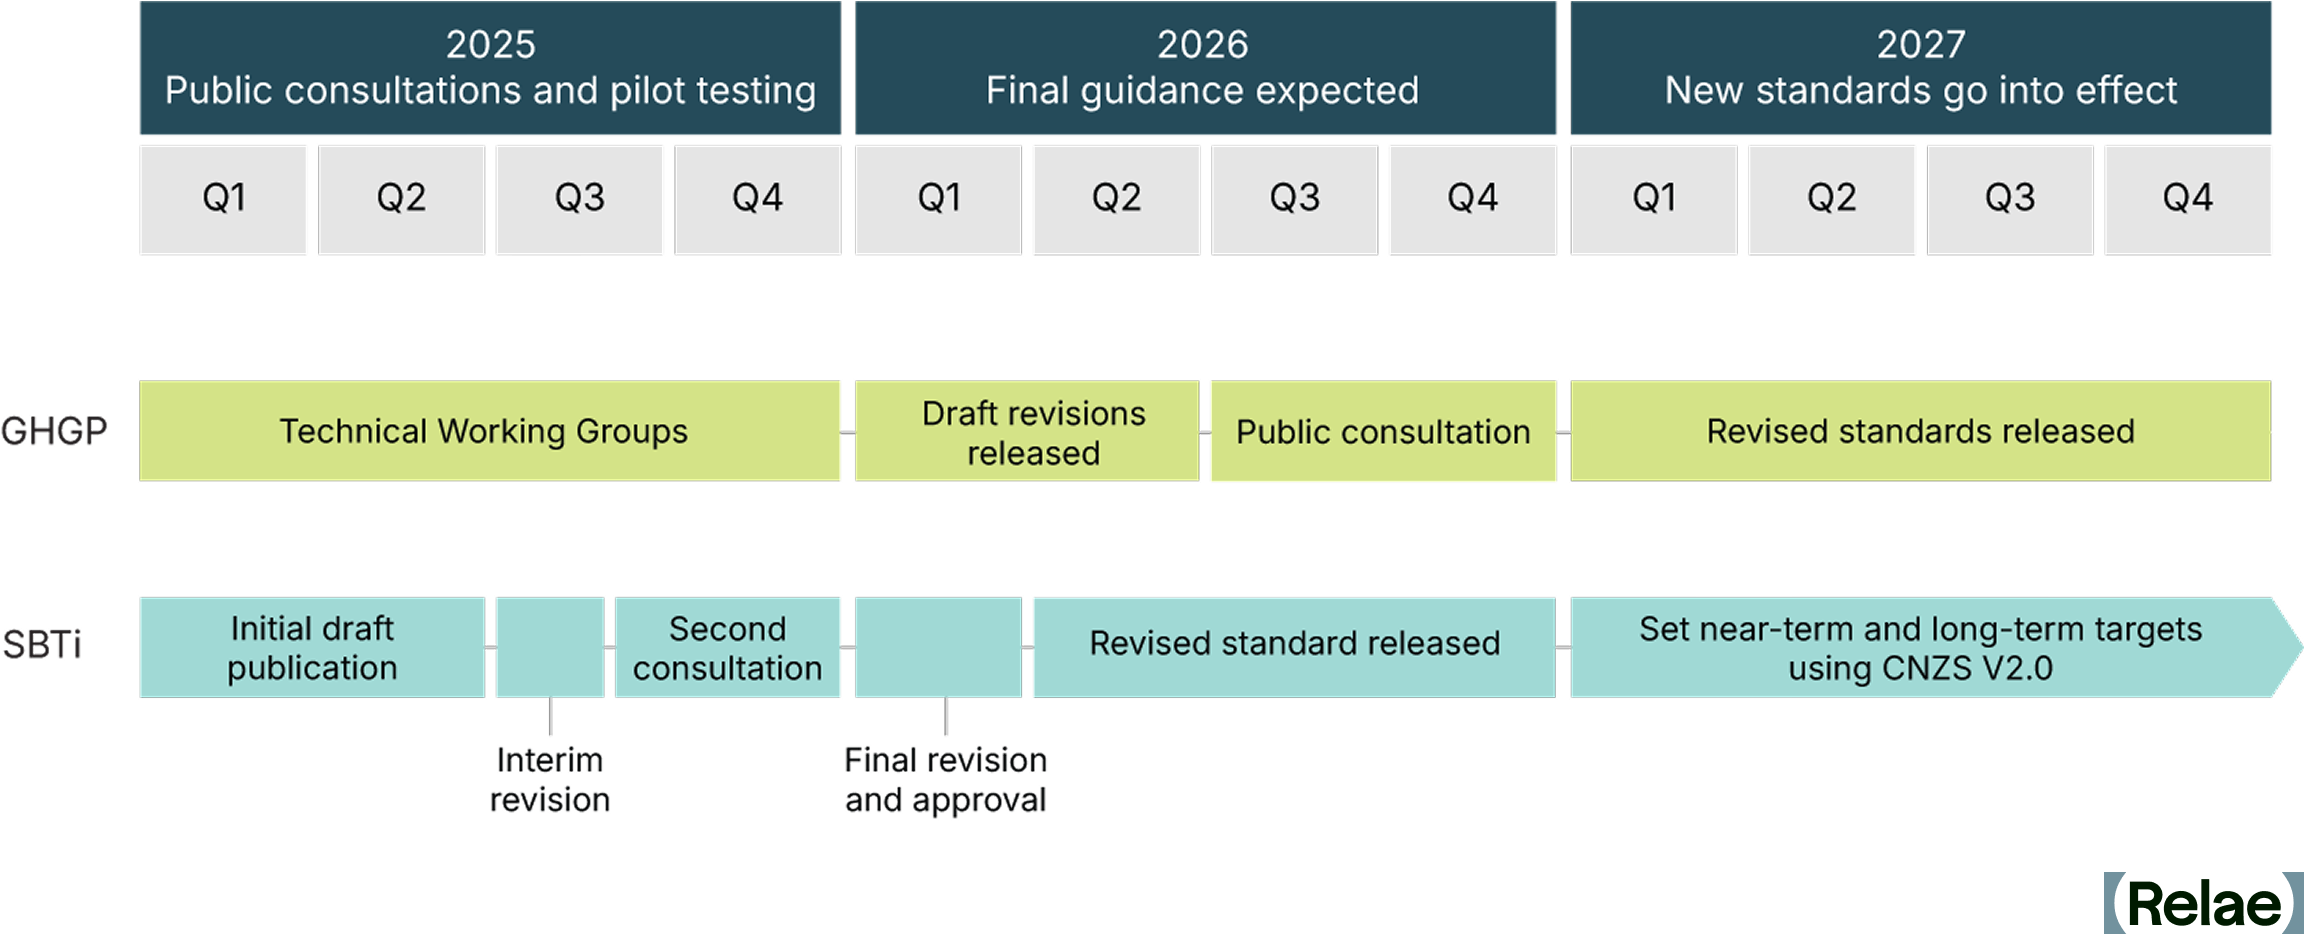
Both the Scope 2 and Consequential Electricity-Sector Emissions consultations closed January 31, 2026, after GHG Protocol extended the original deadline. The GHG Protocol is analyzing feedback with a second consultation and final standards expected by 2027, though the exact timeline is still being finalized.
Companies are encouraged to participate in the public consultation. The GHG Protocol is asking for comments on critical questions, such as:
- Should proposed rules apply to energy consumers of all sizes?
- Which geographical boundaries should be used for locational matching?
- Should existing contracts be grandfathered in?
The public consultation period is an opportunity to shape the standards that will govern electricity-related emission accounting for years to come.
Why Act Now Instead of Waiting
With final rules still in development, companies with scope 2 emission reduction goals or science-based targets face a decision: Wait for clarity or act now.
Several factors favor early action:
- Inclusion of legacy contracts. "There are a lot of indications from the committees that existing long-term contracts will be grandfathered in," Pearce notes. The draft considers a legacy clause that would allow organizations to apply pre-existing contractual agreements, even if they don’t comply with new rules.
- Throttled renewable project development. Interconnection delays for new renewable energy projects, elimination of clean energy tax credits by 2028, and limitations on foreign materials needed to develop renewable energy project components mean that new REC supply may be harder to access in future years.
- Renewable project development timelines. "There's generally a lag, sometimes six to 18 months" between contract signing and project operation, Pearce explains. That means even if you sign today, the RECs won’t be generated for up to 18 months from the signing date.
- High-impact opportunity. Through careful project selection, renewable energy investment can go beyond the annual energy match requirement and incorporate additional impactful metrics, such as higher avoided emissions and positive social impacts.
Renewable Energy Buying Options for Companies
Previously, companies have been able to buy renewable energy through the following three paths; however, they all come with their own tradeoffs.
Traditional REC Buying Options
- REC spot markets make up most corporate renewable procurement. However, they mainly come from existing projects rather than financing new development, which is critical to expanding renewable energy supply to meet rising decarbonization needs.
- Virtual power purchase agreements (VPPAs) are highly impactful but require large power loads and the ability to manage long-term financial risks. Unavailable to most companies.
- Utility green tariffs have limited availability throughout the US (depending on the utility(s) that serve your load) and vary in quality.
Alternative REC Procurement Approach
For companies that want to go beyond the REC spot market and are not large enough to pursue a VPPA, there’s an alternative procurement option available: a high-impact forward REC contract. These multi-year contracts commit to purchasing RECs from specific new projects before they're built, providing the upfront revenue certainty developers need to secure financing at a fraction of the scale and complexity of a VPPA.
Comparing Renewable Energy Procurement Options
The Path Forward
Despite rapidly increasing grid demand, renewable project headwinds, and changing accounting rules, companies can still meet 2030 scope 2 goals.
What companies should do now:
- Watch for the next round of GHG Protocol consultation on Scope 2 revisions
- Evaluate forward REC contracts to lock in terms before rule changes
- Prioritize high-impact RECs that deliver measurable climate and social benefits
GHG Accounting
Relae helps companies, investors, and project developers quantify and interpret emissions across operations, value chains, products, projects, and portfolios. We combine advanced emissions analytics, life cycle assessment, and sector-specific expertise to help you identify emissions hotspots, evaluate high-impact opportunities, and build credible baselines for reporting and investment decisions.
Ready to Navigate What Comes Next?


Rhianna Hixon
Rhianna Hixon

Rhianna Hixon brings over eight years of content strategy expertise to Relae, where she leads the company's content program, translating Relae's scientific expertise into resources that equip decision-makers to act with confidence.
At Relae, Rhianna has built and scaled a content program spanning power and energy, environmental markets, natural capital, and climate strategy. She partners with subject matter experts across the organization to turn rigorous science into compelling narratives that rank, resonate, and drive action.
Before joining Relae, Rhianna spent five years at a B2B digital marketing agency, where she pioneered the content marketing department and developed full-funnel SEO and content strategies for 35+ B2B companies. She holds a B.A. in Environmental Studies and Communications from UC Santa Barbara, a foundation that shapes both her subject matter depth and her approach to climate storytelling.
Academic Achievement Award, University of California, Santa Barbara
Dean's Honors, University of California, Santa Barbara
Scope 3.1 Emissions: How to Measure and Reduce Value Chain Impact
What to Read Next
Scope 2 Emissions Explained: Tracking, Reporting, and Reducing Impact
Key Takeaways
- Scope 2 emissions (indirect emissions from energy use) are increasingly critical to address. With surging electricity demand, especially from data centers, scope 2 is a growing share of corporate emissions and a priority for decarbonization.
- Approaches to scope 2 accounting are evolving—and formal changes are now on the table. Both location-based and market-based methods remain accepted under the Greenhouse Gas Protocol. Still, the Protocol's recently closed public consultation proposes more granular approaches, including 24/7 power and carbon matching, that would better reflect the realities of modern power markets.
- Proven decarbonization levers, such as reducing energy use, entering power purchase agreements, procuring green tariffs, and buying high-quality renewable energy certificates, are already available and impactful. Decarbonization, not just measurement, must be the goal. Companies don’t need to wait to decarbonize.
Accounting for Indirect Emissions From Energy Use
As businesses and organizations strive to reduce their environmental impact, carbon accounting has become an essential tool for tracking and managing greenhouse gas (GHG) emissions. Carbon accounting helps organizations measure, report, and mitigate their emissions across various activities. A key framework for categorizing these emissions is the Greenhouse Gas Protocol (GHG Protocol), which classifies emissions into three scopes:
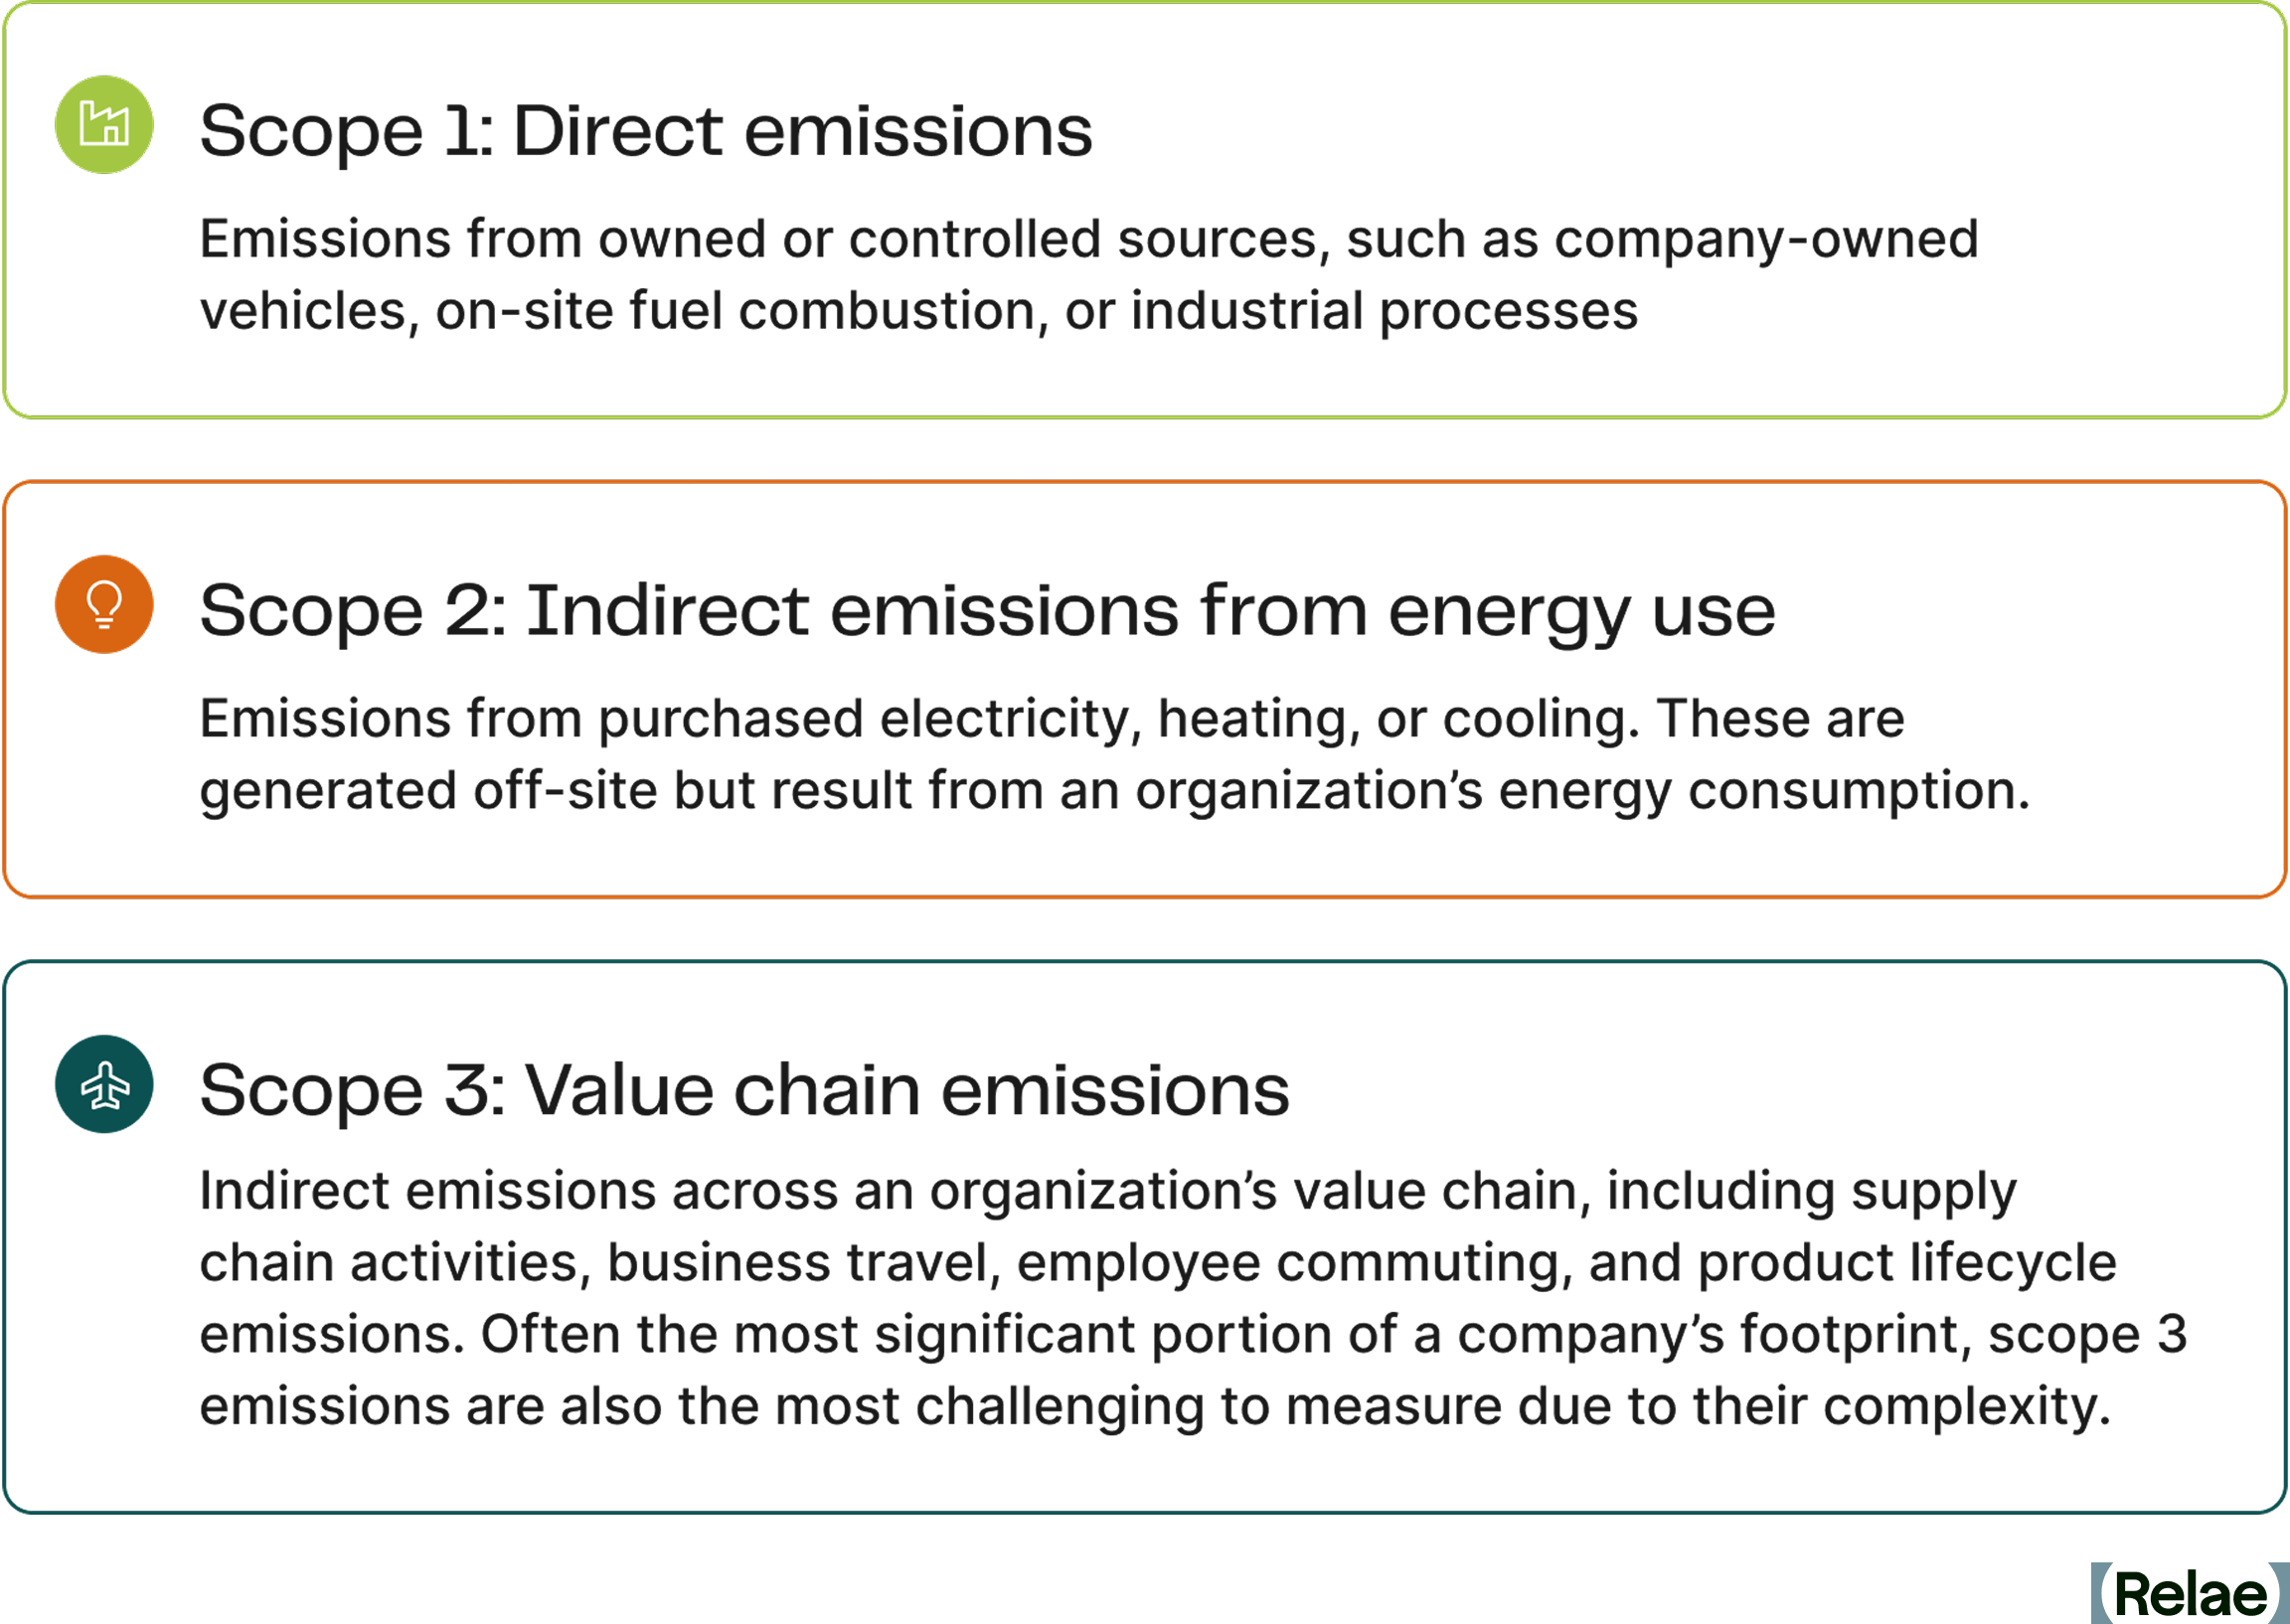
Each scope presents unique challenges and opportunities for reduction. Among them, scope 2 emissions are particularly significant because they stem from purchased energy, which is often generated using fossil fuels. However, numerous reduction mechanisms exist today to help organizations eliminate these emissions, such as improving energy efficiency in order to use less energy, and transitioning to renewable energy sources through market-based mechanisms. Understanding scope 2 emissions is crucial for businesses looking to contribute meaningfully to the global energy transition and achieve sustainability goals.
What Are Scope 2 Emissions?
Scope 2 emissions refer to indirect GHG emissions associated with the consumption of purchased energy. Unlike scope 1 emissions, which result from direct fuel combustion, scope 2 emissions arise from the generation of electricity, steam, heat, or cooling that a company procures from external sources.
The primary sources of scope 2 emissions include:
Purchased electricity: When businesses buy electricity from a utility provider, the emissions from power plants that generate this electricity are classified under scope 2.
Purchased heat, steam, and cooling: Some companies purchase heat, steam, or cooling services instead of generating them on-site. These services often come from centralized facilities that may rely on fossil fuels, thereby contributing to scope 2 emissions.
What sets scope 2 emissions apart from other scopes is the presence of market-based mechanisms that offer multiple pathways for organizations to reduce their carbon footprint. Unlike scope 1, where emissions reductions often require technological shifts or operational changes, scope 2 reductions can be achieved through strategic procurement decisions. The transition to renewable energy sources is an essential component of sustainability strategies, setting the stage for a broader energy transition across industries and economies.
How Are Scope 2 Emissions Measured Today?
The GHG Protocol currently outlines two primary approaches for calculating scope 2 emissions: the location-based method and the market-based method.
Location-Based Method
The location-based method calculates emissions for electricity consumption based on the average emissions intensity of the grid where the energy consumption occurs. This approach is mandatory under various reporting frameworks and does not take into account a company’s procurement choices.
- Relies on grid averages: Emissions are calculated based on regional grid emissions factors rather than specific energy purchases.
- Time-delayed data: Since grid emissions factors are typically updated annually, this method may not reflect real-time energy sourcing changes.
- Limited control: Companies using this method have less direct influence over their reported emissions, as they depend on the overall energy mix of their region.
Market-Based Method
The market-based method, on the other hand, reflects an organization’s actual procurement decisions and energy-sourcing strategies. It accounts for specific contracts, such as power purchase agreements (PPAs), renewable energy credits (RECs), and green tariffs, which allow businesses to claim lower emissions from their purchased electricity.
- Reflects company choices: Emissions calculations take into account contractual agreements for renewable energy purchases.
- Mechanism for electricity transition: Encourages organizations to invest in low-carbon electricity options and actively support the transition to renewables.
- Multiple reduction options: Companies can reduce their scope 2 emissions through a portfolio of mechanisms like PPAs, RECs, and green tariffs, making this method a flexible and strategic tool for decarbonization.
While market-based mechanisms provide flexibility in reducing scope 2 emissions, they also highlight the need for more precise and updated carbon accounting methodologies. For example, some decarbonization strategies, such as time-shifting energy consumption to better match renewable generation, are not accounted for under these methods. This and other limitations mean that the traditional methods outlined in the GHG Protocol are increasingly seen as outdated in an era of rapid changes in energy generation and grid dynamics. As a result, the market is shifting toward more advanced power emission accounting methodologies that provide a more accurate reflection of emissions associated with electricity use.
Proposed Changes to the GHG Protocol Scope 2 Guidance
The current GHG Protocol Scope 2 Guidance provides a market-based instrument methodology, originally designed in the early 2000s, that allows US-based companies to procure renewable energy at any point within a year from anywhere in North America and apply it to any of its annual electricity consumption within that same year. This methodology, as written, allows for a potentially significant mismatch of “emissions caused” (by consuming electricity) versus “emissions avoided” (by generating renewable electricity) in that it does not account for any of the realities of electric grids and generators, which vary significantly over different regions, seasons, and time of day.
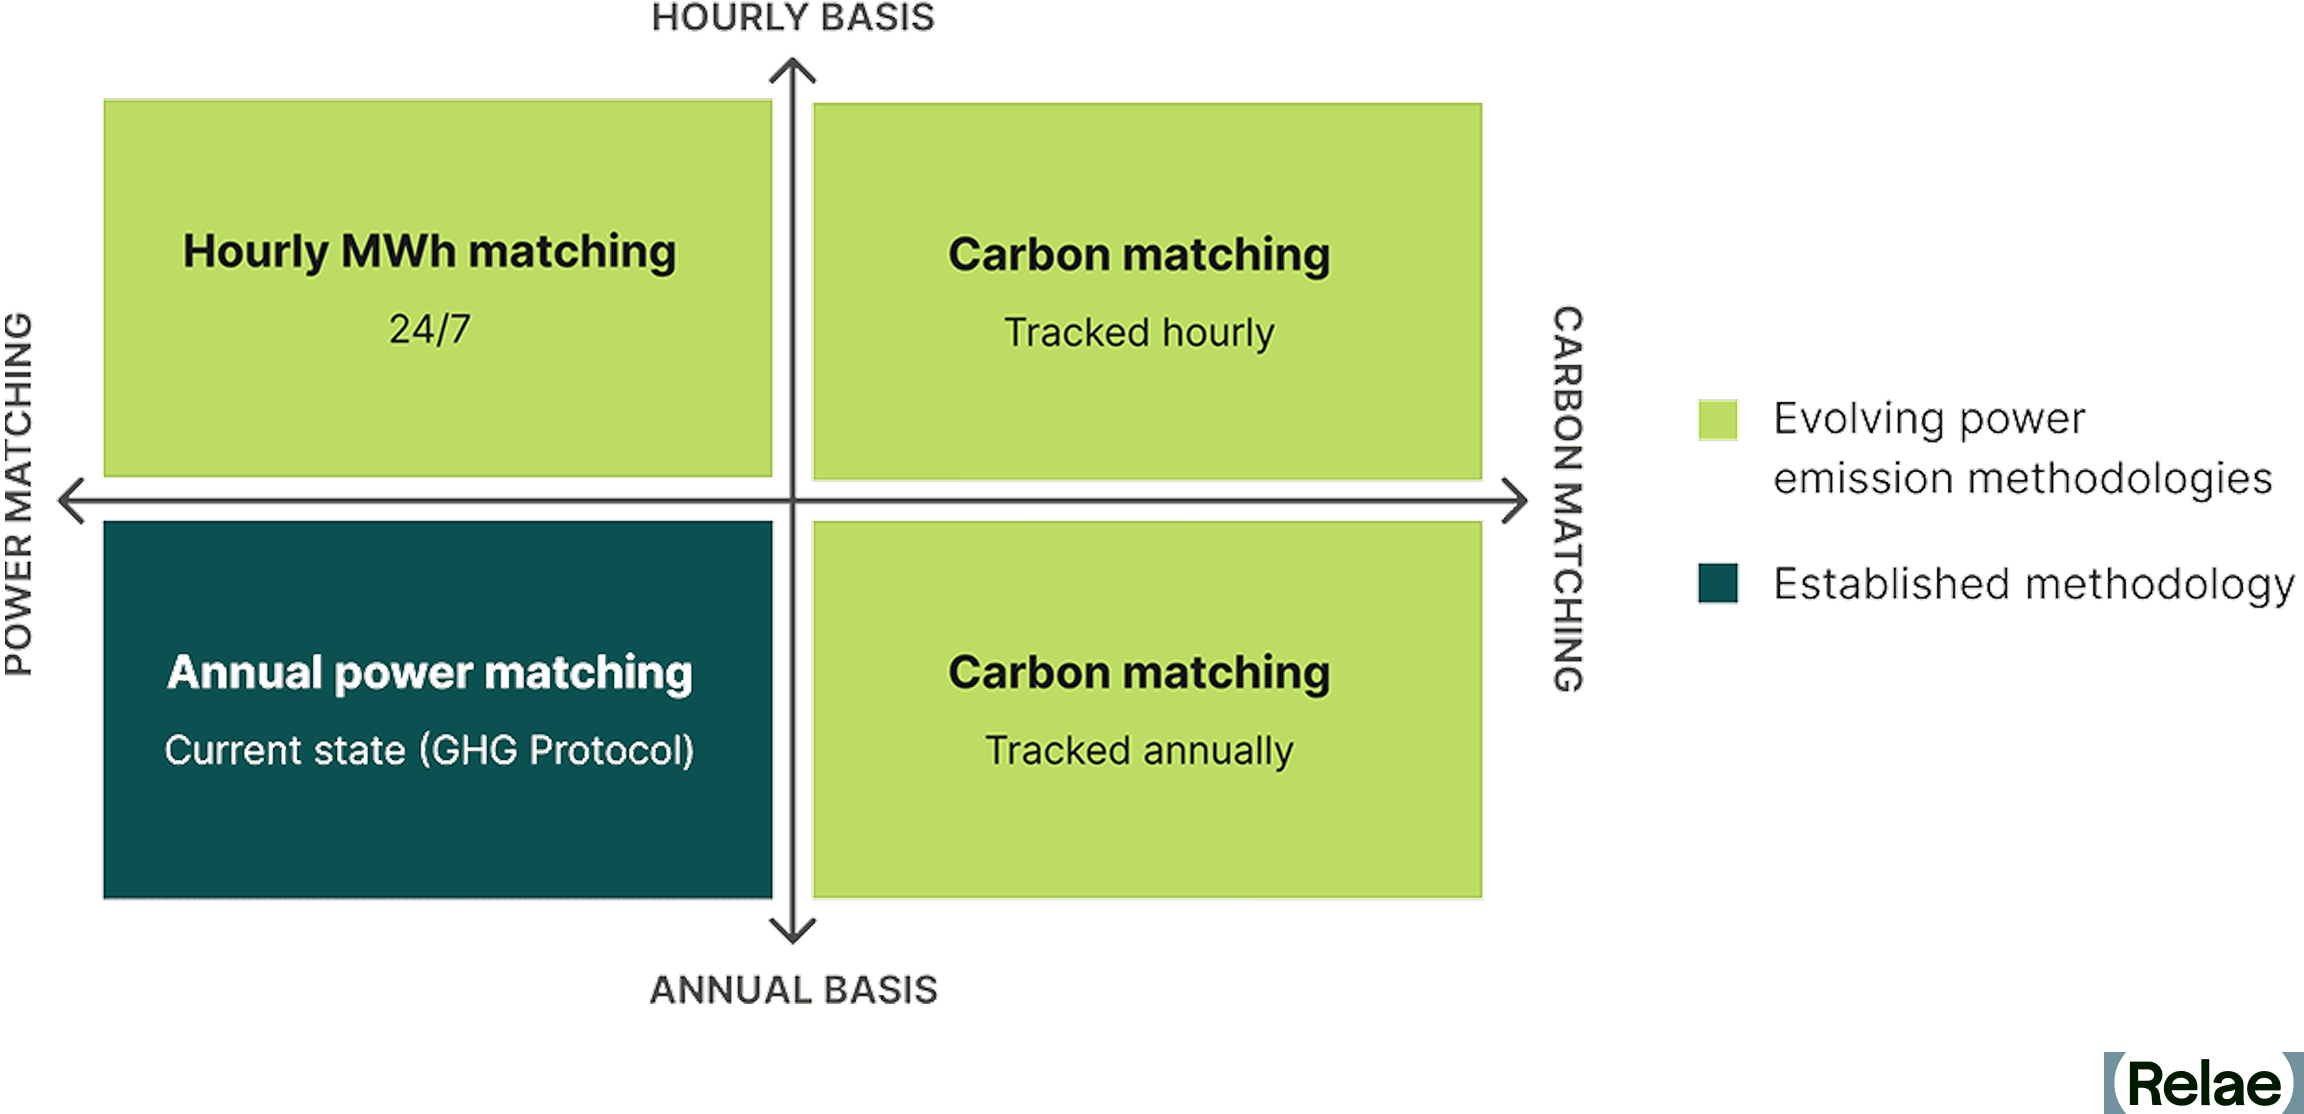
In response to this, the GHG Protocol Scope 2 Guidance is currently undergoing a revision process, which will include how emissions associated with electricity consumption are calculated. A focus of the revision process is on how to better account for the real emissions associated with a corporate’s electricity consumption, and more impactful ways of mitigating them through market-based instruments and other approaches. Advanced power emission accounting methodologies, such as 24/7 power matching and carbon matching, are being explored as ways to better represent the GHG emissions associated with electricity consumption.
- 24/7 power matching emphasizes matching electricity consumption with an equivalent amount of renewable energy production on an hourly basis.
- Carbon matching emphasizes measuring the emissions impact of incremental electricity consumption or production at a specific time.
These emerging methodologies propose a shift toward more granular temporal and region-specific matching, which could require companies to rethink their emissions reporting approach and explore more advanced tracking tools. They may also introduce new strategies beyond market-based instruments for reducing scope 2 emissions, such as time-shifting energy consumption.
As power grids continue to decarbonize and new digital tools emerge, businesses will need to adapt to these evolving methodologies to remain compliant, enhance sustainability strategies, and achieve meaningful reductions in emissions. Companies that proactively integrate advanced power emission tracking into their carbon accounting strategies will be better positioned to lead in the transition to a low-carbon economy.
How to Reduce Scope 2 Emissions
The GHG Protocol provides multiple mechanisms for reducing scope 2 emissions, allowing organizations to shift their energy consumption toward lower-carbon alternatives. These include:
- Reducing energy consumption: Improving energy efficiency in operations can significantly lower electricity use. In some cases, this involves capital investments in more energy-efficient equipment, but in other cases, it can be based on operational changes such as reducing unnecessary lighting, HVAC, and other services during non-working hours. (Electrification efforts, such as shifting from fossil fuel-powered systems to electric alternatives, may actually increase scope 2 emissions, but this can ultimately reduce overall emissions by correspondingly decreasing scope 1 emissions and allowing for renewable energy procurement.)
- RECs: Companies can purchase unbundled RECs (emissions “attributes” separated from the actual electricity product) to offset emissions associated with purchased electricity. While there has been criticism of RECs due to their significant range in quality, high-quality RECs are available, which may include ensuring regional matching, financial additionality, on-line date additionality, or tighter temporal generation to consumption matching. The use of high-quality unbundled RECs is the most accessible and realistic option for most smaller-scale companies to address scope 2 emissions.
- On-site generation and co-location: Installing on-site renewable energy generation, such as solar panels, allows companies to directly offset their electricity consumption from the grid. In some commercial settings, such as companies using leased real estate or co-located data centers, partnering with facilities that prioritize renewable energy procurement can help reduce scope 2 emissions for the facility owner while the facility occupant reduces scope 3 emissions.
- PPAs: Entering into long-term contracts with renewable energy providers ensures companies receive electricity from clean energy sources while supporting the expansion of renewable generation capacity. PPAs are available with standardized contract terms, and some service providers will aggregate demand from multiple smaller companies to reach the minimum required amount for typical PPA contracts. Hedging products are also available to reduce market risks.
- Green tariffs: Many utilities offer green tariffs that enable businesses to purchase renewable energy directly through their electricity provider, often at a premium but with lower emissions impact. For many smaller companies, this is a more viable approach than a PPA with a single renewable generator.
By adopting a combination of these strategies, businesses can significantly lower their scope 2 emissions while aligning with broader sustainability goals and regulatory requirements. The path to decarbonization requires proactive investment in cleaner energy sources, efficient consumption practices, and leveraging market-based instruments to drive the transition toward a low-carbon future.
Why Does Reducing Scope 2 Emissions Matter?
Reducing scope 2 emissions is the underpinning of decarbonizing the power sector and enabling the global energy transition. In 2025, S&P reported that corporate buyers added 15.2 GW of renewable capacity in the US, up from 9.1 GW in 2024, illustrating the growing impact of the corporate sector on the electricity grid. Cleaner grids translate to lower emissions for all energy users. Organizations that actively reduce their scope 2 emissions can contribute to decreasing demand for fossil fuel-based electricity and accelerate the deployment of renewable energy infrastructure.
For companies that own and operate data centers, this transition is especially important. AI data centers consume large amounts of electricity, and their reliance on purchased power makes them a significant source of scope 2 emissions. Since many businesses rely on third-party data center services, reducing emissions from these facilities also helps lower scope 3 emissions across industries. Corporates can influence data centers by requiring that they have a clear and explicit low-emission power strategy in place before procurement.
Beyond direct corporate benefits, reducing scope 2 emissions has a tangible long-term impact on power grids. Increased investment in renewable energy procurement sends a strong market signal, encouraging utilities and developers to expand clean energy projects. As more companies commit to sourcing renewable energy, the overall mix of grid power shifts, making low-carbon electricity more accessible and reducing reliance on fossil fuel-based generation. Ultimately, widespread corporate action in scope 2 emissions reduction supports the broader decarbonization of power markets and strengthens global climate commitments.
Frequently Asked Questions
Will RECs (renewable energy certificates) still count toward scope 2 reductions under the GHG Protocol's proposed changes?
Under the current Scope 2 Guidance, yes—RECs remain a valid market-based instrument. The proposals from the GHG Protocol's recent consultation range from retaining market-based accounting with stricter quality criteria to restructuring how instrument-based claims are reported altogether, and nothing is final until the revised standard is published. What's clear is that scrutiny is rising, particularly for unbundled RECs with weak temporal or geographic connection to a company's actual consumption, so prioritizing high-quality RECs now is the best way to future-proof a procurement strategy.
How would the proposed hourly and regional matching requirements affect companies that rely on unbundled RECs today?
Hourly (24/7) and regional matching would require renewable generation claims to line up much more closely with when and where a company actually consumes electricity. Companies relying on annually matched, unbundled RECs sourced from distant grids would likely see their reported market-based emissions rise under such requirements. The practical preparation is to start collecting more granular (ideally hourly) consumption data and shift toward RECs and contracts with tighter regional and temporal matching.
What's the practical difference between location-based and market-based scope 2 accounting, and will that distinction survive the GHG Protocol's revision?
The location-based method calculates emissions using the average emissions intensity of the local grid, regardless of procurement choices, while the market-based method reflects a company's actual contracts, such as PPAs, RECs, and green tariffs. The consultation explored options from strengthening the criteria for market-based claims to reporting emissions and market instruments in separate, complementary statements. Both concepts will exist in some form, but companies should expect the requirements behind market-based claims to tighten.
When is the new Scope 2 Guidance expected to take effect, and what should companies do now to prepare?
Per the GHG Protocol's July 2026 development plan, a draft of the revised consolidated Corporate Standard is expected for public consultation in 2027, with a final published standard currently estimated for late 2028, and adoption timelines will follow publication. Companies should take action now. Energy efficiency, PPAs, green tariffs, and high-quality RECs reduce real emissions under any accounting regime. Building hourly consumption tracking and auditing the quality of existing REC portfolios now will make any future transition smoother.
Shifting Playbook for Corporate Power Procurement
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s proposed scope 2 revisions would shift many large power buyers from annual renewable energy certificate (REC) accounting to 24/7 hourly matching and reveal a larger emissions gap than most inventories currently report.
- Of all the US grid regions modeled, the emissions gap between annual and 24/7 hourly matching is widest in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the markets where data center load is growing fastest.
- Relae's modeling quantifies the shift from annual to 24/7 hourly matching: serving a 4-gigawatt (GW) data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM, a roughly 800-megawatt premium in PJM that translates directly into cost and siting strategy.
- Closing that gap requires investments in clean, firm generation technologies, like natural gas with carbon capture and storage (CCS), battery storage, and geothermal. The optimal mix varies by market and load profile, which means modeling current and future emissions positions under 24/7 accounting to understand the best procurement options for a specific portfolio.
Annual REC Accounting No Longer Holds at Data Center Scale
For years, large corporate energy buyers have relied on a straightforward approach: purchase renewable energy certificates (RECs) or sign virtual power purchase agreements (VPPAs) to offset market-based scope 2 emissions. Under the current GHG Protocol guidance, these instruments allow companies to claim low or zero emissions regardless of when or where clean energy is actually generated. When corporate clean energy demand was modest, this fueled new renewable project development while aggregate grid emissions were trending down.
That approach worked, until now. Energy demand from data centers and hyperscalers is surging. The Federal Energy Regulatory Commission (FERC) reported more than 50 GW of data center capacity operating in the US at the end of 2025, much of it concentrated in regions where local clean generation cannot keep pace. When corporate clean energy demand was modest, the gap between contractual claims and physical generation was small enough that few questioned this argument. At hyperscaler levels, with load concentrated in a handful of grids, that gap is becoming too large to ignore.
From a climate perspective, well-designed renewable procurement has created real impact by channeling corporate capital into new clean generation, and reducing CO2 emissions anywhere to benefit the climate everywhere. From a grid perspective, power consumption and generation must balance in real time, and the flow of electricity is constrained by the physics of the transmission system. Some regulators, investors, and standard-setters argue that corporate clean energy claims should be grounded in this second, engineering perspective rather than the first. The GHG Protocol's proposed revisions reflect that view, and would force buyers to defend their claims against it.
Relae’s modeling of this 24/7 framework in PJM and ERCOT helps quantify its costs and emissions implications in the markets where the stakes are highest.
What Does 24/7 Hourly Matching Mean for Scope 2 Accounting?
The biggest proposed change to the GHG Protocol’s current Scope 2 Guidance is the move from annual power reporting and matching to a 24/7 approach. Instead of calculating emissions with an annual emissions factor (EF) based on their independent system operator (ISO) or eGRID region for each megawatt-hour (MWh) consumed, companies would need to use hourly-specific EFs.
Companies would still be able to retire RECs to reduce their market-based emissions. However, companies would need to show that these RECs came from clean energy that was generated on the same grid, in the same hour as their facilities consumed power. This makes annual, location-agnostic REC retirement, currently the dominant practice, insufficient for 24/7 market-based accounting.
Both the time restriction (hourly matching) and the location restriction (generation on the same grid as consumption) will make it more difficult for companies to retire RECs. For example, because today's methodology is location-agnostic, a New York-based company can retire RECs from a Texas wind farm (purchased unbundled or via a VPPA) to reduce its reported market-based scope 2 value. This has allowed renewable development to follow the best resource sites rather than the load. Similarly, the time of day that the wind farm generates energy is irrelevant, as long as it is approximately in the same calendar year.
Under the proposed revisions, retiring these RECs would no longer be acceptable for the New York company, since they would fail both location- and hourly-matching requirements. As a result, companies with large REC portfolios today may no longer be able to retire them in order to reduce their market-based scope 2 emissions, if the proposed revisions take effect. These companies may face significant unmatched consumption under 24/7 accounting, especially during evening peaks or grid stress events when fossil-based generation fills the gap.
Annual Matching vs 24/7 Hourly Matching
The figure below illustrates the gap between what a representative large buyer reports under the current annual location- and market-based methodologies, versus what an hourly 24/7 analysis reveals.
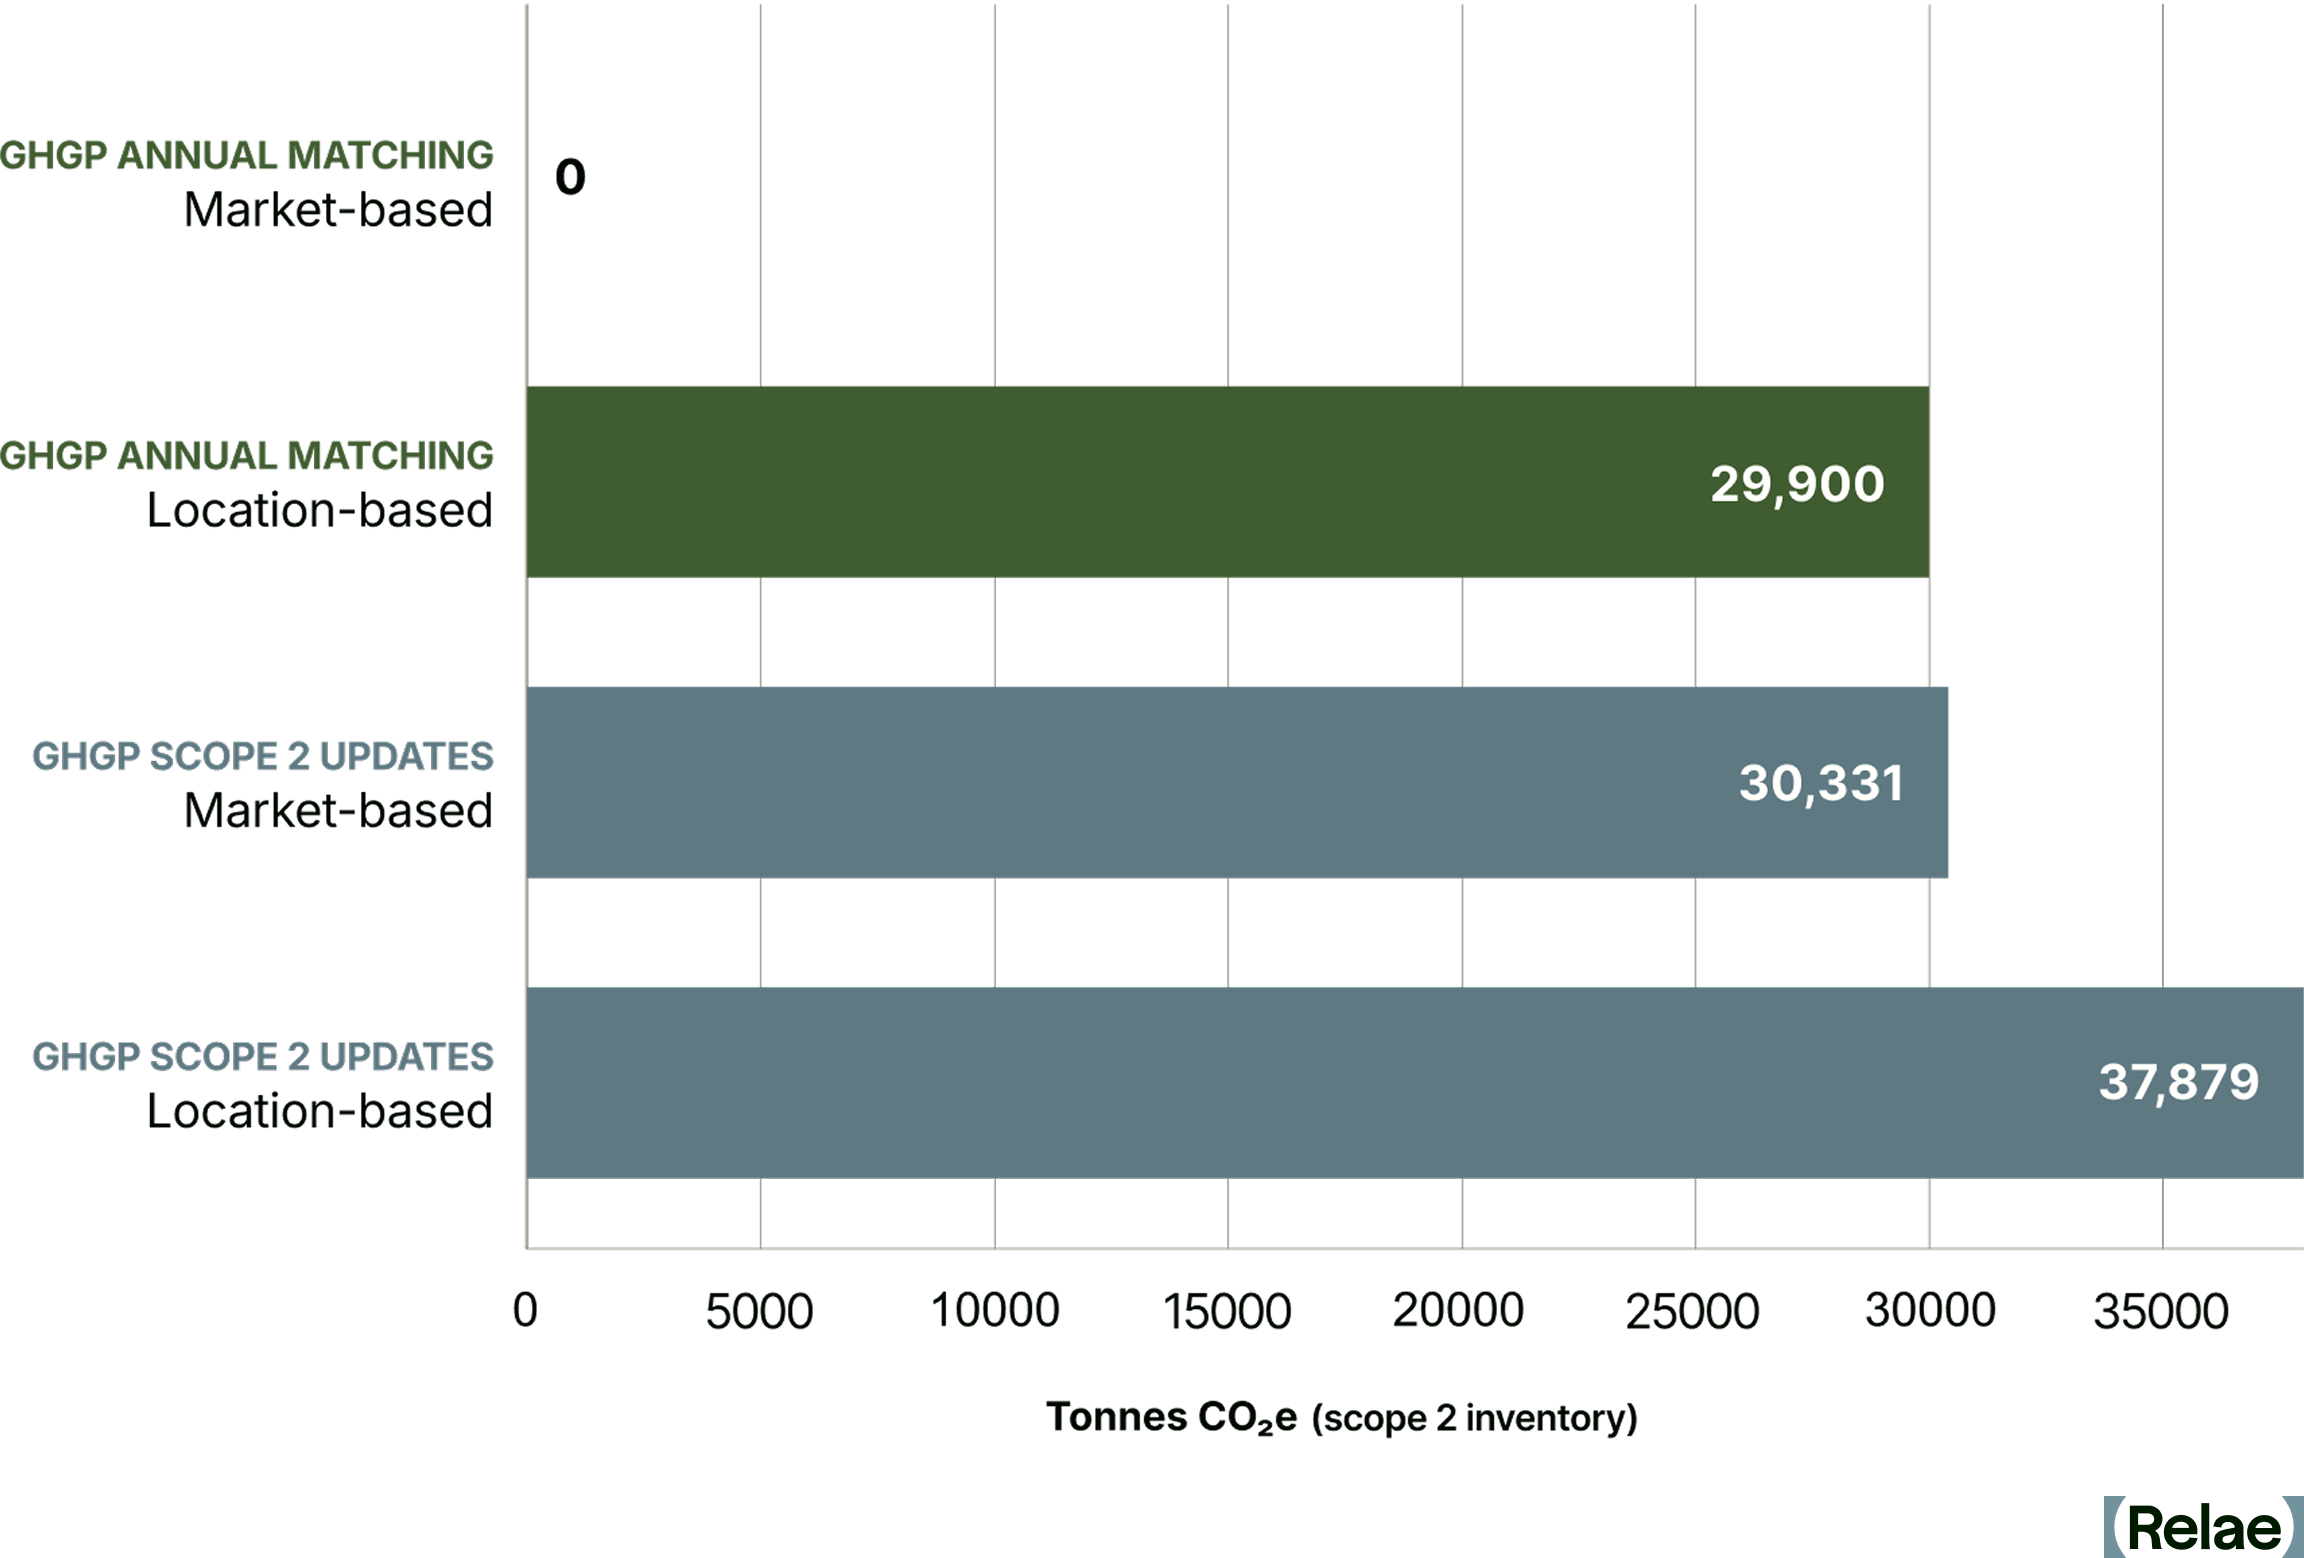
Understanding this emissions gap is the essential first step for buyers to make informed decisions about which instruments to retain, which contracts to renegotiate, and where new investment will matter most. If the proposed scope 2 revisions are enacted, companies procuring clean energy will be disincentivized from buying RECs sourced from variable renewables in distant locations, and instead will find it more favorable to invest in same-grid clean, firm generation, such as geothermal, nuclear, and renewables plus storage. RECs from these projects would qualify to be retired against market-based scope 2 emissions under the proposed revisions, where today's distant-wind or off-peak-solar RECs would not.
Where Pressure Is the Highest: ERCOT and PJM
Two markets stand out for projected hyperscaler load growth: PJM, which covers the extended mid-Atlantic region, and ERCOT in Texas. Both are on track to absorb massive increases in data center demand over the next decade, and both expose the limits of annual REC accounting in ways that will be hard to ignore under the new proposed framework.
PJM: 60% Fossil Generation Means High Marginal Emissions
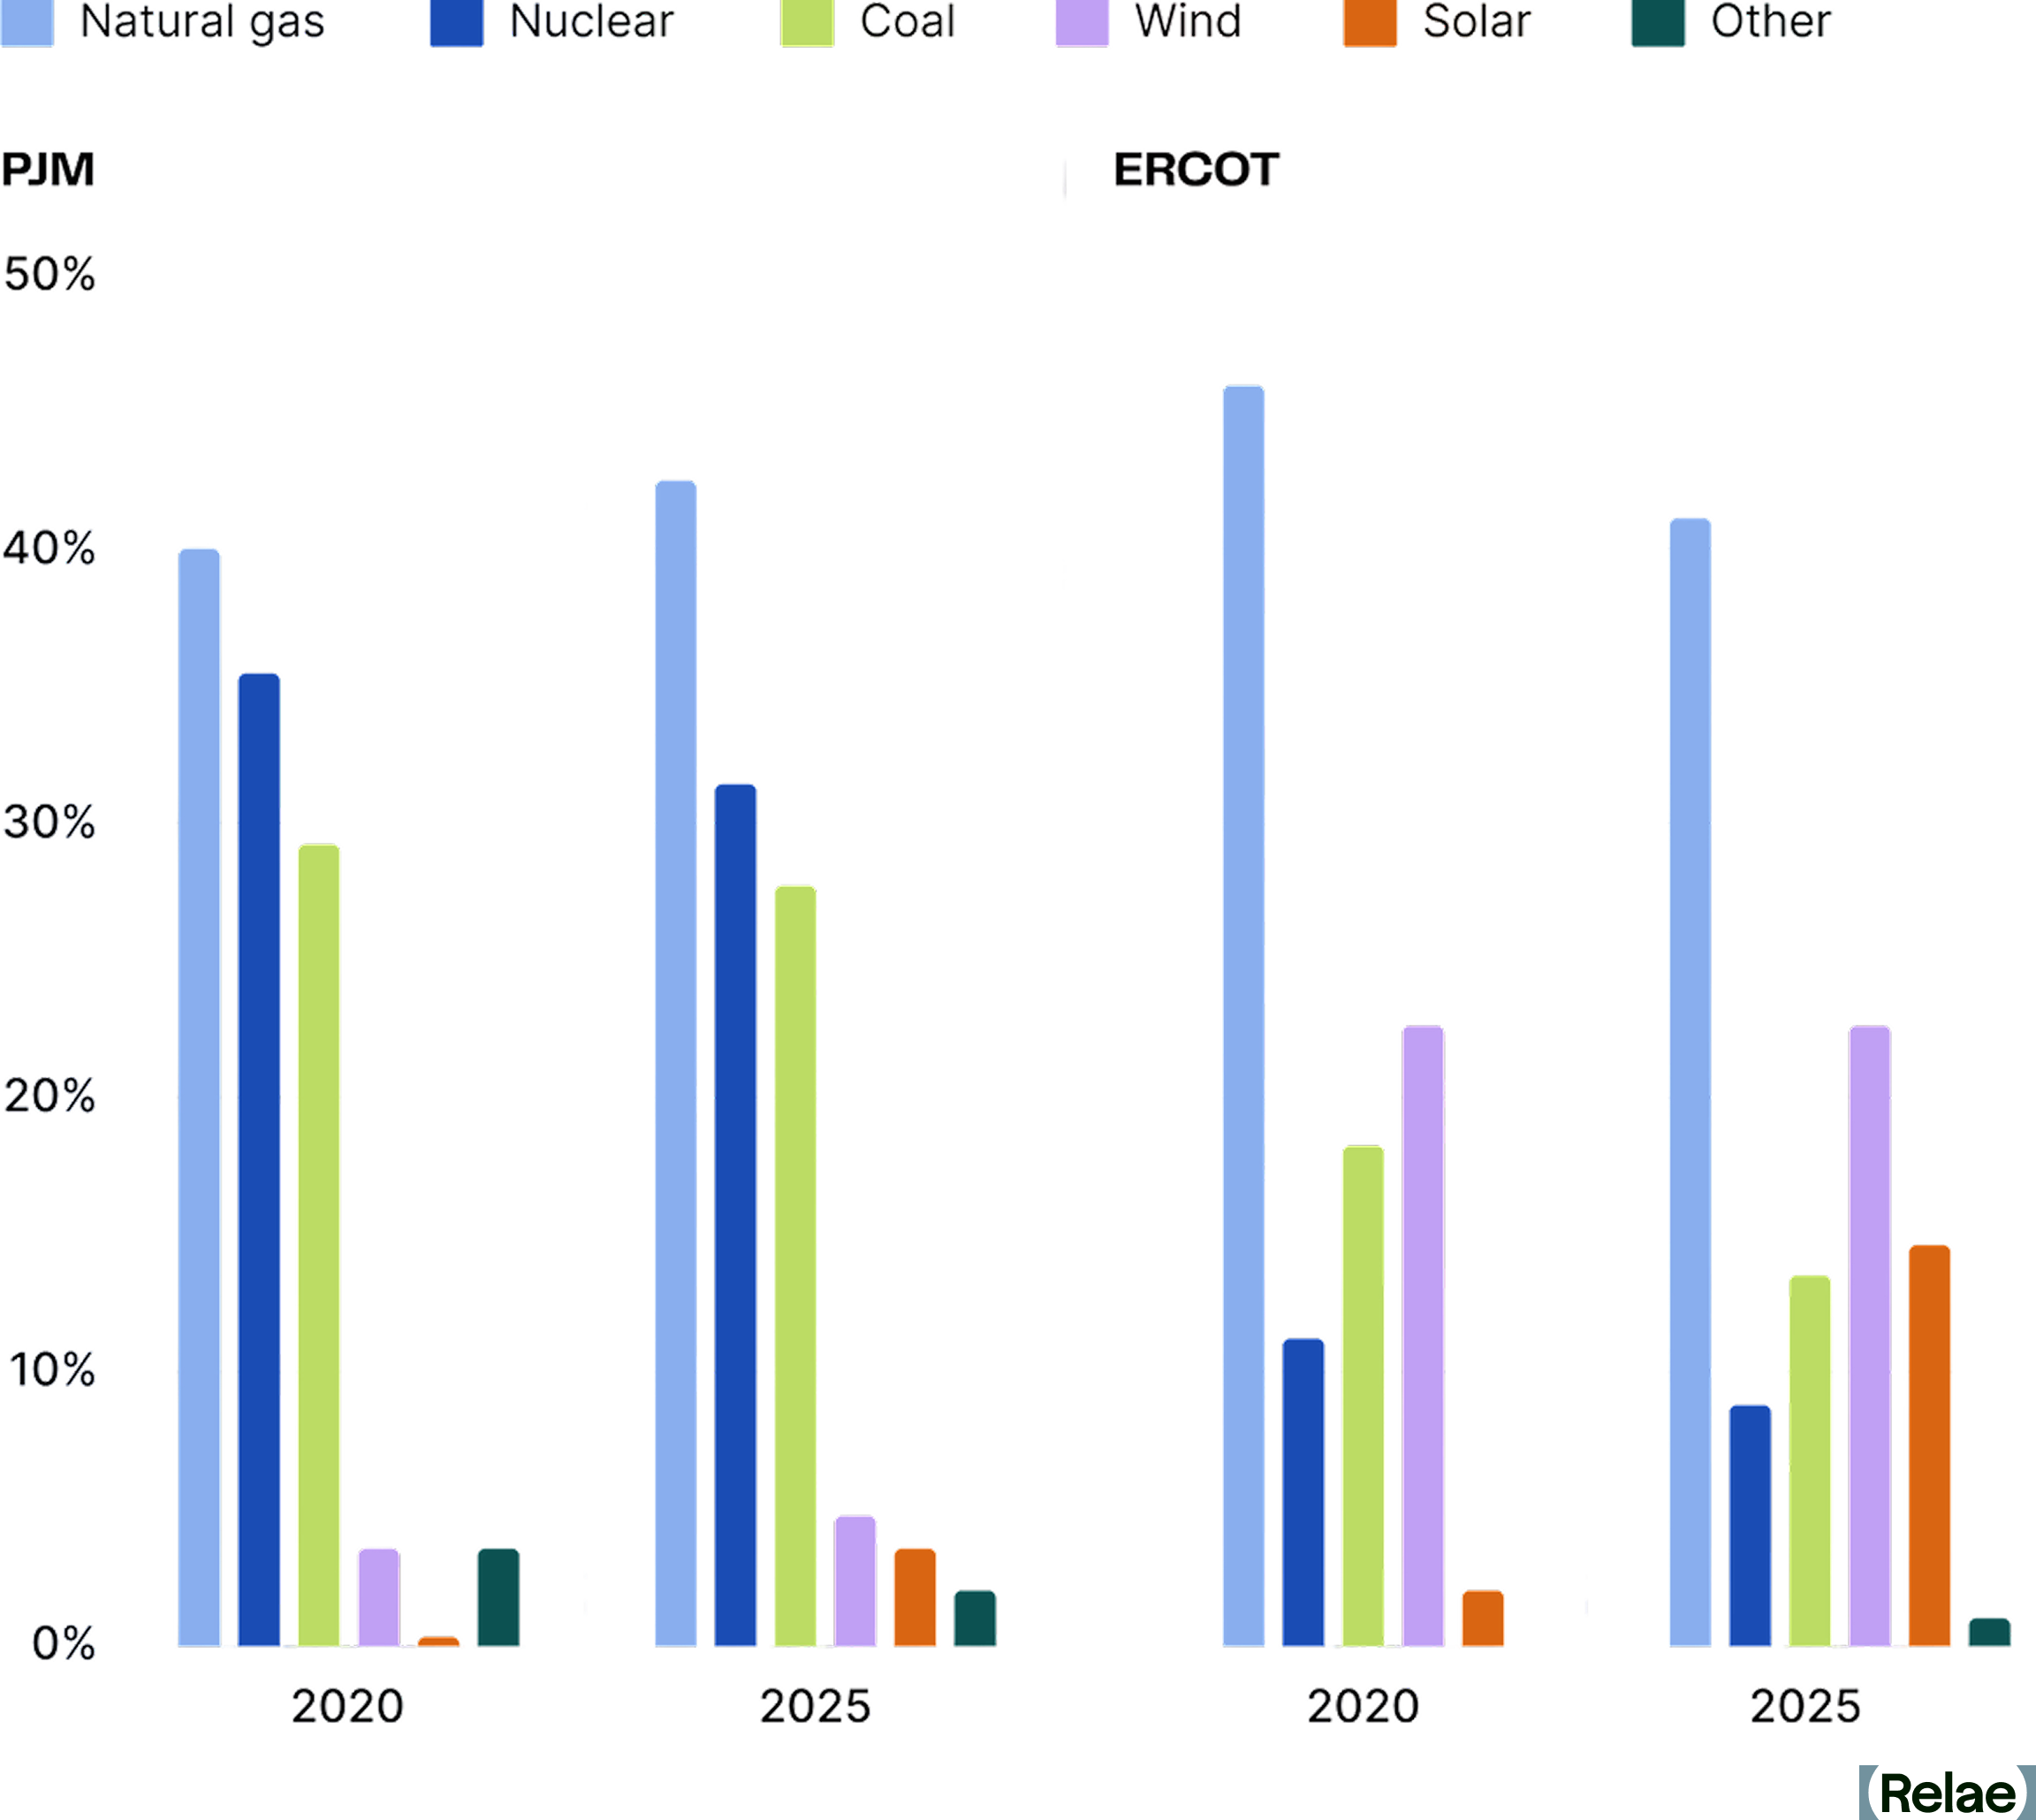
PJM is one of the largest and most complex wholesale electricity markets in the world. Its generation mix still includes 60% coal and natural gas, which means hourly emissions intensity remains high, particularly during evening peaks and grid stress events when fossil generation dominates the dispatch stack.
Buyers relying solely on annual REC retirement may show low market-based scope 2 emissions today, but a 24/7 analysis tells a different story. For PJM-based buyers, this means hourly matching gaps will be largest during evening and overnight hours, when nuclear and storage become disproportionately valuable relative to additional solar.
ERCOT: Solar and Wind Don’t Peak When Demand Does
Texas has abundant wind and solar, with solar generation growing nearly 7x since 2020, but those resources don’t always run when demand peaks. While fossil-based generation has declined since 2020, it still comprises more than half of ERCOT’s generation. Solar dominates midday, wind peaks in the evening, and natural gas fills the gaps, especially during high-demand evenings or extreme weather events.
Buyers with large ERCOT footprints may find that VPPA portfolios, which generate most of their clean energy in off-peak hours, already satisfy the proposed location-based test but fail on hourly matching. Battery storage and demand flexibility could help bridge the gap.
Figure 3 below quantifies that gap in both markets by showcasing the carbon-free energy (CFE) score in ERCOT and PJM, as well as the additional capacity required for a 4 GW load to achieve a 100% CFE target. The CFE score is the share of grid-supplied electricity in a given hour that comes from carbon-free sources, and is the metric the proposed scope 2 revisions would use to evaluate hourly matching. A 100% CFE target means electricity consumption is matched to carbon-free generation in every hour of the year.
In the left panel, a representation1 of each market's 2030 hours are sorted by grid (CFE) score, from the dirtiest hour on the left to the cleanest on the right. Neither grid approaches 100% carbon-free on its own, and the shaded areas represent the unmatched hours a buyer claiming 100% clean energy through annual instruments would actually carry under 24/7 accounting. The gap is the maximum unmatched hours a buyer might be exposed to, as some RECs procured through annual matching may qualify under the new rules, if satisfying the locational and hourly requirements.
The right panel translates that gap into action. The additional co-located clean generation and storage required to serve a representative 4 GW load (roughly 5% of the forecast 2030 C&I load in ERCOT and 4% in PJM) at a 100% hourly CFE target, on top of what the underlying grid already provides.
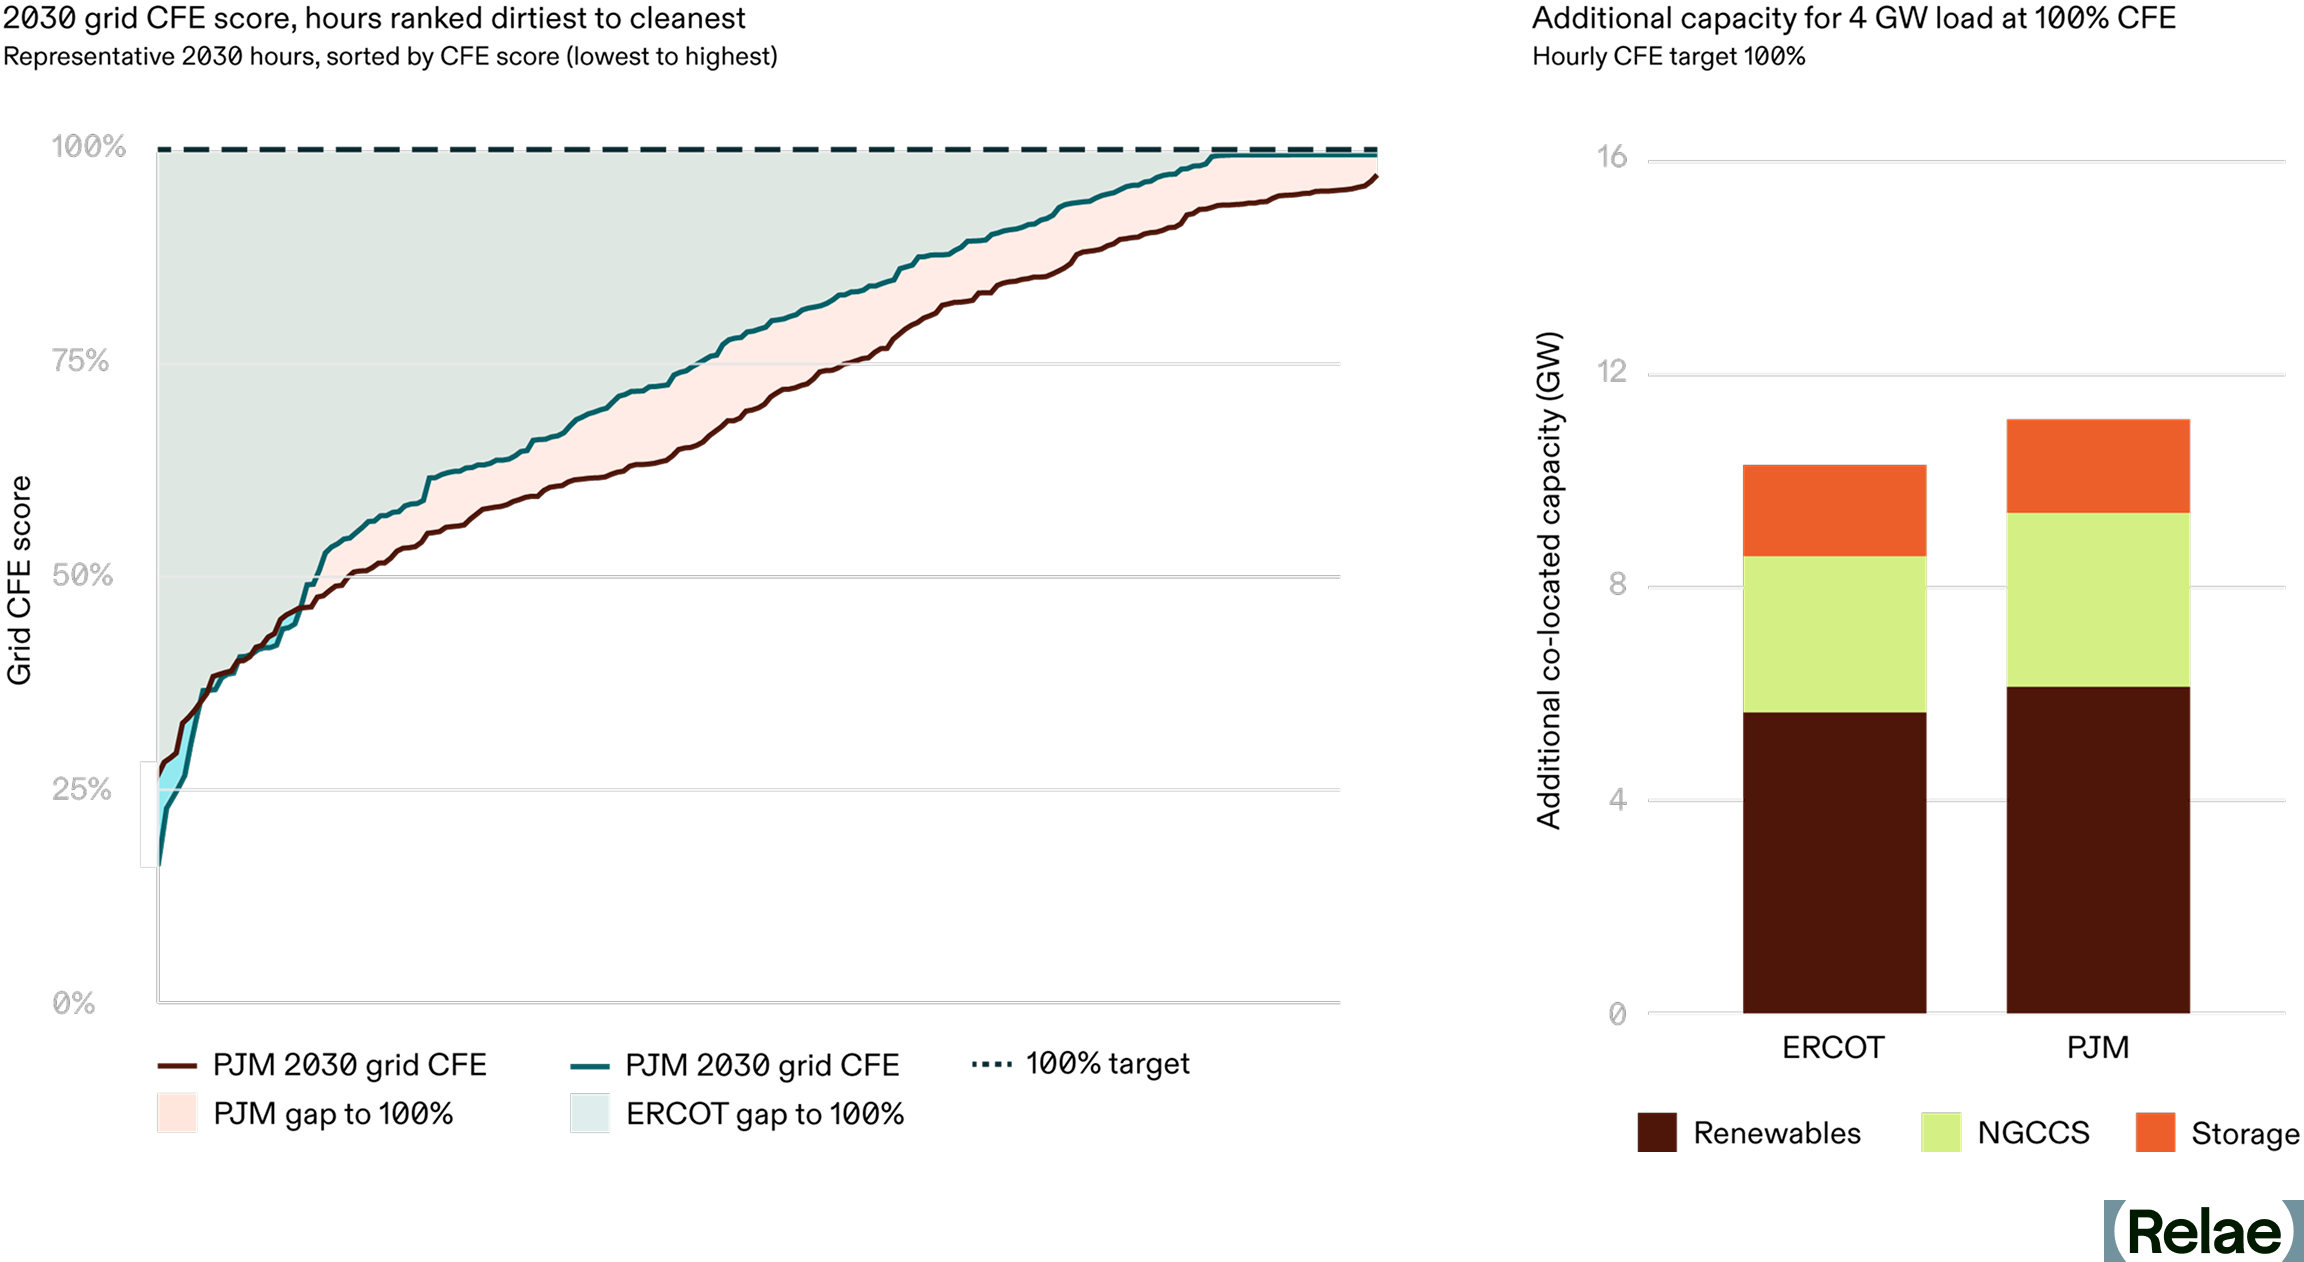
A few patterns are worth highlighting. First, the left panel confirms that PJM’s grid will still spend materially more hours below 100% carbon-free than ERCOT’s in 2030, a direct consequence of the coal- and gas-heavy generation mix described above. Notably, ERCOT's curve reaches 100% in a meaningful share of hours (windows when the grid is running entirely on carbon-free resources), while PJM's never does, meaning some fossil generation is dispatched in every hour.
Second, the ISO a buyer operates in drives a meaningful difference in build-out: hitting 100% hourly CFE for a 4 GW load takes 9.6 GW of additional capacity in ERCOT and closer to 10.5 GW in PJM. This indicates the advantage of achieving hourly and locational matching in already clean grids, which may influence a buyer choosing where to site new workloads.
Renewables have the largest share of the additional capacity in both markets (5-6 GW), paired with significant long-duration energy storage (~2 GW), while natural gas with CCS provides meaningful clean, firm capacity (~3 GW). ERCOT’s storage share of capacity is slightly larger, reflecting the midday-solar/evening-load mismatch, while PJM leans a bit more on natural gas with CCS, where clean, firm generation does more of the heavy lifting due to lower wind speeds and solar irradiance than Texas.
The right panel also illustrates why clean, firm technologies (natural gas with CCS, advanced nuclear, and enhanced geothermal) are likely to be included alongside renewables and batteries in any serious 24/7 portfolio. With only renewables and batteries, hitting the same target requires about double the total generation and storage capacity. In both markets, targets that look achievable today on an annual REC basis will require materially more capital and a different mix of resources, under 24/7 accounting.
Top Questions Large Power Buyers Need to Model Before the Rules Change
The GHG Protocol revisions are not finalized, and the timing of any mandate remains uncertain, which is exactly why modeling cannot wait.
A useful self-test for any large power buyer is: can your team answer the following today with defensible numbers?
- What is your hourly CFE score across your largest load centers, and how far does it sit from your reported market-based emissions?
- Which of your existing VPPAs and REC contracts hold value under 24/7 accounting, and which become effectively stranded?
- What mix of resources delivers the incremental clean, firm capacity that closes your gap in PJM, ERCOT, or wherever your load is concentrated at the lowest cost?
- If your next gigawatt of load were sited in a different ISO, how would your emissions position change?
Clean firm projects do not appear off the shelf. Advanced nuclear, enhanced geothermal, and natural gas with CCS all carry multi-year development timelines, and corporate offtake agreements are often what get these projects financed in the first place. Buyers who engage now help shape the project pipeline that will be available in their target markets in 2030, and can lock in offtake terms before competition for the most valuable sites tightens. Buyers who wait until the methodology is final will be working with shorter lead times, fewer development partners, and less leverage to specify projects that fit their load profiles and hourly matching needs.
Frequently Asked Questions
What is 24/7 hourly matching, and how does it differ from today's REC accounting?
Today's scope 2 accounting lets companies retire renewable energy certificates (RECs) from any grid, at any time of year, to offset their emissions. The GHG Protocol's proposed 24/7 hourly matching would require RECs to come from clean generation on the same grid, in the same hour a facility consumes power, making most of today's location-agnostic RECs ineligible for market-based accounting.
Why are PJM and ERCOT under the most pressure from this shift?
Both markets are absorbing the fastest-growing data center load in the country, and both still lean on fossil generation to meet demand outside peak renewable hours. PJM's generation mix is 60% coal and gas, while ERCOT's solar and wind often don't peak when demand does, so buyers in these markets face the largest gaps between their annual REC claims and their actual hourly carbon-free energy score.
How much additional clean capacity does it take to close the gap?
Relae's modeling finds that serving a 4 GW data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM. That capacity mix leans on renewables and long-duration storage in both markets, with natural gas with CCS playing a larger role in PJM, where wind and solar resources are weaker.
What should power buyers do before the GHG Protocol revisions are finalized?
Start modeling now. Buyers should know their hourly carbon-free energy score, understand which existing VPPAs and REC contracts hold value under 24/7 accounting, and identify the lowest-cost mix of clean, firm resources that closes their gap. Clean firm projects like advanced nuclear, enhanced geothermal, and natural gas with CCS take years to develop, so buyers who engage early have more influence over the project pipeline and better offtake terms.
Modeling the 24/7 Emissions Gap with Relae
For large power buyers assessing what the proposed GHG Protocol revisions mean for their power procurement portfolio, Relae's Advanced Power Emissions Analysis solution models the gap between current market-based reporting and what 24/7 accounting would reveal—by market, load profile, and technology stack.
How Does Geothermal Compare to Other Clean Firm Power Options?
Key Takeaways
- Geothermal shares the clean firm category with only three other technologies: nuclear, natural gas with carbon capture and storage (CCS), and solar or wind paired with long-duration energy storage (LDES).
- Buyers comparing geothermal to solar or unabated natural gas power contracts are comparing different products: one isn’t firm, the other isn’t clean, and both remain cheaper options because they satisfy less of what buyers currently need.
- Geothermal’s cost premium is real, but so is the value it delivers. Geothermal can reach 90%+ capacity factor, delivering dispatchable clean power around the clock, and it sidesteps the gas turbine manufacturing backlogs and pipeline infrastructure delays slowing other firm power technologies.
- Geothermal is closer to commercial readiness than most buyers realize. As demand for firm, low-carbon power intensifies, geothermal warrants a serious look alongside nuclear and gas with CCS.
Geothermal is Gaining Traction Despite Its Cost Premium
Hyperscalers, corporate energy buyers, and data center developers face unprecedented pressure to procure clean power. Wind and solar have played a major role in meeting this need, but they are intermittent, and load growth is accelerating and changing. This market pressure is creating bottlenecks that cannot be solved without new grid infrastructure and/or substantial additions of energy storage. Geothermal, which does not suffer from intermittency, has gained tremendous momentum as a challenger to wind and solar, yet it carries one seemingly glaring disadvantage: its cost.
Yet, major utilities and hyperscalers alike are lining up for geothermal offtake anyway: Southern California Edison and Google have signed separate contracts with Fervo, and Meta has two 150 MW agreements in place with Sage and XGS. These contracts are signaling a growing shift in power markets: not all megawatt-hours are created equal, and the cheapest contracts may no longer contain what buyers truly need.
Fast, Clean Firm Power: What Buyers Need Today
In the clean firm power evolution, clean came first. Buyers signed solar and wind power purchase agreements (PPAs) and matched their annual consumption with renewable energy contracts, or offset them with renewable energy certificates (RECs). With lax carbon accounting, solar and wind remain unbeatable on price. But annual emissions tallies conceal something important—a buyer can procure as much renewable electricity as it consumes over a year while still depending on the rest of the grid during the hours when those resources are unavailable. To close that gap, buyers need a source that delivers clean power around the clock, firmly in every hour, on demand.
Two unforgiving demands have followed since: speed and location. With today’s rapid buildout of new load, a power source needs to come online in time to deliver power when the customer needs it. It is also important to connect near a customer’s location because existing transmission assets are often fully subscribed. Failure on either axis can disqualify a project. However, a contract that can meet all attributes: clean in every hour, firm on demand, quick to deliver, and able to reach the load, might be the best (or only) option available. It is also likely to be considerably more expensive than those annual solar benchmarks that only met the clean condition.
Four Technologies Make the Clean Firm Power Shortlist
Given this strict set of constraints, what power options should buyers consider? The right set of technologies should aim to solve as many of the aforementioned conditions as possible, and that leaves a fairly tight shortlist:
- Solar or Wind paired with Long-Duration Energy Storage (LDES): To achieve the level of reliability that many buyers, including data centers, require, solar or wind would have to be paired with LDES, beyond 4–8 hours, to be able to cover evening hours and remain online during increasingly common extreme weather events. While there are promising LDES technologies on the horizon, most remain expensive and not yet widely commercial. Costs rise significantly compared to a standard solar or wind PPA, and viability varies by location. This will be increasingly competitive as storage costs fall, but not yet a mature firm-power solution at scale.
- Natural Gas with CCS: With large amounts of unabated natural gas generation coming online, CCS is an attractive option to mitigate a large portion of these emissions while retaining time to power (by building gas first and adding CCS later) and the dispatchability of gas-fired power. On the flip side, CCS is operationally complex, geographically restricted, and - unlike other options here - failure at any point in the CCS chain directly impacts the carbon intensity of power delivered. Gas-fired generation is also reliant on the gas delivery pipeline infrastructure, which may face capacity constraints. Finally, natural gas with CCS is 50% more costly per MWh than unabated firm gas.
- Nuclear: Nuclear is seeing renewed interest from a wide range of corporate buyers and investors. Conventional nuclear and small modular reactors (SMRs) are attracting funding and offtake deals. While nuclear power holds high potential, long development timelines, high capital costs, and technology risk remain barriers to commercializing the next wave of nuclear technologies.
- Geothermal: Geothermal can provide firm, dispatchable, and low-carbon power with capacity factors typically above 90%. Development timelines can be faster than nuclear in regions where resources are already proven, with some projects approaching commercial readiness now. Geothermal technology is still geographically constrained, but enhanced geothermal systems (EGS) are poised to expand their geographical flexibility by reducing the number of siting variables.
How to Evaluate the Right Clean Firm Power Technology for Your Project
How do these various options stack up? We compared them across six dimensions:
- Firmness: how reliably a resource can deliver power on the hour, on demand
- Carbon: the lifecycle emissions intensity when considering the operational emissions of the generating facility and the broader system carbon impacts required to meet any reliability gaps
- Time to power: a measure of how long it takes to get from “we need power” to delivery, including interconnection and schedule risk
- Cost (current): the likely cost of a PPA if signed today
- Execution risk: a measure of how likely a project’s claims regarding price, timing, and performance will hold
- Siting flexibility: a measure of how constrained a resource is to a specific geography
This frame is ultimately something the buyer should score themselves; below you will find our current read. Red (unfavorable) represents a weakness that can end an evaluation on its own, green (favorable) means the dimension won’t constrain the decision, and yellow (moderate) sits somewhere in between.
Comparing the clean firm power options is, perhaps ironically, challenging along the “clean” and “firm” lines. Every serious contender delivers low-carbon power around the clock, because that is the price of admission. Not one technology earns an unfavorable rating in those categories. And that is the catch: every weakness in the comparison table sits somewhere else. The dimensions that ultimately win (or end) these contracts may be the ones that the “clean firm” label can obscure or oversimplify.
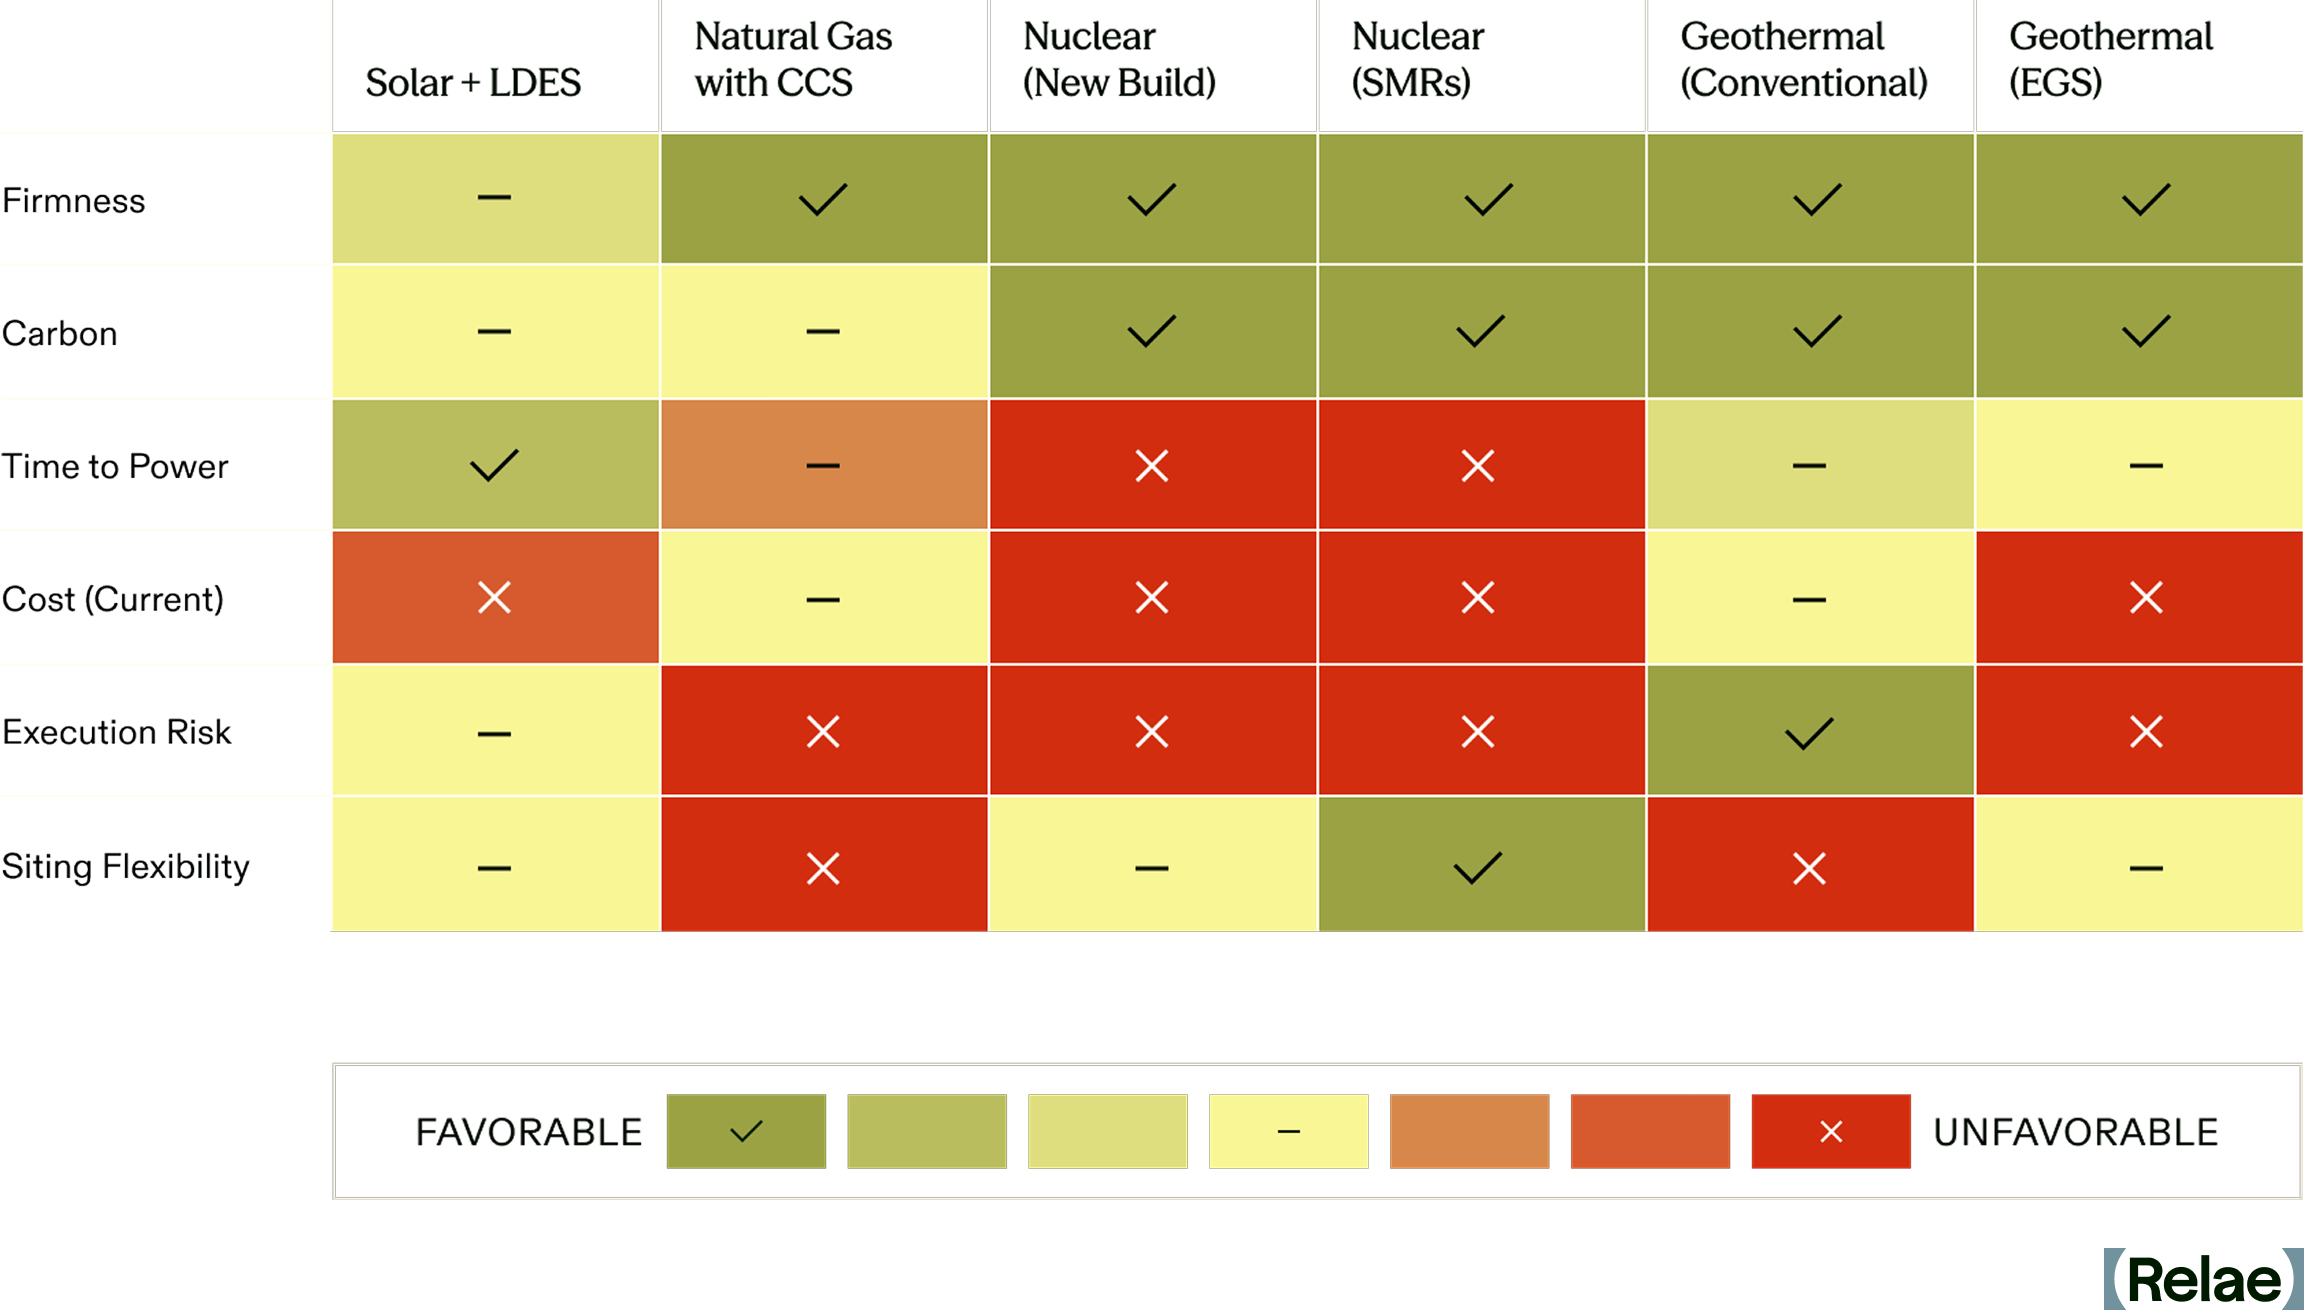
A resource that cannot be energized for a decade, or sited near load, or delivered at a price a buyer cannot defend internally, may be infeasible regardless of what else it offers. None of the four clean firm generation technology groupings clear every hurdle today, but they can satisfy different buyer priorities.
Solar or wind with LDES offers more buyer flexibility, at a price. Enough generation, storage, and other firming can deliver the reliability required, and the buyer sets that target. But the increments get expensive quickly, especially when reliability gaps remain long or unpredictable. Covering more hours means more storage and more generation to fill it, so each step toward firmness parity costs more than the one before it. Firming shortfalls also carry carbon consequences, depending on what gets called to compensate. Those emissions may be absent from GHG accounting ledgers, but that doesn’t stop them from hitting the atmosphere.
Gas with CCS is challenged by execution and siting because the product depends on a chain: gas generation, capture, transport, and a permitted storage site capable of permanent CO2 disposal at scale. Each piece can be developed and tested, but low-carbon electricity requires all of them to work together, which can only be demonstrated once all are built. A buyer cannot substitute a link, and cannot observe the whole chain before committing. Clean, in this sense, is conditional, and the delivered power could end up being far more carbon-intensive than advertised.
Nuclear ranks poorly on time, cost, and execution, but full-scale reactors and small modular reactors carry those weaknesses differently. A large reactor arrives in one piece, and its schedule and final cost come into focus as construction advances. By then, years and billions are committed; a buyer cannot learn from a fraction of a reactor before deciding whether to finish it. Small modular reactors are designed to break that capacity into increments a buyer could add as demand grows, which would ease the one-piece problem. But none are operating commercially in the US yet, and the signed deals target first power in the 2030s, so the modular promise is still years out.
Geothermal’s weaknesses work somewhat differently. Conventional hydrothermal is tightly constrained by location, which buyers can screen before choosing where to procure, or co-locate where possible. Next-generation geothermal, including EGS, could widen that geography considerably.
For EGS, the largest remaining uncertainty is execution: whether the developers can replicate successful drilling and reservoir performance at commercial scale. Part of that risk belongs to the rock, and no contract can make a reservoir perform. But drilling also produces information before the entire project has been built, and geothermal capacity can often be developed incrementally as needed. A buyer can require resource evidence before committing, tie later commitments to demonstrated performance, or spread procurement across projects rather than depend on a single field.
Geothermal’s flexibility has limits. A buyer who needs full capacity by a fixed date may have little room to wait for wells to perform before committing to the next phase. And successful wells do not eliminate risk in project expansion or guarantee performance in other locations. Execution risk stays with the resource. What geothermal offers is more opportunity to learn about that risk while a buyer can still do something about it.
Revisiting the Geothermal Premium
Geothermal contracts, especially EGS, remain expensive. But that premium looks different on this side of the comparison. Clean has a cost, but so does firmness, speed, reach, and execution. Every clean firm option pays for those attributes somewhere. Solar and wind contracts will remain cheap by comparison, but it’s the wrong comparison: the market signing geothermal contracts is pricing a much larger product.
That still leaves a hard decision. Geothermal and gas with CCS carry execution risk and siting constraints. Nuclear asks more of the buyer on cost and time. Firmed solar asks more as reliability requirements rise. The best option will change with each buyer, location, and project. Geothermal’s place in that choice is changing quickly. EGS is expanding where projects can be developed, drilling costs are falling, and commercial experience is growing. Those advances are bringing geothermal into consideration for buyers who previously had little reason to look its way.
And that may be the more revealing aspect of the geothermal market today: buyers are signing those contracts with the alternatives in full view. Their decisions offer an early indication of what clean firm power delivered in the right place and at the right time is worth, and which risks buyers are willing to carry to get it.
Frequently Asked Questions
Is Geothermal Cheaper Than a Solar PPA?
No, a geothermal power contract can be significantly more expensive than a solar PPA. But they're not the same product: solar meets annual clean-energy targets, while geothermal delivers firm, dispatchable power around the clock, which is why buyers are increasingly comparing it to nuclear and gas with CCS instead.
Is Geothermal Cheaper Than Solar with LDES?
Not necessarily on a per-contract basis, but the cost structures behave differently. Solar with LDES gets more expensive with every additional hour of reliability a buyer needs, since covering more hours means adding both more storage and more generation to fill it. Geothermal's premium, by contrast, is priced into the contract upfront as a firm, dispatchable product from day one.
How Does Geothermal's Risk Compare to Gas with CCS?
Differently, in a way that matters to buyers. Gas with CCS depends on a chain (generation, capture, transport, and storage) that can only be verified once the whole system is built, so a buyer can't test it piece by piece. Geothermal generates performance data incrementally through drilling, letting buyers require resource evidence or tie commitments to demonstrated results before committing further, though this data does not come free.
Which Deploys Faster, Geothermal or Nuclear?
Geothermal, in regions with already-proven resources. Fervo's Cape Station, for example, broke ground in 2023 and is on track for first power in late 2026 and 500 MW by 2028: a fraction of a typical new-nuclear large reactor timeline.
Inside NERC’s Level 3 Alert on Data Center Loads
Key Takeaways
- On May 4, 2026, the North American Electric Reliability Corporation (NERC) issued a rare Level 3 “Essential Actions” Alert in response to repeated events in which 1,000+ megawatts (MW) of computation load dropped off the bulk power system in seconds, leading to major grid stability issues.
- The pattern has since escalated: on July 22, 2026, a transmission fault in Ashburn, Virginia took more than 3 GW of data center load offline in seconds—roughly 3% of PJM demand at the time.
- NERC also published Reliability Guidelines that push the same concerns into long-term planning, explicitly recommending resource adequacy models that capture firm vs. flexible load, behind-the-meter resources, and AI training operating windows.
- For transmission operators and balancing authorities, the releases compel new scrutiny of how computational loads affect stability and resource adequacy. For hyperscalers and other large loads, those assessments now sit on the critical path: if operators cannot show through advanced modeling that they can integrate the new loads, interconnection and buildout plans stall.
- Meeting the bar takes advanced grid modeling at multiple time and spatial scales, from sub-second stability through long-horizon capacity and resource adequacy, to evaluate the role of large load portfolios considering demand response, storage, and co-located generation.
Why Grid Frequency Matters for Large Loads
When we turn on the lights or charge our phones, it’s easy to forget that electricity travels through the power grid as alternating current. Sixty times a second—far faster than our eyes can see—the flow of electricity alternates back and forth along the wires making up both the transmission and distribution parts of the North American grid.
Power generation equipment and most large industrial loads are designed to work with this 60 Hertz (Hz) alternating flow and must be synchronized precisely to this rhythm to function. Grid synchronization is so important that it can even have geopolitical implications.
For some electrical equipment, getting out of sync with the grid’s frequency can lead to malfunctions or even physical damage and destruction. That’s why grid-connected equipment is protected by circuits that automatically disconnect from the grid (“trip offline”) if the grid frequency begins to deviate by even one percent. For minor equipment, this is easily managed. However, when large amounts of generation or load trip offline quickly, it can lead to rapidly cascading grid blackouts affecting tens of millions of people with costs in the billions.
Grid operators pay extremely careful attention to factors that could cause grid frequency to deviate. The grid’s frequency stays near 60 Hz only when total power generation and consumption (load) are closely balanced. If load suddenly drops below generation, physical rotating generators like gas turbines can begin to speed up, making grid frequency rise.
This becomes particularly dangerous when large grid-connected loads all trip offline simultaneously because of minor frequency deviations or other factors. If these loads are large enough, they can trigger a cascading sequence of rising frequency and further equipment and generator trips, potentially causing a complete “grid collapse” blackout. The North American grid may be getting closer to this scenario.
What Triggered NERC’s Highest-Urgency Alert
Data center load drops are now a documented grid stability threat. On May 4, 2026, NERC issued a rare Level 3 “Essential Actions” Alert—its highest-urgency notification—in response to a pattern of customer-initiated load reductions in which 1,000+ MW of computational load (data centers) dropped off the bulk power system (tripped offline) in seconds. These were “customer-initiated” because protection circuits at data centers detected problems with grid-supplied power and automatically disconnected to protect their sensitive computing equipment from electrical damage.
Paired with a new Reliability Guideline on emerging large loads, the alert highlights the urgent need to better understand the potential for these events to cause grid instability or even blackouts. Together, these two documents reset the bar for the detailed grid modeling and planning needed for any utility, independent system operator (ISO), or hyperscaler with material data-center growth in its footprint.
Customer-Initiated Load Reductions
A customer-initiated load reduction (CILR) is an event in which a large load, most often a data center, AI training facility, or crypto miner, abruptly and without warning reduces or disconnects its electricity draw from the grid in response to a frequency or voltage disturbance that the grid’s internal protection circuits interpret as unsafe.
Compute-based loads like AI data centers are particularly sensitive to changes in the expected voltage and frequency from grid-supplied power, and their automated electrical protection systems tend to react more quickly and at smaller deviations than conventional industrial, commercial, and residential loads.
NERC has documented multiple events of 1,000+ MW since 2022, with reductions occurring in seconds, much faster than real-time operators can respond. This makes these events a significant risk to grid frequency stability that is distinct from more traditional load loss events that occur at a smaller scale or over slower timescales, allowing grid operators to take action to compensate.
How the Alert Reshapes Grid Interconnection
For utilities and ISOs, the alert and guideline raise the standard of evidence required to connect computational loads safely to the grid. Modeling assessments now sit on the critical path for large load interconnection decisions, and the same studies will increasingly inform reserve margin, transmission, and dispatch program designs.
For hyperscalers and other large loads, the consequence is direct. Plans that assume firm service without supporting analysis will face longer queues and tougher interconnection conditions. Buildout timelines now depend on whether utilities and ISOs can show, through stability and resource adequacy modeling, that the system can absorb the load and respond safely to its disturbances.
For storage developers, particularly long-duration and fast-responding assets, these events elevate the reliability value of rapid response and load-shifting resources. The same grid modeling improvements that capture flexible load behavior also surface storage's full reliability contribution.
For flexibility platforms, the same modeling work that satisfies NERC's expectations unlocks faster, cheaper interconnection. Demand response, large-load shifting, and co-located dispatch coordination are now both technical and commercial enablers.
A Higher Bar for Power Analysis
These pressures point to a higher bar for power analysis at multiple time and spatial scales, for utilities and the large loads they serve.
At sub-second to second timescales, electromagnetic transient (EMT) models capture fast electrical switching and the uninterruptible power supply behavior that determines whether a data center stays connected during a disturbance (“rides through”). The alert asks for these models to be more detailed, validated against actual equipment, and shared between large loads, transmission owners, and planners.
At seconds-to-minutes, dynamic stability simulation covers system frequency response, voltage recovery, and oscillation behavior after disturbances. NERC now expects annual stability studies and explicit load drop contingencies in planning files.
At hours-to-years, capacity expansion and production cost modeling determine whether the system has enough resources, in the right places, with the right flexibility, to keep up with computational load growth. NERC’s May 2026 Large Loads Reliability Guideline is most explicit at this scale, calling for resource adequacy studies that represent firm and flexible load components, behind-the-meter resources, AI training operating windows, and probabilistic scenarios across many weather, load, and outage combinations on a network-aware footprint.
Rising to the Challenge
Since the alert was issued, its expectations have begun hardening into rules. Registered entities were required to report to NERC on their progress against the seven Essential Actions by August 3, 2026, and on July 16, 2026, FERC directed NERC to go further: to develop mandatory reliability standards for computational loads and revise its registration criteria, with the first standards and Rules of Procedure changes due December 31, 2026 and a second-phase work plan due March 1, 2027. NERC's Large Loads Action Plan anticipates new "Computational Load Owner" and "Computational Load Operator" registered entity types alongside the first three computational load standards.
The practical consequence is that the modeling described above is no longer only good planning practice: utilities, ISOs, hyperscalers, and other large loads should expect the data-sharing, study, and commissioning expectations in the alert to return as auditable requirements, and should build the capability before the compliance deadline rather than after it.
Frequently Asked Questions
What is a NERC Level 3 Alert, and what does it require?
A Level 3 “Essential Actions” Alert is the most urgent of NERC's three alert levels, reserved for risks that need immediate, documented industry response. The May 4, 2026 alert directed registered entities to take seven essential actions on computational load—covering modeling, system studies, commissioning, protection, fault recording, and direct operational communication with large load operators. Written responses were due to NERC by August 3, 2026.
Why do data centers disconnect from the grid during minor disturbances?
Data centers run voltage- and frequency-sensitive computing equipment protected by automatic transfer systems that switch to on-site UPS or backup generation the moment grid power looks abnormal. Those protection settings trip faster, and at smaller deviations, than conventional industrial loads, so a fault lasting milliseconds can move a gigawatt of demand off the system in seconds. Because the shift is customer-initiated, grid operators get no warning and no time to rebalance.
How does the alert change interconnection for hyperscalers and other large loads?
Modeling assessments now sit on the critical path for large load interconnection. A plan that assumes firm service without stability and resource adequacy analysis behind it will face longer queues and tougher interconnection conditions, because the utility or ISO has to be able to show the system can absorb the load and respond safely to its disturbances. In practice, buildout timelines are now tied to someone else's study queue.
What modeling do utilities and large loads need to meet NERC's expectations?
Electromagnetic transient (EMT) models validated against actual equipment for sub-second ride-through behavior; dynamic stability simulation with explicit load-drop contingencies for seconds-to-minutes frequency and voltage response; and capacity expansion and probabilistic resource adequacy modeling that separates firm from flexible load, represents behind-the-meter resources, and reflects AI training operating windows. The paired Reliability Guideline is most explicit about the last of these.
Shifting Playbook for Corporate Power Procurement
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s proposed scope 2 revisions would shift many large power buyers from annual renewable energy certificate (REC) accounting to 24/7 hourly matching and reveal a larger emissions gap than most inventories currently report.
- Of all the US grid regions modeled, the emissions gap between annual and 24/7 hourly matching is widest in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the markets where data center load is growing fastest.
- Relae's modeling quantifies the shift from annual to 24/7 hourly matching: serving a 4-gigawatt (GW) data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM, a roughly 800-megawatt premium in PJM that translates directly into cost and siting strategy.
- Closing that gap requires investments in clean, firm generation technologies, like natural gas with carbon capture and storage (CCS), battery storage, and geothermal. The optimal mix varies by market and load profile, which means modeling current and future emissions positions under 24/7 accounting to understand the best procurement options for a specific portfolio.
Annual REC Accounting No Longer Holds at Data Center Scale
For years, large corporate energy buyers have relied on a straightforward approach: purchase renewable energy certificates (RECs) or sign virtual power purchase agreements (VPPAs) to offset market-based scope 2 emissions. Under the current GHG Protocol guidance, these instruments allow companies to claim low or zero emissions regardless of when or where clean energy is actually generated. When corporate clean energy demand was modest, this fueled new renewable project development while aggregate grid emissions were trending down.
That approach worked, until now. Energy demand from data centers and hyperscalers is surging. The Federal Energy Regulatory Commission (FERC) reported more than 50 GW of data center capacity operating in the US at the end of 2025, much of it concentrated in regions where local clean generation cannot keep pace. When corporate clean energy demand was modest, the gap between contractual claims and physical generation was small enough that few questioned this argument. At hyperscaler levels, with load concentrated in a handful of grids, that gap is becoming too large to ignore.
From a climate perspective, well-designed renewable procurement has created real impact by channeling corporate capital into new clean generation, and reducing CO2 emissions anywhere to benefit the climate everywhere. From a grid perspective, power consumption and generation must balance in real time, and the flow of electricity is constrained by the physics of the transmission system. Some regulators, investors, and standard-setters argue that corporate clean energy claims should be grounded in this second, engineering perspective rather than the first. The GHG Protocol's proposed revisions reflect that view, and would force buyers to defend their claims against it.
Relae’s modeling of this 24/7 framework in PJM and ERCOT helps quantify its costs and emissions implications in the markets where the stakes are highest.
What Does 24/7 Hourly Matching Mean for Scope 2 Accounting?
The biggest proposed change to the GHG Protocol’s current Scope 2 Guidance is the move from annual power reporting and matching to a 24/7 approach. Instead of calculating emissions with an annual emissions factor (EF) based on their independent system operator (ISO) or eGRID region for each megawatt-hour (MWh) consumed, companies would need to use hourly-specific EFs.
Companies would still be able to retire RECs to reduce their market-based emissions. However, companies would need to show that these RECs came from clean energy that was generated on the same grid, in the same hour as their facilities consumed power. This makes annual, location-agnostic REC retirement, currently the dominant practice, insufficient for 24/7 market-based accounting.
Both the time restriction (hourly matching) and the location restriction (generation on the same grid as consumption) will make it more difficult for companies to retire RECs. For example, because today's methodology is location-agnostic, a New York-based company can retire RECs from a Texas wind farm (purchased unbundled or via a VPPA) to reduce its reported market-based scope 2 value. This has allowed renewable development to follow the best resource sites rather than the load. Similarly, the time of day that the wind farm generates energy is irrelevant, as long as it is approximately in the same calendar year.
Under the proposed revisions, retiring these RECs would no longer be acceptable for the New York company, since they would fail both location- and hourly-matching requirements. As a result, companies with large REC portfolios today may no longer be able to retire them in order to reduce their market-based scope 2 emissions, if the proposed revisions take effect. These companies may face significant unmatched consumption under 24/7 accounting, especially during evening peaks or grid stress events when fossil-based generation fills the gap.
Annual Matching vs 24/7 Hourly Matching
The figure below illustrates the gap between what a representative large buyer reports under the current annual location- and market-based methodologies, versus what an hourly 24/7 analysis reveals.
Understanding this emissions gap is the essential first step for buyers to make informed decisions about which instruments to retain, which contracts to renegotiate, and where new investment will matter most. If the proposed scope 2 revisions are enacted, companies procuring clean energy will be disincentivized from buying RECs sourced from variable renewables in distant locations, and instead will find it more favorable to invest in same-grid clean, firm generation, such as geothermal, nuclear, and renewables plus storage. RECs from these projects would qualify to be retired against market-based scope 2 emissions under the proposed revisions, where today's distant-wind or off-peak-solar RECs would not.
Where Pressure Is the Highest: ERCOT and PJM
Two markets stand out for projected hyperscaler load growth: PJM, which covers the extended mid-Atlantic region, and ERCOT in Texas. Both are on track to absorb massive increases in data center demand over the next decade, and both expose the limits of annual REC accounting in ways that will be hard to ignore under the new proposed framework.
PJM: 60% Fossil Generation Means High Marginal Emissions
PJM is one of the largest and most complex wholesale electricity markets in the world. Its generation mix still includes 60% coal and natural gas, which means hourly emissions intensity remains high, particularly during evening peaks and grid stress events when fossil generation dominates the dispatch stack.
Buyers relying solely on annual REC retirement may show low market-based scope 2 emissions today, but a 24/7 analysis tells a different story. For PJM-based buyers, this means hourly matching gaps will be largest during evening and overnight hours, when nuclear and storage become disproportionately valuable relative to additional solar.
ERCOT: Solar and Wind Don’t Peak When Demand Does
Texas has abundant wind and solar, with solar generation growing nearly 7x since 2020, but those resources don’t always run when demand peaks. While fossil-based generation has declined since 2020, it still comprises more than half of ERCOT’s generation. Solar dominates midday, wind peaks in the evening, and natural gas fills the gaps, especially during high-demand evenings or extreme weather events.
Buyers with large ERCOT footprints may find that VPPA portfolios, which generate most of their clean energy in off-peak hours, already satisfy the proposed location-based test but fail on hourly matching. Battery storage and demand flexibility could help bridge the gap.
Figure 3 below quantifies that gap in both markets by showcasing the carbon-free energy (CFE) score in ERCOT and PJM, as well as the additional capacity required for a 4 GW load to achieve a 100% CFE target. The CFE score is the share of grid-supplied electricity in a given hour that comes from carbon-free sources, and is the metric the proposed scope 2 revisions would use to evaluate hourly matching. A 100% CFE target means electricity consumption is matched to carbon-free generation in every hour of the year.
In the left panel, a representation1 of each market's 2030 hours are sorted by grid (CFE) score, from the dirtiest hour on the left to the cleanest on the right. Neither grid approaches 100% carbon-free on its own, and the shaded areas represent the unmatched hours a buyer claiming 100% clean energy through annual instruments would actually carry under 24/7 accounting. The gap is the maximum unmatched hours a buyer might be exposed to, as some RECs procured through annual matching may qualify under the new rules, if satisfying the locational and hourly requirements.
The right panel translates that gap into action. The additional co-located clean generation and storage required to serve a representative 4 GW load (roughly 5% of the forecast 2030 C&I load in ERCOT and 4% in PJM) at a 100% hourly CFE target, on top of what the underlying grid already provides.
A few patterns are worth highlighting. First, the left panel confirms that PJM’s grid will still spend materially more hours below 100% carbon-free than ERCOT’s in 2030, a direct consequence of the coal- and gas-heavy generation mix described above. Notably, ERCOT's curve reaches 100% in a meaningful share of hours (windows when the grid is running entirely on carbon-free resources), while PJM's never does, meaning some fossil generation is dispatched in every hour.
Second, the ISO a buyer operates in drives a meaningful difference in build-out: hitting 100% hourly CFE for a 4 GW load takes 9.6 GW of additional capacity in ERCOT and closer to 10.5 GW in PJM. This indicates the advantage of achieving hourly and locational matching in already clean grids, which may influence a buyer choosing where to site new workloads.
Renewables have the largest share of the additional capacity in both markets (5-6 GW), paired with significant long-duration energy storage (~2 GW), while natural gas with CCS provides meaningful clean, firm capacity (~3 GW). ERCOT’s storage share of capacity is slightly larger, reflecting the midday-solar/evening-load mismatch, while PJM leans a bit more on natural gas with CCS, where clean, firm generation does more of the heavy lifting due to lower wind speeds and solar irradiance than Texas.
The right panel also illustrates why clean, firm technologies (natural gas with CCS, advanced nuclear, and enhanced geothermal) are likely to be included alongside renewables and batteries in any serious 24/7 portfolio. With only renewables and batteries, hitting the same target requires about double the total generation and storage capacity. In both markets, targets that look achievable today on an annual REC basis will require materially more capital and a different mix of resources, under 24/7 accounting.
Top Questions Large Power Buyers Need to Model Before the Rules Change
The GHG Protocol revisions are not finalized, and the timing of any mandate remains uncertain, which is exactly why modeling cannot wait.
A useful self-test for any large power buyer is: can your team answer the following today with defensible numbers?
- What is your hourly CFE score across your largest load centers, and how far does it sit from your reported market-based emissions?
- Which of your existing VPPAs and REC contracts hold value under 24/7 accounting, and which become effectively stranded?
- What mix of resources delivers the incremental clean, firm capacity that closes your gap in PJM, ERCOT, or wherever your load is concentrated at the lowest cost?
- If your next gigawatt of load were sited in a different ISO, how would your emissions position change?
Clean firm projects do not appear off the shelf. Advanced nuclear, enhanced geothermal, and natural gas with CCS all carry multi-year development timelines, and corporate offtake agreements are often what get these projects financed in the first place. Buyers who engage now help shape the project pipeline that will be available in their target markets in 2030, and can lock in offtake terms before competition for the most valuable sites tightens. Buyers who wait until the methodology is final will be working with shorter lead times, fewer development partners, and less leverage to specify projects that fit their load profiles and hourly matching needs.
Frequently Asked Questions
What is 24/7 hourly matching, and how does it differ from today's REC accounting?
Today's scope 2 accounting lets companies retire renewable energy certificates (RECs) from any grid, at any time of year, to offset their emissions. The GHG Protocol's proposed 24/7 hourly matching would require RECs to come from clean generation on the same grid, in the same hour a facility consumes power, making most of today's location-agnostic RECs ineligible for market-based accounting.
Why are PJM and ERCOT under the most pressure from this shift?
Both markets are absorbing the fastest-growing data center load in the country, and both still lean on fossil generation to meet demand outside peak renewable hours. PJM's generation mix is 60% coal and gas, while ERCOT's solar and wind often don't peak when demand does, so buyers in these markets face the largest gaps between their annual REC claims and their actual hourly carbon-free energy score.
How much additional clean capacity does it take to close the gap?
Relae's modeling finds that serving a 4 GW data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM. That capacity mix leans on renewables and long-duration storage in both markets, with natural gas with CCS playing a larger role in PJM, where wind and solar resources are weaker.
What should power buyers do before the GHG Protocol revisions are finalized?
Start modeling now. Buyers should know their hourly carbon-free energy score, understand which existing VPPAs and REC contracts hold value under 24/7 accounting, and identify the lowest-cost mix of clean, firm resources that closes their gap. Clean firm projects like advanced nuclear, enhanced geothermal, and natural gas with CCS take years to develop, so buyers who engage early have more influence over the project pipeline and better offtake terms.
Modeling the 24/7 Emissions Gap with Relae
For large power buyers assessing what the proposed GHG Protocol revisions mean for their power procurement portfolio, Relae's Advanced Power Emissions Analysis solution models the gap between current market-based reporting and what 24/7 accounting would reveal—by market, load profile, and technology stack.
Reconciliation Bill Dramatically Shifts the Clean Energy Landscape
Key Takeaways
- Accelerated phase-out schedules for key clean energy and decarbonization tax credits will shorten the runway for project development, which could stall or cancel projects.
- Urgency is paramount, and qualified projects should expedite construction and operational timelines to secure eligibility for existing credits.
- A more complicated policy landscape requires concerted effort to navigate, including with the support of policy professionals.
Reconciliation Rolls Back Much of the IRA
On Friday, July 4, 2025, the President signed a sweeping reconciliation bill, H.R. 1, that will add at least $3.3 trillion to the national debt and marks a pivotal, contentious moment for US clean energy policy. The law was enacted through the complex legislative process known as budget reconciliation, requiring only a simple majority of votes in the House and Senate. The new law substantially modifies or terminates many of the Inflation Reduction Act of 2022 (IRA)'s clean energy incentives and has extensive implications for the economic viability of American energy and manufacturing projects.
In the Senate, three Republicans crossed party lines to vote against the bill, requiring Vice President JD Vance to break the tie. In the House, only two Republicans broke ranks to vote against final passage. While some of the more complex provisions of the bill, such as new foreign entity of concern (FEOC) restrictions, will require more time to fully assess, we've prepared a rapid run-down of key alterations to IRA incentives for carbon management, hydrogen, and clean fuel technologies.
What Is the 2025 Reconciliation Bill?
While the 2025 reconciliation bill is staggering in length, scope, and severity, containing provisions to cut Medicaid, reduce nutrition assistance, raise the debt limit, and cut taxes primarily for the wealthy, some of the most drastic sections of the bill modify tax incentives and other public funding for clean energy and emissions reductions.
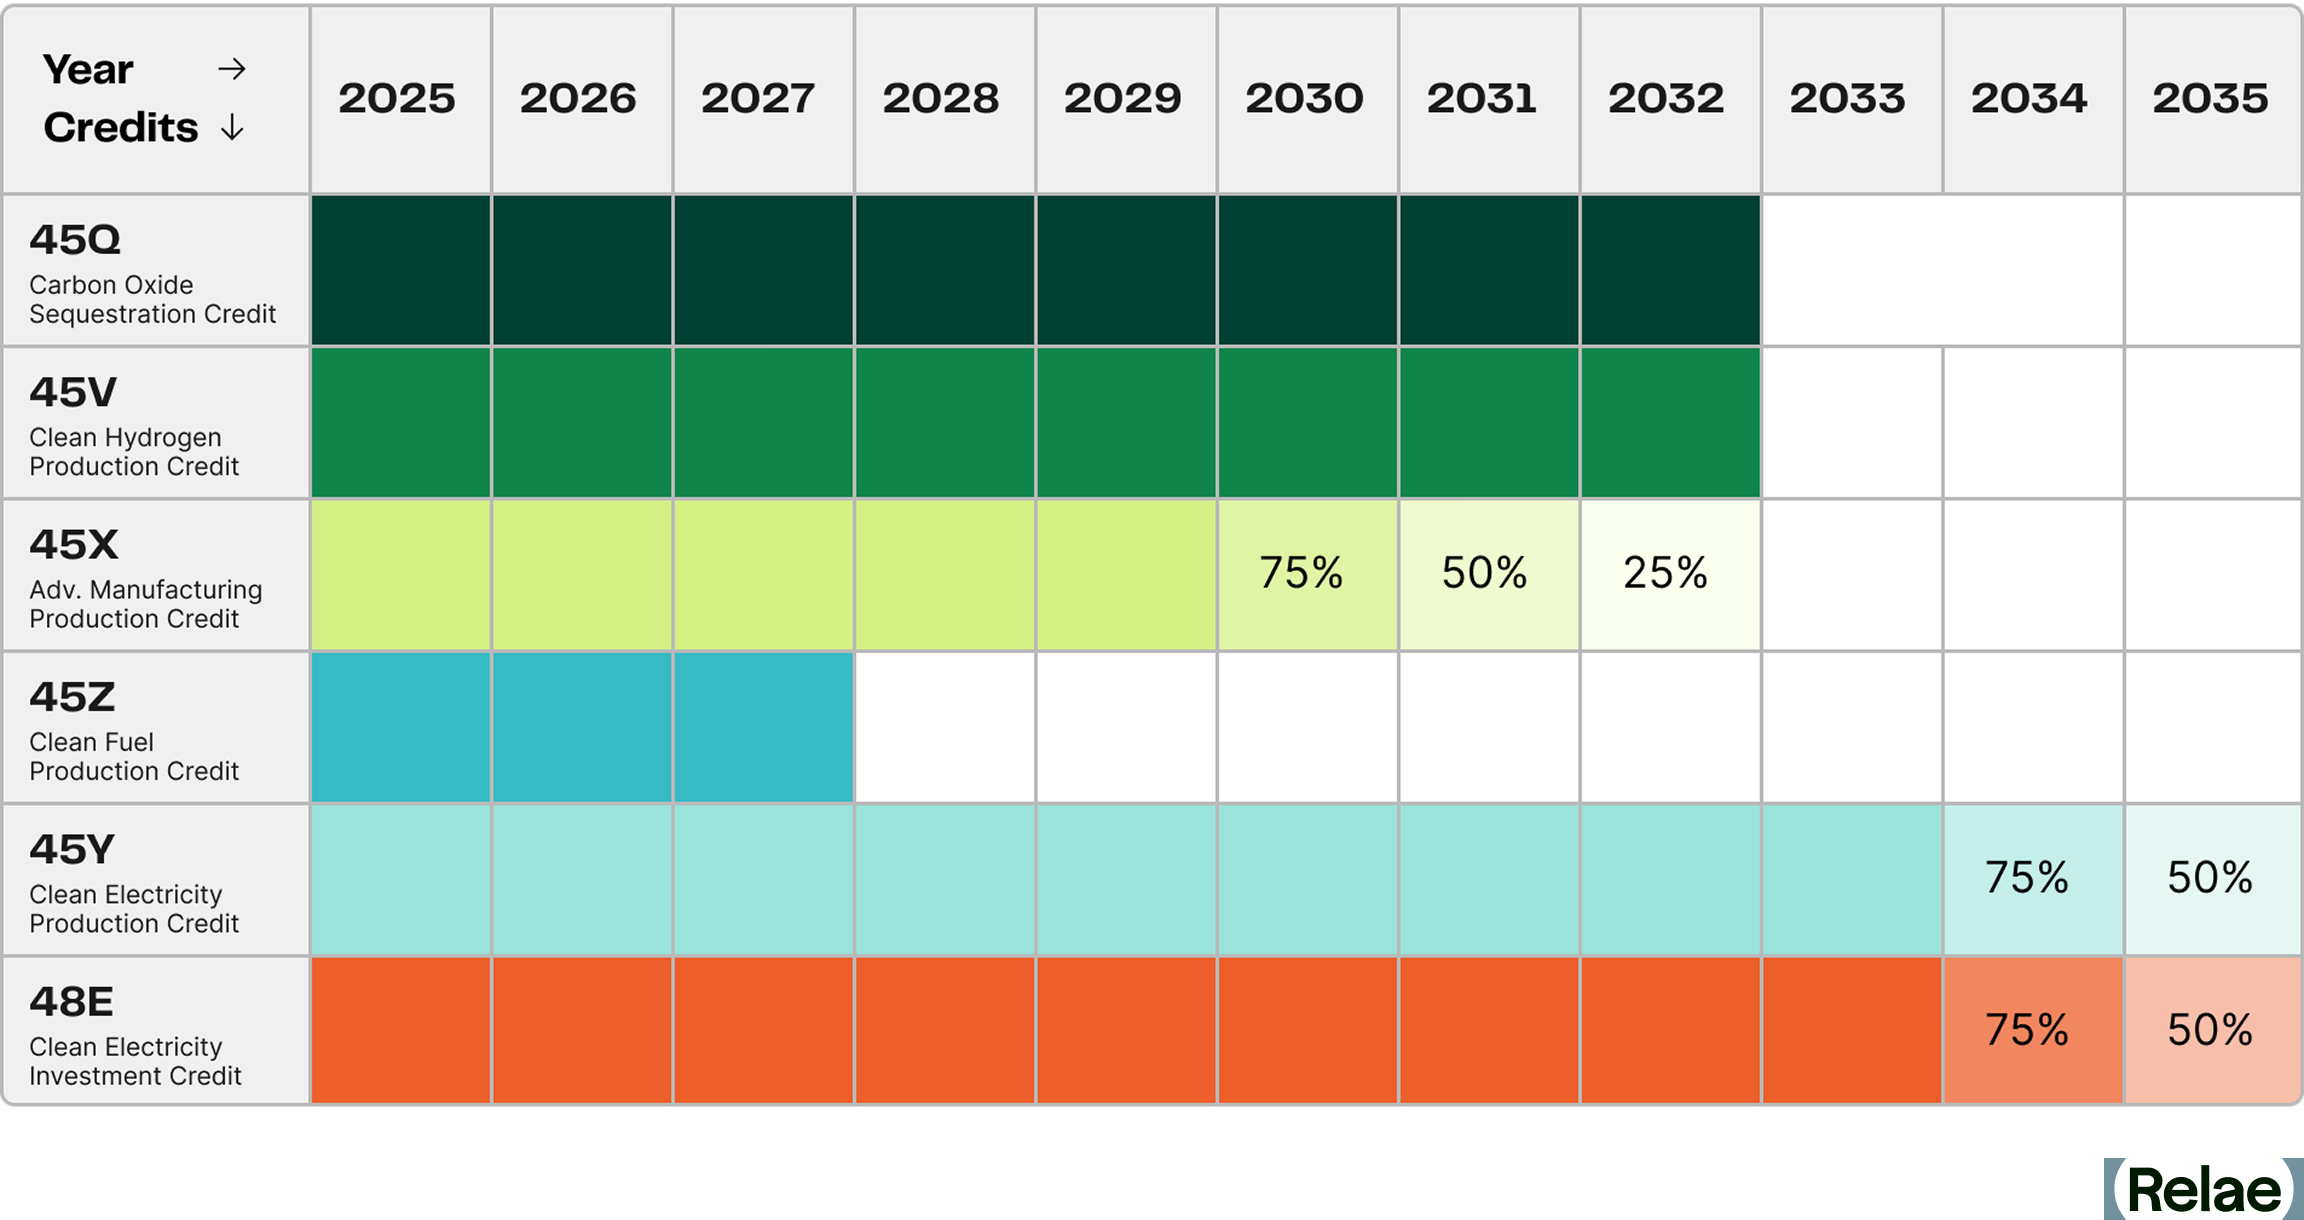
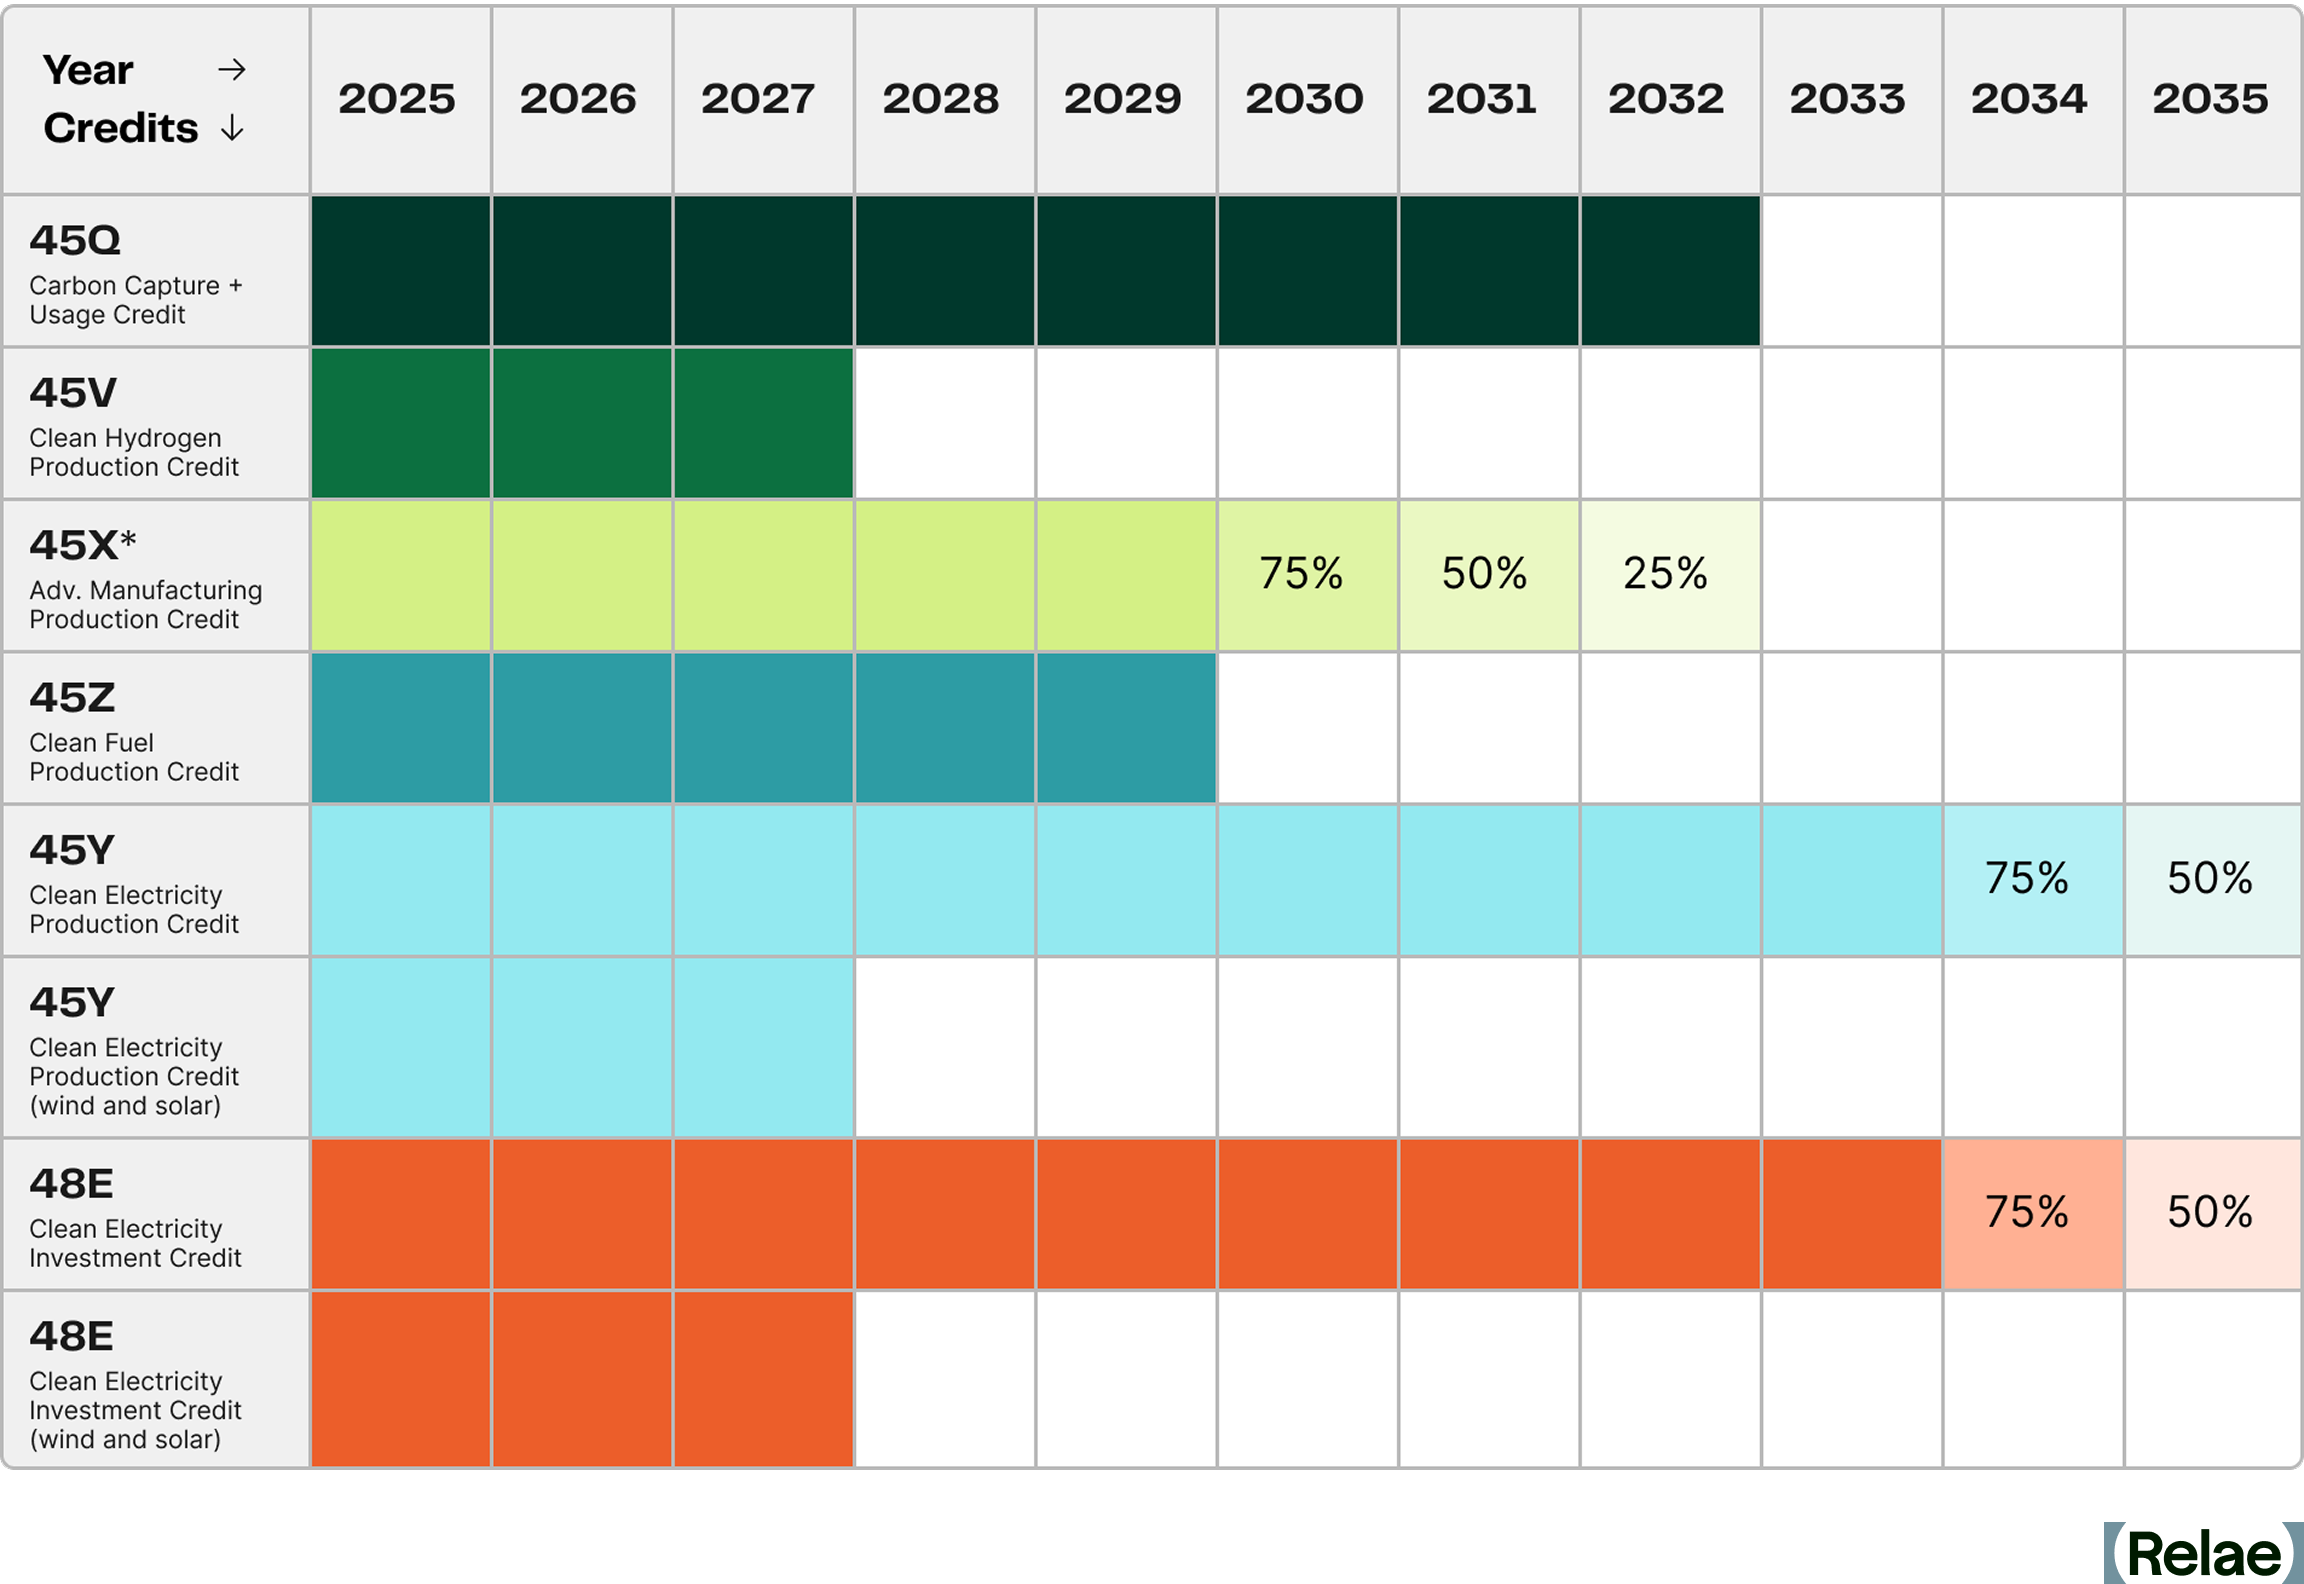
Many of the incentives to deploy clean energy that were created or enhanced under the IRA will be phased out early or repealed altogether. Credits with accelerated phase-out schedules include the newly created 45Y clean electricity production tax credit, which will no longer support wind or solar projects after 2027, and the 45V credit for clean hydrogen production for which projects must now commence construction before Jan 1, 2028 (moved up from Jan 1, 2033).
Since the passage of the reconciliation package, there has been active litigation on several provisions, including an order from a federal district court to vacate IRS guidance that would have prohibited certain wind and solar projects from securing safe harbor. The table below provides a detailed breakdown of key changes to major tax credits between the original IRA, the draft that moved through Committees in the House, and the final text that was passed by the Senate and signed into law.
Major Tax Credit Changes in the Reconciliation Law
How FEOC Restrictions Threaten Clean Energy Supply Chains
Many clean energy tax credits include ambiguous language restricting projects connected to FEOC, complicating supply chains and creating new problems for developers of clean energy projects. The law also introduces a complex matrix of new definitions, such as "Prohibited Foreign Entities," which includes both "Specified Foreign Entities" and "Foreign-Influenced Entities."
The FEOC restrictions embedded in the reconciliation bill represent a seismic shift for clean energy developers. These new rules, designed to limit the influence of Covered Nations (China, Russia, North Korea, and Iran), will disqualify projects from receiving tax credits if they source components, minerals, or intellectual property from entities tied to these nations. In other instances, the partial ownership or investment of an entity with financial ties to a Prohibited Foreign Entity may also disqualify a project from qualifying for tax credits.
This FEOC language matters for developers and investors because of the resulting global supply chain disruptions, investment uncertainty, and compliance burdens. The clean energy sector is deeply reliant on global supply chains, especially for solar panels, batteries, and wind components, industries where China currently dominates. The IRA intended to counter this by moving the manufacturing and production of these supply chains to the US. Project developers must now thoroughly review their supply chains and capital providers, and may need to quickly pivot to compliant resources.
In February 2026, the IRS released interim guidance on the FEOC provisions to provide safe harbor guidance for clean energy manufacturing, investment, and production credits to help taxpayers gauge whether material assistance was provided by a prohibited foreign entity.
Other Major Rollbacks to the IRA
Beyond clean energy tax credits, the reconciliation package also repeals and rescinds many other IRA provisions. This includes a full rescission of all unobligated IRA appropriated balances at the Department of Energy's Loan Programs Office, and several other programs, including:
- The Tribal Energy Loan Guarantee Program
- Greenhouse Gas Reduction Fund
- Transmission Facility Financing
A complete list of rescissions of energy-related funding is outlined in Sections 60001-60024 and 50402 of the law. These rescissions represent tens of billions of dollars in lost climate investments made under the IRA, which would have provided funds to state, local, and Tribal governments, federal agencies, non-profits, and commercial project developers to reduce emissions and update critical infrastructure.
What Can Project Developers and Other Companies Do?
Developers will need to act quickly to meet updated commence construction and place into service requirements, though circumstances are technology specific (e.g., safe harbor updates to 48E and 45Y). Tax credits generally have advanced commence construction and operational deadlines, resulting in a strong first-movers advantage. Companies should also review their supply chains and revise equipment and material procurement sourcing plans as necessary to address restrictions presented in the reconciliation bill.
An executive order from President Donald Trump issued on July 7 will further complicate how companies proceed. In the EO, the President directs his administration to "strictly enforce the termination of […] 45Y and 48E […] for wind and solar facilities." The Administration will likely issue extremely strict interpretations of "commence construction" clauses and FEOC requirements in forthcoming tax credit guidance issued by the Treasury Department, though these moves are quite likely to face litigation.
The new restrictions being proposed by the Administration, including specific details on FEOC, qualified equipment, commence construction, and other reporting requirements, will require additional guidance from the IRS and provide an opportunity for engagement through public comment. It is important that impacted companies weigh in during these public comment periods, not only to help inform and influence the final rules issued by the Administration, but also to build an administrative record that could support litigation efforts to strike down the final rules.
Staying Ahead of Policy Changes
Given the rapidly shifting landscape of energy policy, it's paramount that companies stay abreast of the latest changes and dedicate resources to understanding how they may be affected. Policy professionals, including the experts at Relae (formerly Carbon Direct), can support organizations as they engage in the regulatory process, anticipate and prepare for new legislation, and navigate the requirements to access essential tax credits and incentives. Even under new constraints, expert guidance can help maximize impact and minimize disruption.
Frequently Asked Questions
How does the reconciliation bill change the timelines for major clean energy tax credits?
Most clean energy tax credits saw their windows shortened relative to the original IRA:
- The 45Y and 48E credits now terminate entirely for wind and solar facilities placed in service after December 31, 2027, with a separate phase-down (75% in 2034, 50% in 2035, 0% after) for other technologies.
- The 45V clean hydrogen credit's "commence construction" deadline moved from December 31, 2032 to December 31, 2027.
- The 45Z clean fuel credit now ends on December 31, 2029 (versus 2027 in the original IRA, but bonuses for SAF have been removed and new emissions-calculation methods favor corn ethanol).
- Notably, the 45Q carbon capture credit saw little change and retained transferability, with credit values for enhanced oil recovery and utilization raised to match secure geological storage.
What are the FEOC restrictions, and why do they matter so much for developers?
FEOC ("Foreign Entity of Concern") restrictions disqualify projects from tax credits if they source components, minerals, or intellectual property from entities tied to China, Russia, North Korea, or Iran. Even partial ownership or investment ties to a "Prohibited Foreign Entity" can trigger disqualification. The definitions are complex and still being clarified through IRS guidance, meaning developers need to review supply chains and capital providers carefully and may need to pivot to compliant sourcing.
What should project developers do now in response to these changes?
Developers should move quickly to meet the earlier "commence construction" and "placed in service" deadlines, since credits now benefit early actors. This includes reviewing and potentially restructuring supply chains and procurement plans to address FEOC restrictions, and closely monitoring forthcoming IRS/Treasury guidance.
How to Fix Load Forecasting for the AI Era
Key Takeaways
- Accurate load forecasting is needed to distinguish and prioritize real demand, align capital deployment, and reduce delays in bringing new power capacity online. Traditional load forecasting was built for predictable, gradual demand growth, not for the scale, uncertainty, and dynamic behavior of data centers.
- The system-level fix to data-center load forecasting requires probabilistic, more frequent, category-specific methods paired with mandatory data standards and policy alignment. Together, these give planners visibility into the range of possible futures and the likelihood of each.
- Without that fix, today's forecasts conflate real demand with speculative submissions, reducing accuracy. Inaccurate forecasting in either direction is expensive: underbuild adds friction to economic development; overbuild risks raising retail rates. Both can erode public trust in planning.
- Behind-the-meter generation (BTM) and load flexibility can help achieve speed-to-power in the near term. Just 1% data-center flexibility could unlock 100 GW—more than the entire US nuclear fleet.
Load Growth Is Increasing, Uncertain, and Concentrated
For two decades, US electricity demand was flat. Utilities, transmission planners, and corporate buyers built their planning models around that reality. Then AI workloads changed it.
AI load growth is large, uncertain, and concentrated in major power markets. While load forecasting projections vary across studies, the trajectory is clear: electricity demand is scaling faster than the bulk power grid was designed to handle. Accurate load forecasting is needed to distinguish and prioritize real demand, align capital deployment, and reduce delays in bringing new power capacity online.
On April 30, 2026, Relae (formerly Carbon Direct) hosted a Trellis Group panel on load forecasting in the AI era. Panelists included Derya Eryilmaz, PhD, Vice President of Power Commercialization at Relae; John Miller, Director of Transmission Policy at the Corporate Energy Buyers Association (CEBA); Daniel Padilla, Strategy and Business Development Lead at Emerald AI; and Sam Hodas, Head of US Government Affairs at National Grid. Jake Mitchell, Director of Climate Tech Innovation at Trellis Group, moderated.
The conversation explored where load forecasts fail, what they cost, how to fix them, and near-term solutions to overcome grid constraints. Here is what the panel found.
What Is Load Forecasting?
Load forecasting is the practice of predicting how much electricity will be consumed across a region, at what times, and under what conditions. It informs the major capital and procurement decisions on the grid: where to build transmission, how much generation to procure, what capacity to bid into wholesale markets, and how corporate buyers secure clean, firm power.
Long-term forecasts inform multi-year decisions about transmission and generation. Short-term operational forecasts inform real-time grid operations and trading. The two often sit in separate workflows, but short-term operational forecasts should feed into long-term system planning to improve accuracy as demand patterns shift.
The Bulk Power Grid Is Under Strain
Large power users face constraints on clean, firm power, transmission capacity, multi-year interconnection queues, and aging infrastructure. The strain is most acute in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the two US markets expected to see the most significant load growth. Each constraint raises the cost of getting load forecasts wrong.
Hodas from National Grid describes the operational reality on the utility side: aging infrastructure inherited from a different demand era. “We’ve got transmission lines that are 70 to 100 years old in New York and Massachusetts, some of the oldest in the country, still in operation.” Replacing or upgrading that infrastructure requires investment, and ratepayers are already pressed.
Why Today’s Load Forecasts Fail
Traditional load forecasting was built for predictable, gradual demand growth, not for the scale, uncertainty, and dynamic behavior of data centers.
Most utilities and Independent System Operators (ISOs) produce load forecasts on annual or biannual cycles. They aggregate submissions from individual customers, run that data through a deterministic single-peak load estimate against a single capacity scenario, and pass the consolidated forecast up to regional planners. Regional Transmission Organizations (RTOs) roll those bottom-up utility forecasts into a regional view.
This worked when demand was flat and predictable. It no longer works with nonlinear growth driven by data centers. Eryilmaz from Relae identifies key structural limitations.
Four Structural Limitations to Traditional Forecasting Methods
- Over-stating and double-counting. Data centers bid into multiple regions while shopping for power, inflating regional forecasts and blurring the line between real and hypothetical demand—the speculative-load problem.
- Deterministic models (vs probabilistic models). Most planning runs a single peak load estimate against a single capacity scenario, missing the geographic concentration and uncertainty inherent in integrating large loads into the system.
- Aggregated submissions. Utilities report large loads as a single block of gigawatts, with no resolution into workload type, ramp schedule, or operational shape. Planners reverse-engineer peak-demand assumptions rather than measure them.
- Infrequent cadence. Annual or biannual forecasts cannot catch an 80% queue reduction or a multi-gigawatt addition between cycles.
The Speculative-Load Problem
The core challenge in load forecasting is distinguishing real versus hypothetical load. While data center electricity demand is projected to grow by 13-27% annually through 2028, the majority of the projects in the data center queue may not materialize, inflating regional load forecasts.
American Electric Power's Ohio utility (AEP Ohio) introduced a tariff requiring data centers to put up firm financial commitments before getting in line for grid connection. Its interconnection queue dropped from 30 gigawatts to 5.6 gigawatts. More than 80% of the submitted load was speculative: projects that disappeared once commitment became required.
ERCOT shows the same overstatement problem on a larger scale. Roughly 225 gigawatts of data center demand sits in the ERCOT queue against a historic system peak of 85 gigawatts. Texas Senate Bill 6 introduced similar financial obligations for new loads, but those rules apply only to interconnections after 2025, and the cleanup of speculative demand has not yet materialized.
The speculative-load problem shows up in interconnection times. An average new project in PJM can wait 4 to 5 years to become operational. Some of that delay is a real backlog. The rest comes from the inability to distinguish real submissions from speculative ones.
As Eryilmaz puts it, “Load forecasting is actually the center of all of these problems. It is a tool to help planners make the right investment decisions.”
The Cost of Inaccurate Forecasting
As Miller from CEBA notes, “A single misforecasted project can swing a transmission plan by hundreds of megawatts.” Significant inaccuracies can erode public trust in the planning process in two main ways. Underbuilding adds friction to economic development and can limit corporate access to clean power markets. Conversely, overbuilding risks raising retail rates if capacity remains underutilized.
The goal is to achieve right-sized infrastructure investment. When planning aligns with actual large load growth, it can be net beneficial to retail rates. By spreading fixed costs across more usage, significant new demand can put downward pressure on the rates via the “denominator effect.”
On the other hand, forecasting variability can distort capacity procurement and interconnection queue prioritization. When load forecasts spike upward, grid operators like PJM have to scramble to buy additional electricity capacity on short notice. These emergency procurements lock in major dollar commitments on the basis of unstable forecast numbers.
PJM, Midcontinent Independent System Operator (MISO), and Southwest Power Pool (SPP) have also reshaped their interconnection queues to make room for new large loads, but those queue priorities depend on the same forecasts that are unreliable in the first place.
“There is no substitute for good backbone regional transmission planning,” Miller says. “Full stop. That is the enabler of all of the load growth that we’re talking about.”
BTM Generation and Load Flexibility: A Near-Term Bridge
Hyperscalers’ need for power is way faster than that of utilities and RTOs. Generation alone cannot scale fast enough to meet this new demand, and hyperscalers need speed-to-power.
As Eryilmaz frames it, behind-the-meter generation and load flexibility are interim solutions to the timing mismatch between data center urgency and the grid's slower build cycles. BTM generation and flexibility work differently:
- BTM is power generated on the data center's side of the utility meter, bypassing grid interconnection entirely. The structure gives operators large, reliable blocks of power without waiting years for grid approval.
- Load flexibility is the demand-side approach. A data center modifies its grid draw in response to grid signals. In practice, that can mean curtailing compute workloads during stress events, pre-cooling facilities ahead of a heat wave, drawing from on-site batteries or generators, or shifting workloads to data centers in less-constrained regions.
The Value of Load Flexibility
Relae’s power system modeling quantifies the dollar value of load flexibility in ERCOT. Load flexibility can eliminate forced load shedding risk, even at 40 gigawatts of data center buildout, preventing $5.5 billion in annual consumer welfare losses by curtailing an average of 5% of demand for under 1% of operating hours.
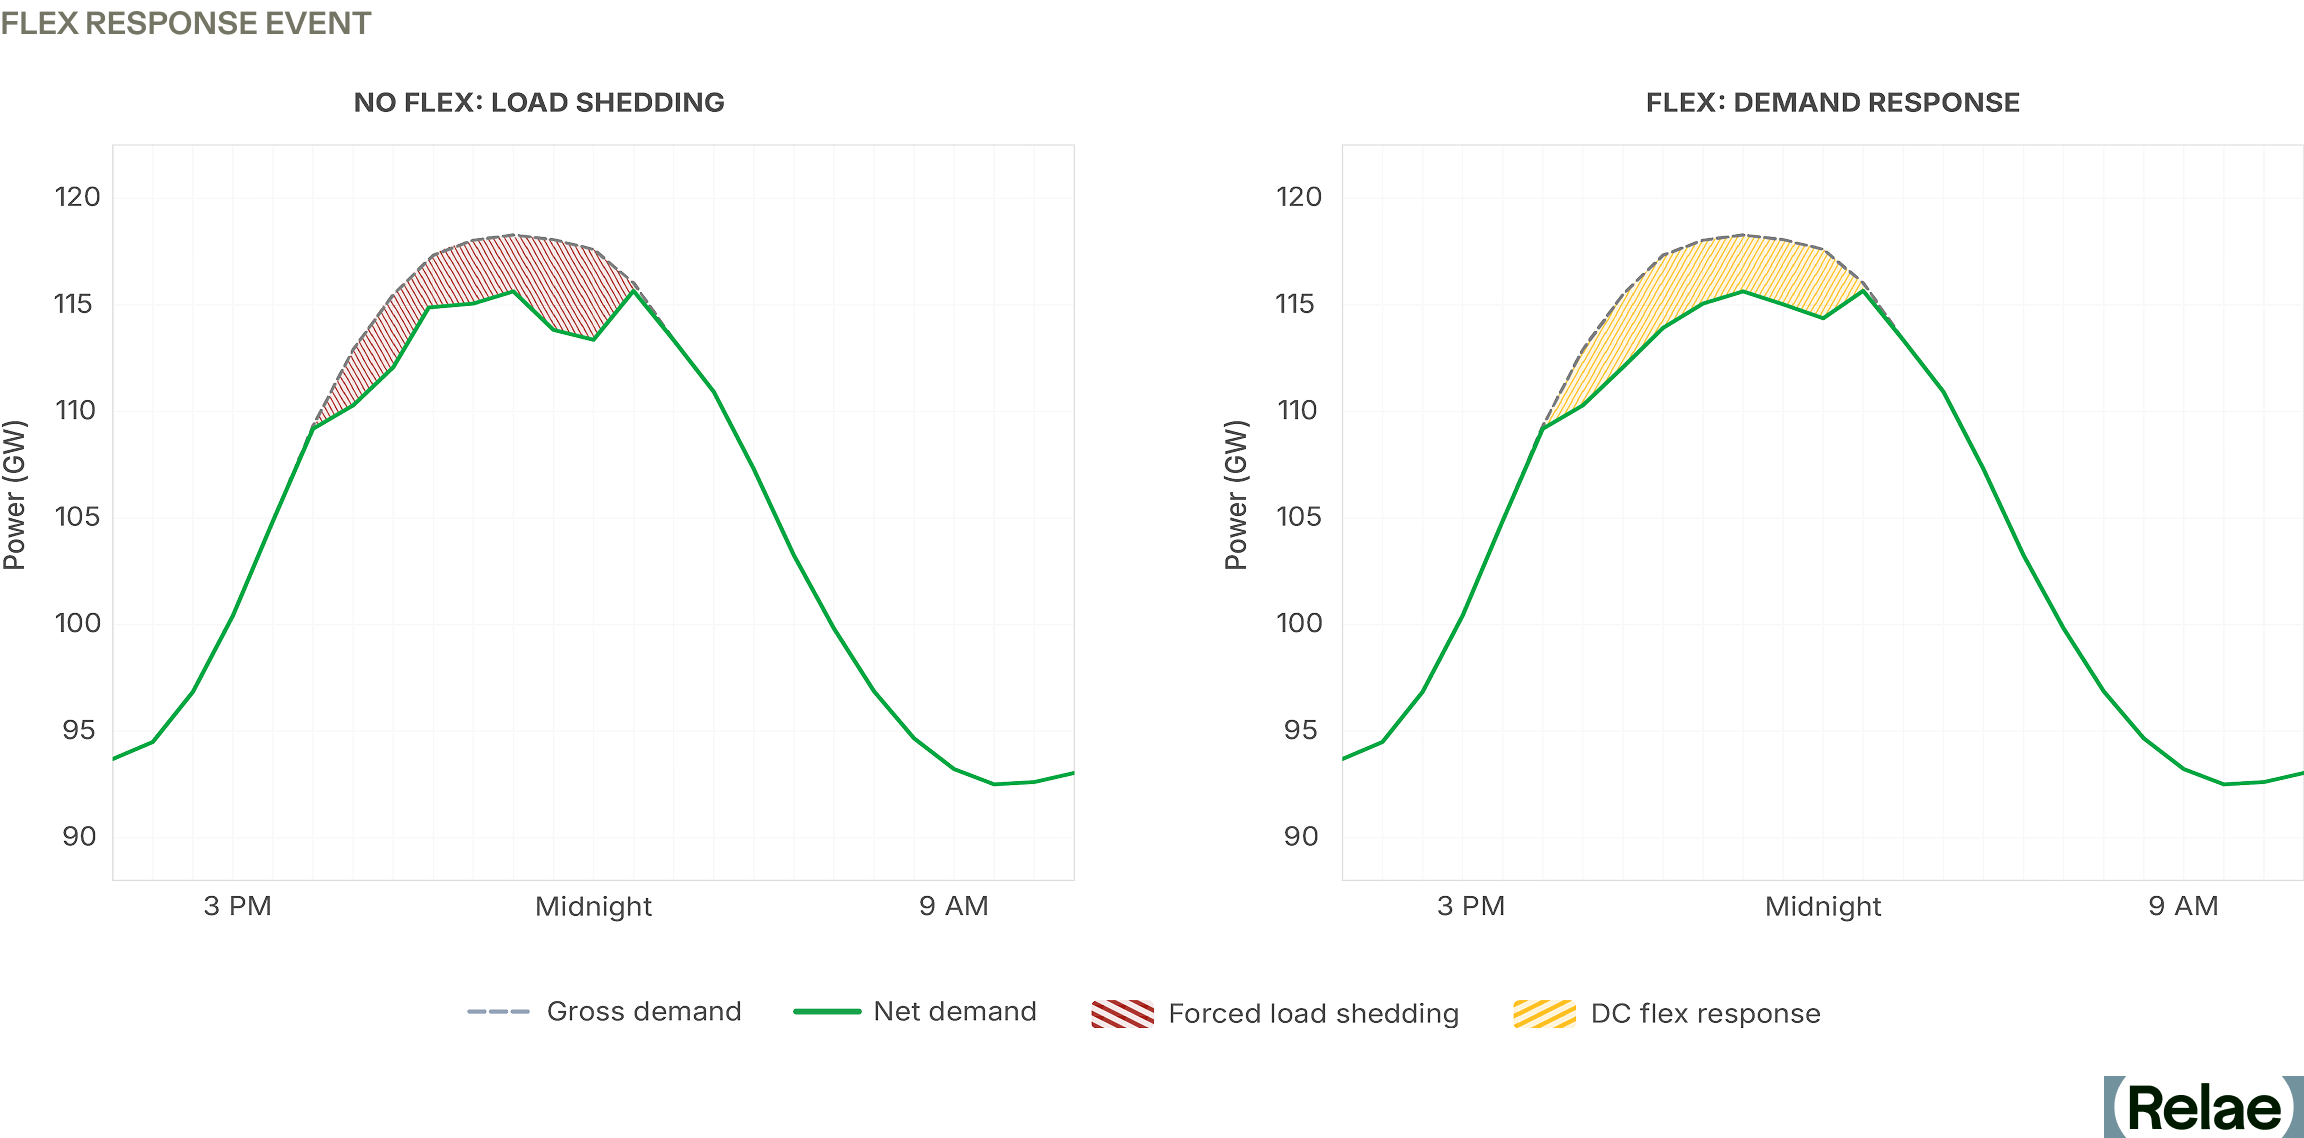
Padilla from Emerald AI reinforces the scale and value of load flexibility: “With just 1% flexibility, we can unlock 100 gigawatts of data centers across the US. That’s more than the entire US nuclear fleet.”
Silicon Valley Power, a municipal utility, is the first US utility to tie flexibility to interconnection speed: flexible data centers get connected faster. NVIDIA, EPRI, Digital Realty, and PJM are partnering on the Aurora AI Factory, the first purpose-built reference design for flexible AI data centers.
But standardized policy for load flexibility is lagging. Padilla highlights this challenge: “Today, if a data center wants to be flexible, they have nowhere to point. We need standardized tariffs, interconnection rules, and product definitions for large loads that reward them with upsizing interconnection in response to flexibility.”
Flexibility Takes Many Forms, but it Isn't Universal
Flexibility means accepting brief, predictable downtime, and some workloads can't tolerate it. Hospital systems and mission-critical enterprise applications need 99.999% uptime, the "five nines" standard. As Padilla puts it: "99.9% uptime, with brief and predictable curtailments, is plenty" for most AI workloads. That distinction determines which data centers can participate in flexibility programs.
Miller points out that compute-level flexibility is not always feasible. BTM batteries and virtual power plants (VPPs) are among the alternatives that can offset what data centers withdraw when the grid is stressed, even at facilities whose compute workloads cannot pause directly.
Better Load Forecasting: The Longer-Term Fix
While BTM generation and load flexibility can help address near-term speed-to-power, the longer-term fix is improving load forecasting methods and the standardization of data provided by the data centers themselves.
Eryilmaz outlines three technical shifts for better load forecasting:
- Embed short-term operational forecasting into long-term planning. Short-term spikes, weather risk, and reserve considerations carry direct implications for multi-year capital decisions. The line between operations and planning breaks down when growth is nonlinear.
- Replace deterministic models with probabilistic methods. Risk metrics like loss of load hours (expected hours per year that demand exceeds supply) and expected unserved energy (total expected energy shortfall) measure both how much capacity the system has and the conditions under which it might fall short. The North American Electric Reliability Corporation (NERC) has suggested both metrics as part of its reliability framework.
- Forecast load by category. Treating all data center load as a single block hides the differences in load profiles, operational schedules, and ramp-up timing that drive system planning.
Policy Alignment
Technical forecasting improvements only scale with policy alignment, and Miller proposes a two-part fix:
On the top-down side, RTOs need authority to take an independent view of utility-submitted forecasts. They should require milestones, such as firm financial commitments and secured financing, before counting a submitted load against the regional forecast.
On the bottom-up side, state regulators set the rules that govern how individual utilities prepare their forecasts. Large load tariffs play a big role in how utility-level forecasts come together. Federal and state authorities need to row in the same direction. Hodas frames the same alignment from the utility side: “Grid investment unlocks economic growth, but for us to make those investments, we need regulatory certainty.”
Standardizing Large-Load Data
The Federal Energy Regulatory Commission (FERC) has since moved: in June 2026 it issued show cause orders directing six RTOs and ISOs—CAISO, ISO-NE, MISO, NYISO, PJM, and SPP—to revise or justify their large-load interconnection rules, and in July 2026 it directed NERC to develop computational-load reliability standards and registration criteria by the end of the year. Both are useful first steps. But as Eryilmaz argues, voluntary disclosure has not closed the gap.
The industry cannot meaningfully compare ISO forecasts when each utility submits load data in different shapes (e.g., using different methods and data standards) on different schedules. Mandatory submission requirements and published methodologies, applied consistently across utilities, ISOs, and state regulators, are the only path to forecasts whose components are actually comparable.
Getting Load Forecasting Right Starts Now
The system-level fix to improving forecasting is through probabilistic, category-specific methods paired with data standardization and policy support. Together, these account for the scale, uncertainty, and dynamic behavior of data center loads, and give planners visibility into the range of possible futures and the likelihood of each.
All forecasts will be wrong to some degree, but as Miller puts it, “It's ultimately not about having a perfect prediction. It's about baking in methods to account for uncertainty.” These system-level improvements won't eliminate errors entirely, but they will minimize them, leading to more confident investment decisions and a grid better prepared for what's ahead.
Frequently Asked Questions
What is load forecasting, and why is it harder now with AI data center loads?
Load forecasting predicts how much electricity a region will consume, when, and under what conditions—the basis for where to build transmission, how much generation to procure, and how corporate buyers secure clean, firm power. It was designed for two decades of flat, gradual demand growth. Data center load is none of those things: it is large, geographically concentrated, arrives in gigawatt blocks with no disclosed operating shape, and can be withdrawn as quickly as it appeared.
What is speculative load in an interconnection queue, and how do planners tell it apart from real demand?
Speculative load is capacity requested by projects that may never be built — often the same data center bidding into several regions at once while shopping for power, which counts the same gigawatts more than once. The tested filter is a financial commitment: when AEP Ohio required firm commitments before queue entry, the utility's reported data center pipeline fell from about 30 GW to roughly 5.7 GW. Milestone requirements, independent RTO review of utility submissions, and mandatory data standards are the tools planners have.
Is load flexibility proven and scalable today, or still emerging?
The modeling case for load flexibility is strong; the commercial case is still early. Duke's Nicholas Institute found the 22 largest US balancing authority areas could absorb roughly 76–126 GW of new load if it accepts modest curtailment, and Relae's ERCOT modeling shows demand response eliminating forced load shedding risk at 40 GW of data center buildout, avoiding $5.5 billion in annual consumer welfare losses. What is still missing is the market plumbing—standardized tariffs, interconnection rules, and product definitions—so a data center willing to be flexible has somewhere to sign up.
What should a company look for when evaluating a region's load forecast?
Ask whether the forecast is probabilistic or a single deterministic peak, how often it is refreshed, and whether large loads are broken out by category and operating shape rather than reported as one block of gigawatts. Then ask what milestone or financial commitment a project must clear before its megawatts count toward the forecast. A forecast that cannot answer those three questions cannot tell you how much of the queue ahead of you is real.
[cta]
Beyond Backup Generators: Hydrogen as Baseload Power for AI Infrastructure
Key Takeaways
- Speed to operation is the value proposition. While grid interconnection can take 3-5 years in constrained regions, hydrogen fuel cell systems can be deployed in a fraction of that time—a large advantage for operators racing to meet data center capacity demands.
- Hydrogen is moving beyond backup. Fuel cells could supply 6-15% of incremental data center power, functioning as primary or near-primary power rather than emergency standby.
- Higher fuel costs can be rational. When the alternative is a multi-year wait for grid power and the development loss that comes with it, paying a premium for hydrogen is better than falling behind.
The Grid Can’t Keep Up With Data Centers
The data center infrastructure buildout is moving at a pace the US power grid was never designed to accommodate. Cleanview tracks about 63 GW of operating US data center capacity and another 392 GW in planning, roughly six times what exists today. Developers in high-demand corridors—Northern Virginia, Central Texas, Phoenix—are finding that the grid can't deliver new capacity fast enough.
Interconnection queues now stretch 3-5 years in many regions, and that’s before accounting for permitting, transmission upgrades, and substation buildouts. For operators that need power online faster than the grid can deliver it, this timeline gap is a fundamental constraint on the business.
This mismatch between AI deployment, generator bottlenecks, and grid timelines is why hydrogen is entering the conversation as a viable power option for a growing subset of data center deployments, alongside natural gas with carbon capture, geothermal, and long-duration energy storage.
Hydrogen Fuel Cells: From Standby to Primary Power
For most of its history in data centers, hydrogen has been discussed as a cleaner replacement for diesel backup generators. That framing undersells the opportunity.
The shift happening now is more fundamental: hydrogen fuel cells are being evaluated as primary or near-primary power sources for behind-the-meter and facilities that can’t wait for grid connection. Notably, many modern fuel cell systems—including solid oxide fuel cells—can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy's 2024 deal with American Electric Power to provide up to 1 GW of fuel cells for data center power illustrates this approach: the systems will initially run on natural gas, with the capability to switch to 100% hydrogen in the future.
Furthermore, fuel cell systems are modular, can be deployed incrementally as load grows, and provide continuous power output. This is a promising path, and one that will scale only as fast as the fuel cell supply chain can keep up. Unlike solar or wind, fuel cells aren’t weather-dependent. Running on hydrogen, they produce zero direct emissions at the point of use. Running on natural gas, they still emit CO2, but their higher efficiency gives them a lower carbon intensity than a comparable gas turbine.
Goldman Sachs estimates that fuel cells could supply 6-15% of incremental data center power (the estimate doesn't specify fuel mix, though most near-term deployments would run primarily on natural gas). This is a meaningful share of new capacity, driven largely by operators who face years-long waits for both grid connections and new gas turbines. Bloom Energy, whose fuel cell products serve data center applications, has been a notable outlier in an otherwise struggling hydrogen sector, with its stock rising sharply on strong revenue performance and growing investor enthusiasm around data center power demand.
Speed to power depends on the fuel. Solid oxide fuel cells run on pipeline natural gas today, so operators do not wait for a hydrogen supply chain. Bloom states it can deliver onsite power for an entire data center in as little as 90 days, with the ability to add modules as load grows under certain circumstances. In all but a few select locations, hydrogen comes later when the same systems switch fuels as clean supply scales. Projects that need hydrogen from day one face additional challenges. Limited hydrogen availability and supporting infrastructure across much of the US can undermine the potential speed advantage of hydrogen-dependent projects. Nevertheless, locations with suitable hydrogen supply and supporting infrastructure may offer viable near-term opportunities.
The Hydrogen Premium: When Paying More Makes Sense
Hydrogen-generated power is more expensive than other forms of electricity generation in most markets. The logistics penalty (including compression, transport, and storage) can push hydrogen from $4/kg at the production site to $8-16/kg delivered, making the economics look unfavorable on a simple $/MWh comparison. In practical terms, hydrogen at $4-6/kg translates to roughly $120-180/MWh on an energy-content basis (LHV). At a fuel cell electrical efficiency of around 50%—typical for solid oxide systems—the effective cost of electricity rises to approximately $240-360/MWh for co-located production, compared to $40-60/MWh for natural gas fuel cells, $51-129/MWh for gas combined cycle, and $144-276/MWh for gas peakers. Operators can improve hydrogen economics by co-locating with production, avoiding the logistics penalty that can double or quadruple delivered costs.
While expensive, this cost comparison misses the central point. The relevant question is not whether hydrogen is cheaper than grid power, but whether it is better than having no access to power at all.
For an operator with signed contracts and a 100 MW facility sitting idle during a multi-year interconnection queue, the opportunity cost is substantial. At average US wholesale colocation rates (~$196/kW/month - a record high), a facility of that size represents roughly $235 million per year in potential revenue—meaning even a single year of delay can outweigh years of hydrogen fuel premiums.
The Inflation Reduction Act’s 45V Production Tax Credit further compresses the gap, offering up to $3/kg for clean hydrogen production—but projects must begin construction by December 31, 2027, to qualify. That deadline adds urgency to what’s already a time-sensitive calculus.
Reframing the Cost Debate for Speed-to-Power
The debate about whether hydrogen is cost-competitive with grid power misses the strategic challenge facing data center operators today: the fastest path to reliable, clean power. Hydrogen can play a consequential role in that timeline in some markets.
Assessing that requires modeling the full picture: grid interconnection timelines, hydrogen supply chain costs at a specific location, the 45V credit’s impact on project economics, and how hydrogen compares to batteries and other bridging technologies for a data center’s particular load profile.
Relae’s advisory team helps data center operators and technology companies evaluate these tradeoffs with rigorous, independent analysis. If speed to operation is a factor in your energy planning, let’s talk.
Frequently Asked Questions
How much faster is hydrogen fuel cell deployment than waiting for grid interconnection?
Grid interconnection in constrained regions can take 3-5 years once permitting, transmission upgrades, and substation buildouts are factored in. Fuel cell systems, especially those that start on natural gas and then transition to hydrogen, can be deployed in a fraction of that time. They are modular and can be installed and scaled incrementally as a facility’s load grows, though the pace depends on equipment and fuel supply.
If hydrogen costs more than grid power, why would an operator choose it?
For an operator with a 100 MW facility sitting idle during a multi-year interconnection queue, the lost revenue—roughly $235 million a year at average US wholesale colocation rates—can outweigh years of hydrogen’s fuel premium. That makes the higher cost a rational tradeoff against a multi-year wait for grid power, not just an expensive alternative to it.
Do hydrogen fuel cell systems have to run on pure hydrogen from day one?
No. Many modern fuel cell systems, including solid oxide fuel cells, can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy’s up to 1 GW agreement with American Electric Power follows this model: the systems start on natural gas, with the capability to switch to 100% hydrogen as the hydrogen supply chain matures.



