Scope 2 Emissions Explained: Tracking, Reporting, and Reducing Impact
Key Takeaways
- Scope 2 emissions (indirect emissions from energy use) are increasingly critical to address. With surging electricity demand, especially from data centers, scope 2 is a growing share of corporate emissions and a priority for decarbonization.
- Approaches to scope 2 accounting are evolving—and formal changes are now on the table. Both location-based and market-based methods remain accepted under the Greenhouse Gas Protocol. Still, the Protocol's recently closed public consultation proposes more granular approaches, including 24/7 power and carbon matching, that would better reflect the realities of modern power markets.
- Proven decarbonization levers, such as reducing energy use, entering power purchase agreements, procuring green tariffs, and buying high-quality renewable energy certificates, are already available and impactful. Decarbonization, not just measurement, must be the goal. Companies don’t need to wait to decarbonize.
Accounting for Indirect Emissions From Energy Use
As businesses and organizations strive to reduce their environmental impact, carbon accounting has become an essential tool for tracking and managing greenhouse gas (GHG) emissions. Carbon accounting helps organizations measure, report, and mitigate their emissions across various activities. A key framework for categorizing these emissions is the Greenhouse Gas Protocol (GHG Protocol), which classifies emissions into three scopes:
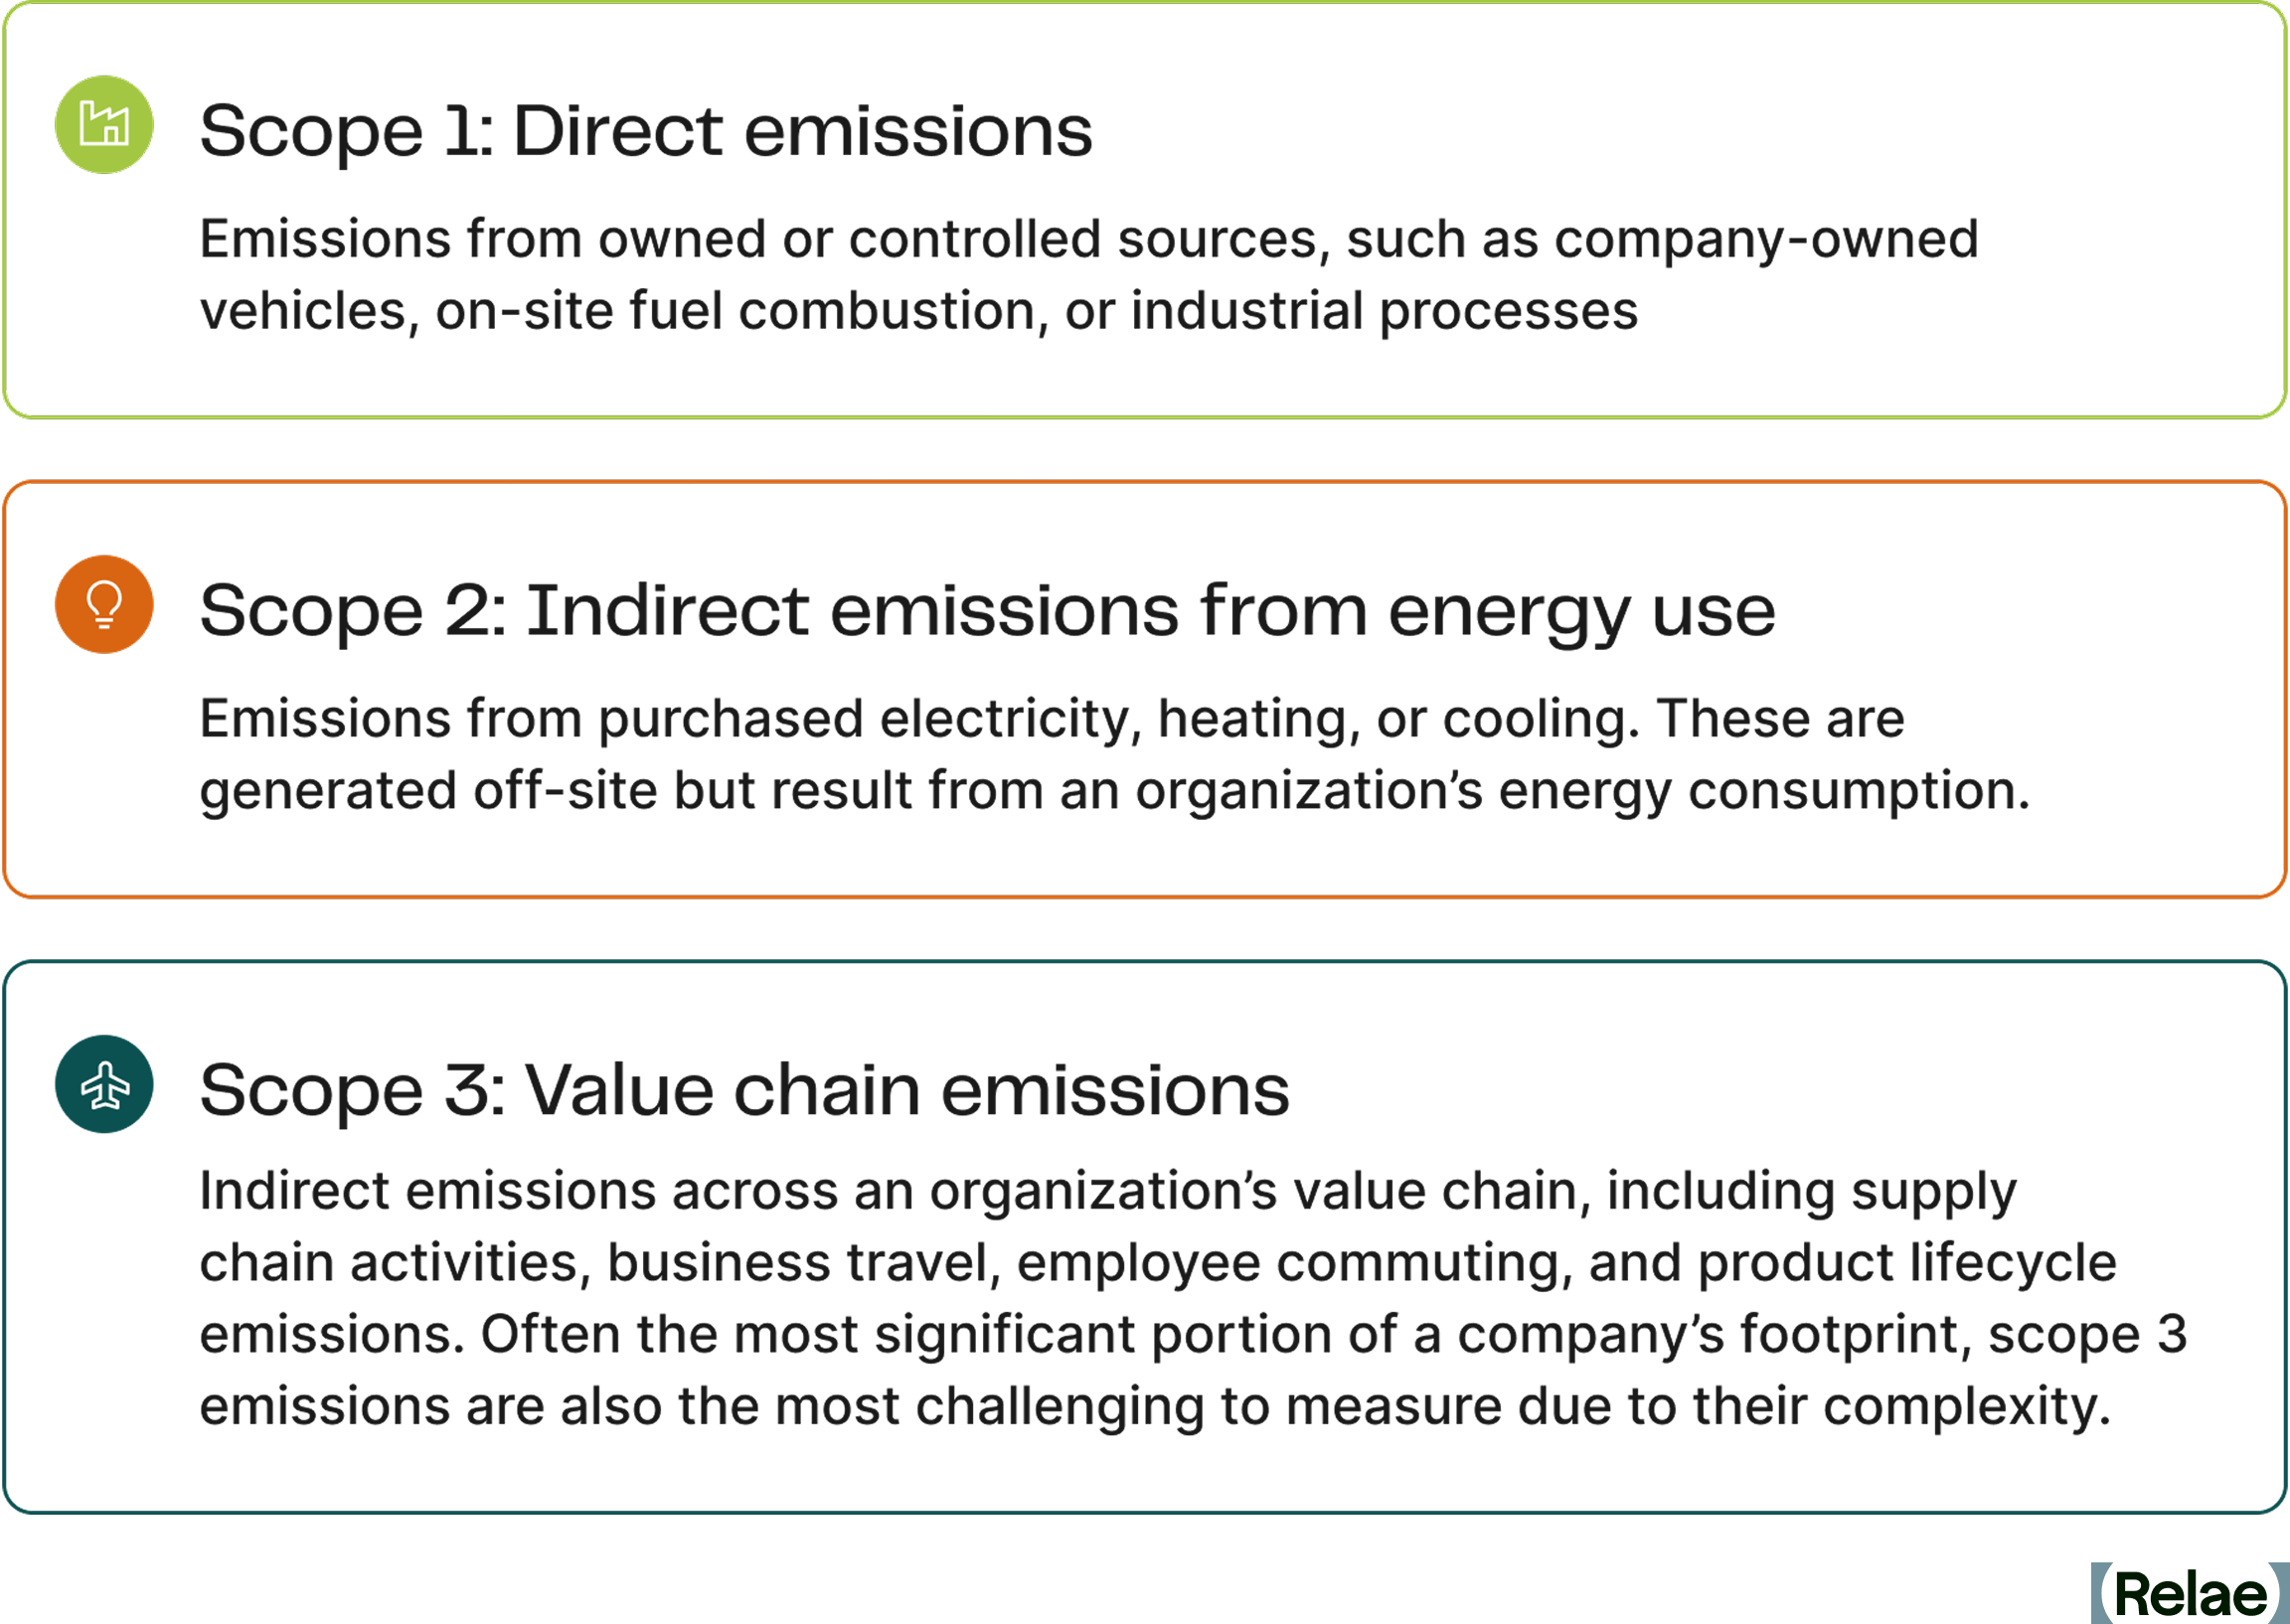
Each scope presents unique challenges and opportunities for reduction. Among them, scope 2 emissions are particularly significant because they stem from purchased energy, which is often generated using fossil fuels. However, numerous reduction mechanisms exist today to help organizations eliminate these emissions, such as improving energy efficiency in order to use less energy, and transitioning to renewable energy sources through market-based mechanisms. Understanding scope 2 emissions is crucial for businesses looking to contribute meaningfully to the global energy transition and achieve sustainability goals.
What Are Scope 2 Emissions?
Scope 2 emissions refer to indirect GHG emissions associated with the consumption of purchased energy. Unlike scope 1 emissions, which result from direct fuel combustion, scope 2 emissions arise from the generation of electricity, steam, heat, or cooling that a company procures from external sources.
The primary sources of scope 2 emissions include:
Purchased electricity: When businesses buy electricity from a utility provider, the emissions from power plants that generate this electricity are classified under scope 2.
Purchased heat, steam, and cooling: Some companies purchase heat, steam, or cooling services instead of generating them on-site. These services often come from centralized facilities that may rely on fossil fuels, thereby contributing to scope 2 emissions.
What sets scope 2 emissions apart from other scopes is the presence of market-based mechanisms that offer multiple pathways for organizations to reduce their carbon footprint. Unlike scope 1, where emissions reductions often require technological shifts or operational changes, scope 2 reductions can be achieved through strategic procurement decisions. The transition to renewable energy sources is an essential component of sustainability strategies, setting the stage for a broader energy transition across industries and economies.
How Are Scope 2 Emissions Measured Today?
The GHG Protocol currently outlines two primary approaches for calculating scope 2 emissions: the location-based method and the market-based method.
Location-Based Method
The location-based method calculates emissions for electricity consumption based on the average emissions intensity of the grid where the energy consumption occurs. This approach is mandatory under various reporting frameworks and does not take into account a company’s procurement choices.
- Relies on grid averages: Emissions are calculated based on regional grid emissions factors rather than specific energy purchases.
- Time-delayed data: Since grid emissions factors are typically updated annually, this method may not reflect real-time energy sourcing changes.
- Limited control: Companies using this method have less direct influence over their reported emissions, as they depend on the overall energy mix of their region.
Market-Based Method
The market-based method, on the other hand, reflects an organization’s actual procurement decisions and energy-sourcing strategies. It accounts for specific contracts, such as power purchase agreements (PPAs), renewable energy credits (RECs), and green tariffs, which allow businesses to claim lower emissions from their purchased electricity.
- Reflects company choices: Emissions calculations take into account contractual agreements for renewable energy purchases.
- Mechanism for electricity transition: Encourages organizations to invest in low-carbon electricity options and actively support the transition to renewables.
- Multiple reduction options: Companies can reduce their scope 2 emissions through a portfolio of mechanisms like PPAs, RECs, and green tariffs, making this method a flexible and strategic tool for decarbonization.
While market-based mechanisms provide flexibility in reducing scope 2 emissions, they also highlight the need for more precise and updated carbon accounting methodologies. For example, some decarbonization strategies, such as time-shifting energy consumption to better match renewable generation, are not accounted for under these methods. This and other limitations mean that the traditional methods outlined in the GHG Protocol are increasingly seen as outdated in an era of rapid changes in energy generation and grid dynamics. As a result, the market is shifting toward more advanced power emission accounting methodologies that provide a more accurate reflection of emissions associated with electricity use.
Proposed Changes to the GHG Protocol Scope 2 Guidance
The current GHG Protocol Scope 2 Guidance provides a market-based instrument methodology, originally designed in the early 2000s, that allows US-based companies to procure renewable energy at any point within a year from anywhere in North America and apply it to any of its annual electricity consumption within that same year. This methodology, as written, allows for a potentially significant mismatch of “emissions caused” (by consuming electricity) versus “emissions avoided” (by generating renewable electricity) in that it does not account for any of the realities of electric grids and generators, which vary significantly over different regions, seasons, and time of day.
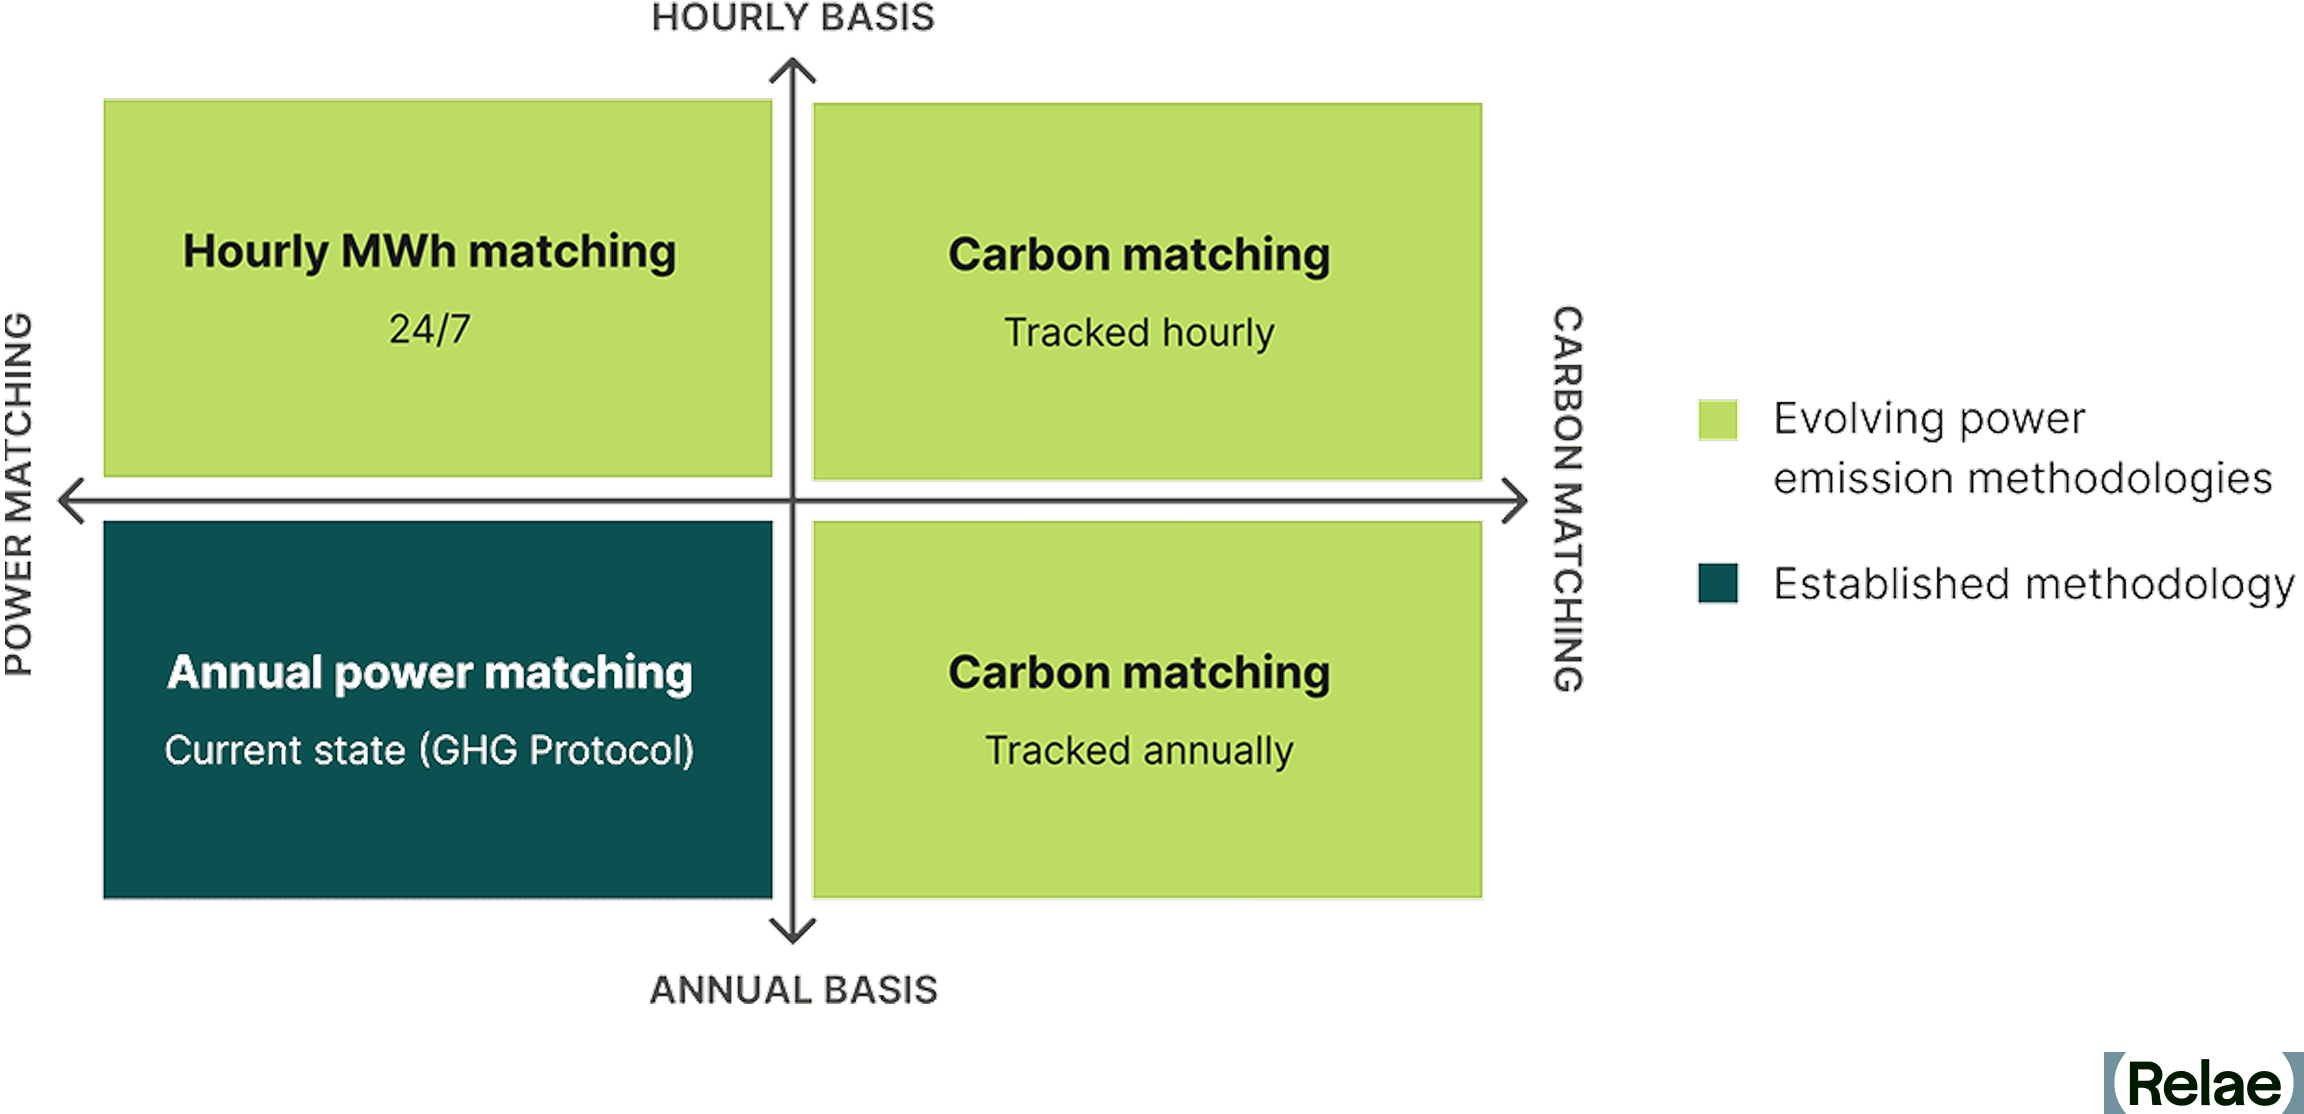
In response to this, the GHG Protocol Scope 2 Guidance is currently undergoing a revision process, which will include how emissions associated with electricity consumption are calculated. A focus of the revision process is on how to better account for the real emissions associated with a corporate’s electricity consumption, and more impactful ways of mitigating them through market-based instruments and other approaches. Advanced power emission accounting methodologies, such as 24/7 power matching and carbon matching, are being explored as ways to better represent the GHG emissions associated with electricity consumption.
- 24/7 power matching emphasizes matching electricity consumption with an equivalent amount of renewable energy production on an hourly basis.
- Carbon matching emphasizes measuring the emissions impact of incremental electricity consumption or production at a specific time.
These emerging methodologies propose a shift toward more granular temporal and region-specific matching, which could require companies to rethink their emissions reporting approach and explore more advanced tracking tools. They may also introduce new strategies beyond market-based instruments for reducing scope 2 emissions, such as time-shifting energy consumption.
As power grids continue to decarbonize and new digital tools emerge, businesses will need to adapt to these evolving methodologies to remain compliant, enhance sustainability strategies, and achieve meaningful reductions in emissions. Companies that proactively integrate advanced power emission tracking into their carbon accounting strategies will be better positioned to lead in the transition to a low-carbon economy.
How to Reduce Scope 2 Emissions
The GHG Protocol provides multiple mechanisms for reducing scope 2 emissions, allowing organizations to shift their energy consumption toward lower-carbon alternatives. These include:
- Reducing energy consumption: Improving energy efficiency in operations can significantly lower electricity use. In some cases, this involves capital investments in more energy-efficient equipment, but in other cases, it can be based on operational changes such as reducing unnecessary lighting, HVAC, and other services during non-working hours. (Electrification efforts, such as shifting from fossil fuel-powered systems to electric alternatives, may actually increase scope 2 emissions, but this can ultimately reduce overall emissions by correspondingly decreasing scope 1 emissions and allowing for renewable energy procurement.)
- RECs: Companies can purchase unbundled RECs (emissions “attributes” separated from the actual electricity product) to offset emissions associated with purchased electricity. While there has been criticism of RECs due to their significant range in quality, high-quality RECs are available, which may include ensuring regional matching, financial additionality, on-line date additionality, or tighter temporal generation to consumption matching. The use of high-quality unbundled RECs is the most accessible and realistic option for most smaller-scale companies to address scope 2 emissions.
- On-site generation and co-location: Installing on-site renewable energy generation, such as solar panels, allows companies to directly offset their electricity consumption from the grid. In some commercial settings, such as companies using leased real estate or co-located data centers, partnering with facilities that prioritize renewable energy procurement can help reduce scope 2 emissions for the facility owner while the facility occupant reduces scope 3 emissions.
- PPAs: Entering into long-term contracts with renewable energy providers ensures companies receive electricity from clean energy sources while supporting the expansion of renewable generation capacity. PPAs are available with standardized contract terms, and some service providers will aggregate demand from multiple smaller companies to reach the minimum required amount for typical PPA contracts. Hedging products are also available to reduce market risks.
- Green tariffs: Many utilities offer green tariffs that enable businesses to purchase renewable energy directly through their electricity provider, often at a premium but with lower emissions impact. For many smaller companies, this is a more viable approach than a PPA with a single renewable generator.
By adopting a combination of these strategies, businesses can significantly lower their scope 2 emissions while aligning with broader sustainability goals and regulatory requirements. The path to decarbonization requires proactive investment in cleaner energy sources, efficient consumption practices, and leveraging market-based instruments to drive the transition toward a low-carbon future.
Why Does Reducing Scope 2 Emissions Matter?
Reducing scope 2 emissions is the underpinning of decarbonizing the power sector and enabling the global energy transition. In 2025, S&P reported that corporate buyers added 15.2 GW of renewable capacity in the US, up from 9.1 GW in 2024, illustrating the growing impact of the corporate sector on the electricity grid. Cleaner grids translate to lower emissions for all energy users. Organizations that actively reduce their scope 2 emissions can contribute to decreasing demand for fossil fuel-based electricity and accelerate the deployment of renewable energy infrastructure.
For companies that own and operate data centers, this transition is especially important. AI data centers consume large amounts of electricity, and their reliance on purchased power makes them a significant source of scope 2 emissions. Since many businesses rely on third-party data center services, reducing emissions from these facilities also helps lower scope 3 emissions across industries. Corporates can influence data centers by requiring that they have a clear and explicit low-emission power strategy in place before procurement.
Beyond direct corporate benefits, reducing scope 2 emissions has a tangible long-term impact on power grids. Increased investment in renewable energy procurement sends a strong market signal, encouraging utilities and developers to expand clean energy projects. As more companies commit to sourcing renewable energy, the overall mix of grid power shifts, making low-carbon electricity more accessible and reducing reliance on fossil fuel-based generation. Ultimately, widespread corporate action in scope 2 emissions reduction supports the broader decarbonization of power markets and strengthens global climate commitments.
Frequently Asked Questions
Will RECs (renewable energy certificates) still count toward scope 2 reductions under the GHG Protocol's proposed changes?
Under the current Scope 2 Guidance, yes—RECs remain a valid market-based instrument. The proposals from the GHG Protocol's recent consultation range from retaining market-based accounting with stricter quality criteria to restructuring how instrument-based claims are reported altogether, and nothing is final until the revised standard is published. What's clear is that scrutiny is rising, particularly for unbundled RECs with weak temporal or geographic connection to a company's actual consumption, so prioritizing high-quality RECs now is the best way to future-proof a procurement strategy.
How would the proposed hourly and regional matching requirements affect companies that rely on unbundled RECs today?
Hourly (24/7) and regional matching would require renewable generation claims to line up much more closely with when and where a company actually consumes electricity. Companies relying on annually matched, unbundled RECs sourced from distant grids would likely see their reported market-based emissions rise under such requirements. The practical preparation is to start collecting more granular (ideally hourly) consumption data and shift toward RECs and contracts with tighter regional and temporal matching.
What's the practical difference between location-based and market-based scope 2 accounting, and will that distinction survive the GHG Protocol's revision?
The location-based method calculates emissions using the average emissions intensity of the local grid, regardless of procurement choices, while the market-based method reflects a company's actual contracts, such as PPAs, RECs, and green tariffs. The consultation explored options from strengthening the criteria for market-based claims to reporting emissions and market instruments in separate, complementary statements. Both concepts will exist in some form, but companies should expect the requirements behind market-based claims to tighten.
When is the new Scope 2 Guidance expected to take effect, and what should companies do now to prepare?
Per the GHG Protocol's July 2026 development plan, a draft of the revised consolidated Corporate Standard is expected for public consultation in 2027, with a final published standard currently estimated for late 2028, and adoption timelines will follow publication. Companies should take action now. Energy efficiency, PPAs, green tariffs, and high-quality RECs reduce real emissions under any accounting regime. Building hourly consumption tracking and auditing the quality of existing REC portfolios now will make any future transition smoother.
GHG Accounting
Relae helps companies, investors, and project developers quantify and interpret emissions across operations, value chains, products, projects, and portfolios. We combine advanced emissions analytics, life cycle assessment, and sector-specific expertise to help you identify emissions hotspots, evaluate high-impact opportunities, and build credible baselines for reporting and investment decisions.
Ready to Navigate What Comes Next?


Julia Millot
Julia Millot
,

Julia Millot is a Senior Power Decarbonization Manager at Relae, working directly with clients on measuring and reducing electricity-related GHG emissions and optimizing power portfolios. Julia has over a decade of experience working with clients in the energy, tech, retail, financial, and manufacturing sectors on growth and climate strategies. Prior to Relae, she led US Climate Advisory at Position Green and ran her own consultancy, Green Opal Advisors, focusing on corporate decarbonization.
What to Read Next
Navigating Scope 2 Accounting Changes
Key Takeaways
- Voice your opinion: The Greenhouse Gas (GHG) Protocol is updating its scope 2 guidance with final standards expected in 2027, which may require hourly and regional matching of renewable energy certificates (RECs), potentially changing how companies claim their electricity-related emission reductions.
- Act now to secure renewable energy contracts: Companies should move forward with their scope 2 climate commitments today. The GHG Protocol is expected to grandfather in contracts entered into under existing rules.
- Beyond the megawatt hour (MWh): High-impact forward REC contracts measure impact beyond the current annual MWh match requirement, maximizing near-term carbon abatement and social impact for every dollar invested.
Why 2027 Rule Changes Matter for 2030 Targets
Companies racing to meet 2030 climate targets face converging pressures: surging electricity demand, constrained renewable energy supply, and scope 2 accounting rules that could undergo significant changes by 2027.
In a recent webinar, power market experts from Relae (formerly Carbon Direct) and Ever.green explored these changes. Patti Smith, former Electricity Decarbonization Lead at Relae; Julia Millot, Senior Power Decarbonization Manager at Relae; and Liz Pearce, Chief Revenue Officer at Ever.green, unpacked what's changing and how companies can respond.
The stakes are high. Based on GHG Protocol Scope 2 Public Consultation materials, companies may need to match RECs to electricity consumption on an hourly and locational basis as early as 2028. However, we expect the GHG Protocol to grandfather forward REC contracts signed before new rules take effect, enabling companies to continue advancing toward 2030 targets amid rule uncertainty.
Big Changes to the Power Grid
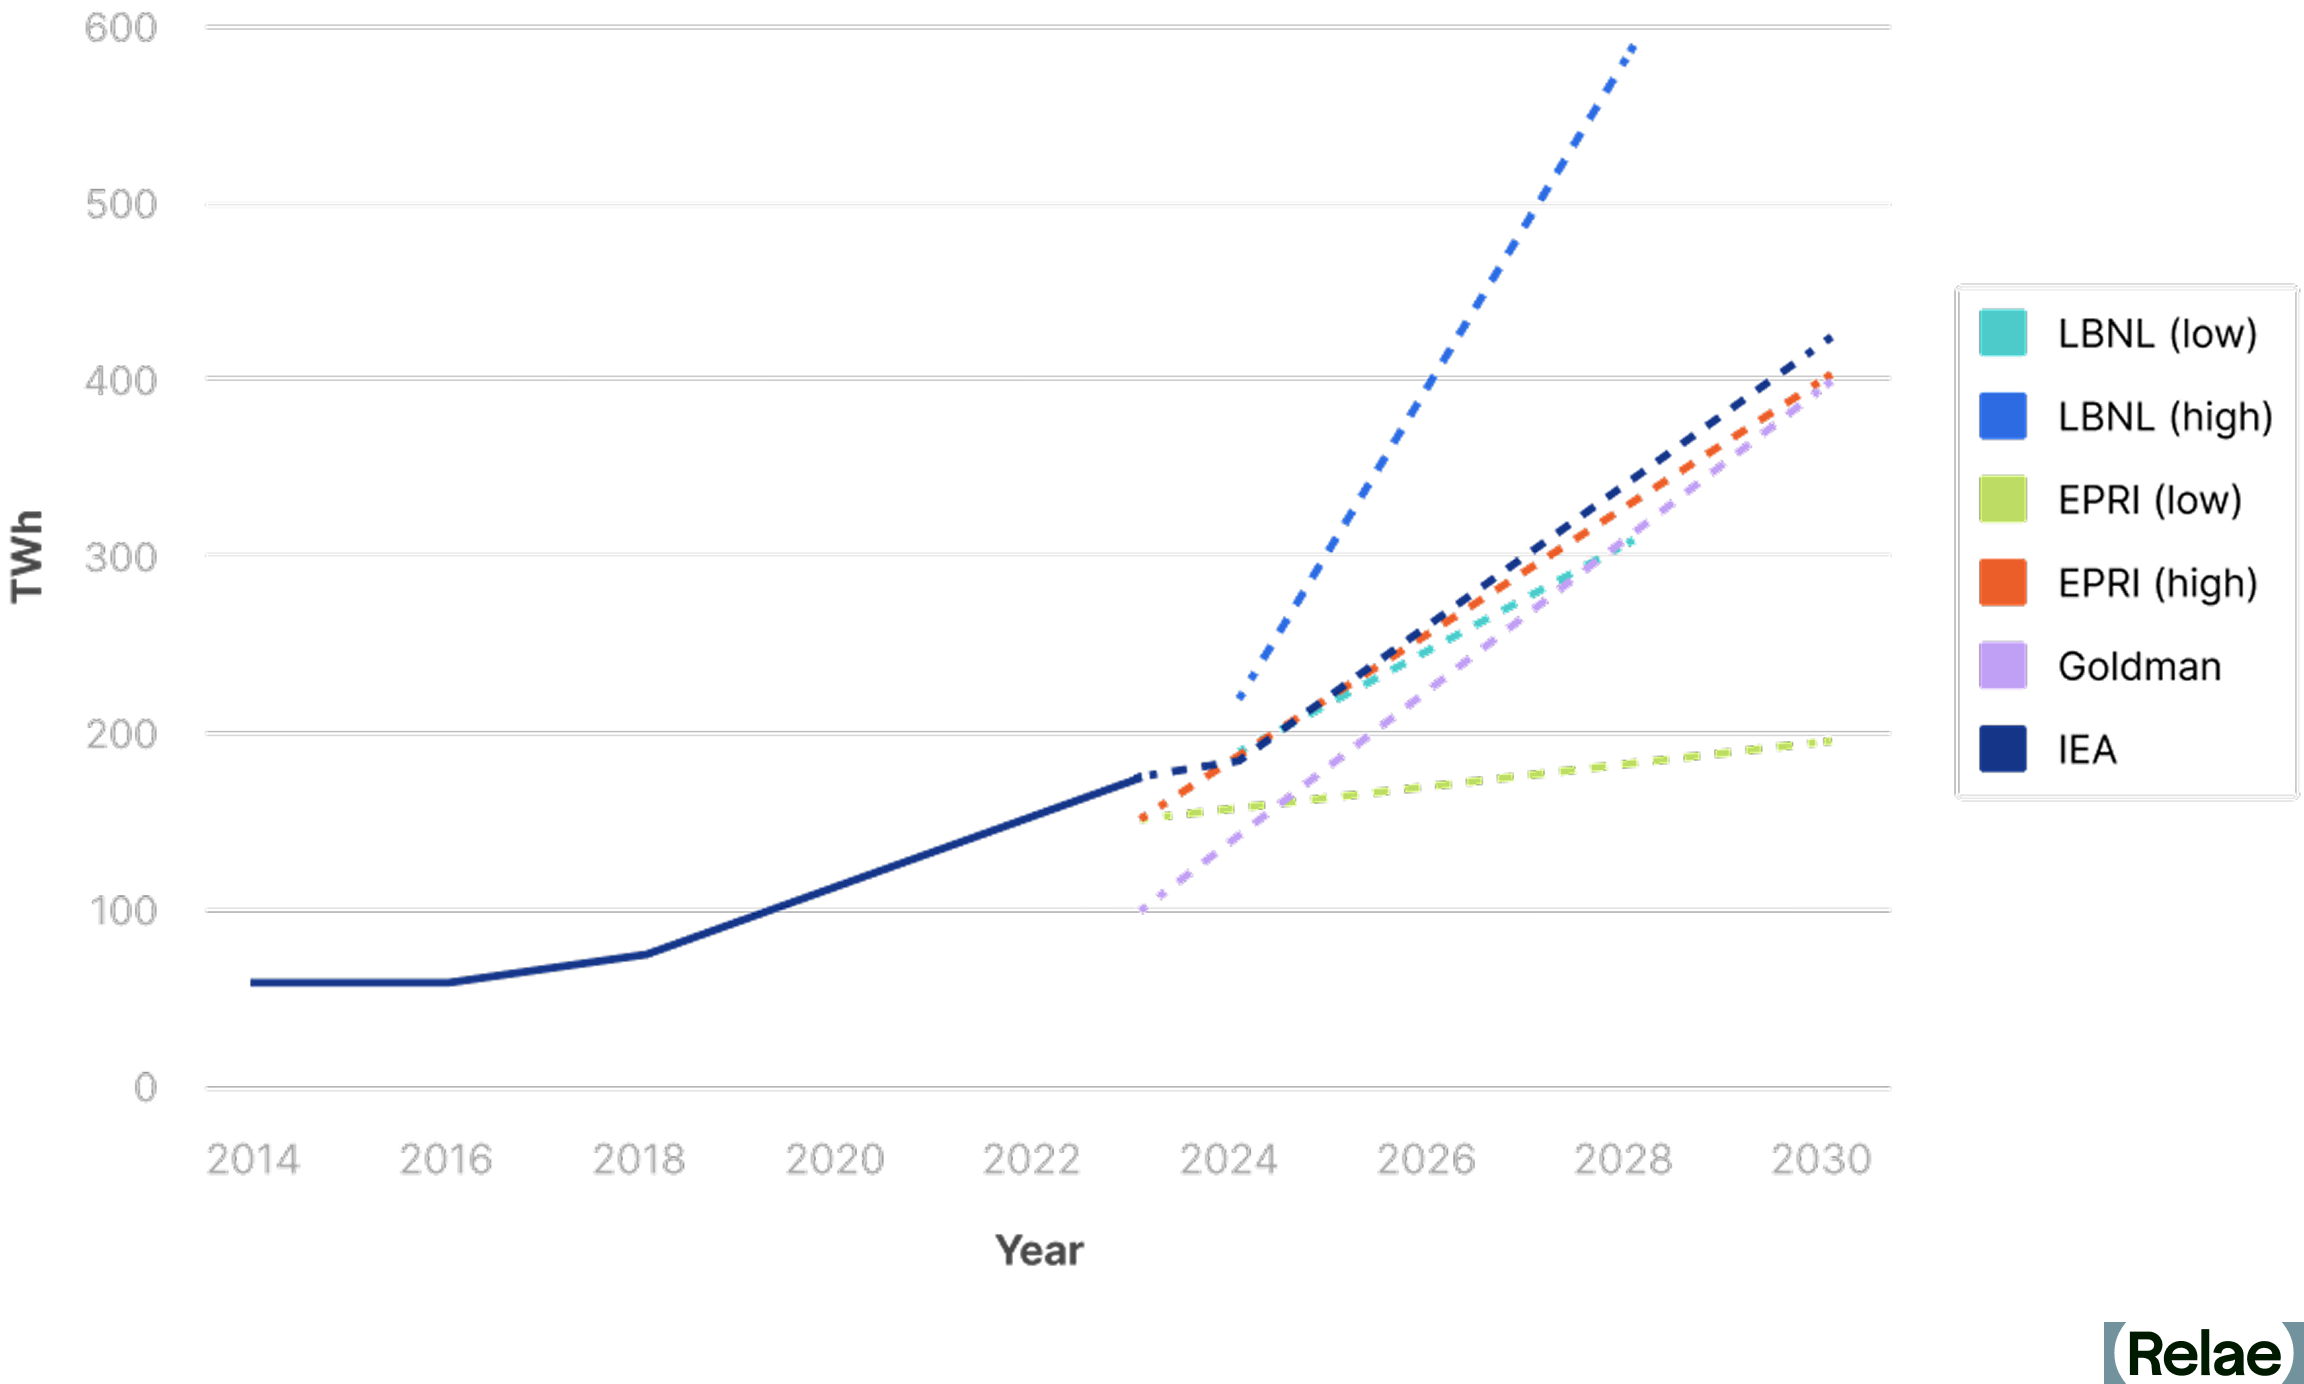
The US power grid is entering sustained demand growth for the first time in decades. "Over the next five years, data centers alone are going to put [the equivalent] of four New York Cities onto the grid," Smith explains, citing forecasts that project around 200 terawatt hours of new data center load through 2030 (i.e. cumulative energy consumption). That demand growth also shows up in near-term grid planning. NERC's January 2026 Long-Term Reliability Assessment forecasts North American summer peak demand rising by 224 gigawatts—a 24% increase—over the next decade, with new data centers cited as the primary driver. These figures highlight that peak capacity and total energy consumption are directly impacted by the data center boom.
Meanwhile, new renewable projects face headwinds. Smith points to interconnection queue delays: "Solar and battery projects are taking three to five years from initial request to operation." At the same time, clean energy tax credits, which were driving wind and solar expansion, have been curtailed. New restrictions on foreign supply chain materials, which are critical to renewable project development, are further hampering the development of new clean electricity projects.
The result: Power demand is rising while new renewable electricity supply is getting throttled.
The Messy Reality of Electricity Emissions Accounting
Quantifying the emissions from an individual power plant is straightforward. Allocating those emissions to the companies that consume power is far more complicated.
Grid-supplied electricity comes from many generators that shift constantly, sometimes even second to second. Companies can’t directly measure emissions from a grid-connected load because the generators serving it continuously change.
Without direct measurement, companies need rules to estimate the emissions they are responsible for. The GHG Protocol’s Scope 2 Guidance provides that framework, establishing how companies estimate electricity-related emissions and how to reduce them through renewable energy purchases.
How Companies Currently Claim Renewable Energy
For the past decade, companies have used renewable energy purchases to achieve their scope 2 emission reduction goals. The most widely used mechanism is the REC, each representing clean energy attributes for one MWh of renewable electricity generated and added to the grid. Currently, when a company buys RECs equal to its annual electricity consumption, it can claim 100% renewable electricity. Under current rules, companies can use purchased renewable energy from anywhere in North America and apply it to any load in North America at any time during the year.
Importantly, emissions from different power grids vary widely across North America depending on time of day, time of year, and the power grid makeup.
This flexibility allows companies to match a REC from a clean grid against electricity consumption from a dirtier one, creating a potential mismatch between emissions claimed and actual emissions avoided. This gap has drawn scrutiny, contributing to the motivations for the scope 2 rules rewrite.
What's Changing in GHG Protocol Scope 2 Accounting?
On October 19, 2025, after years of consultation, the GHG Protocol released two separate proposals for public consultation:
1. Scope 2 changes: Moving away from annual REC matching to an ‘hourly and regional’ REC matching requirement.
2. New consequential methodology: A new approach to estimating emissions caused by a company’s consumption and avoided by its renewable energy contracts.
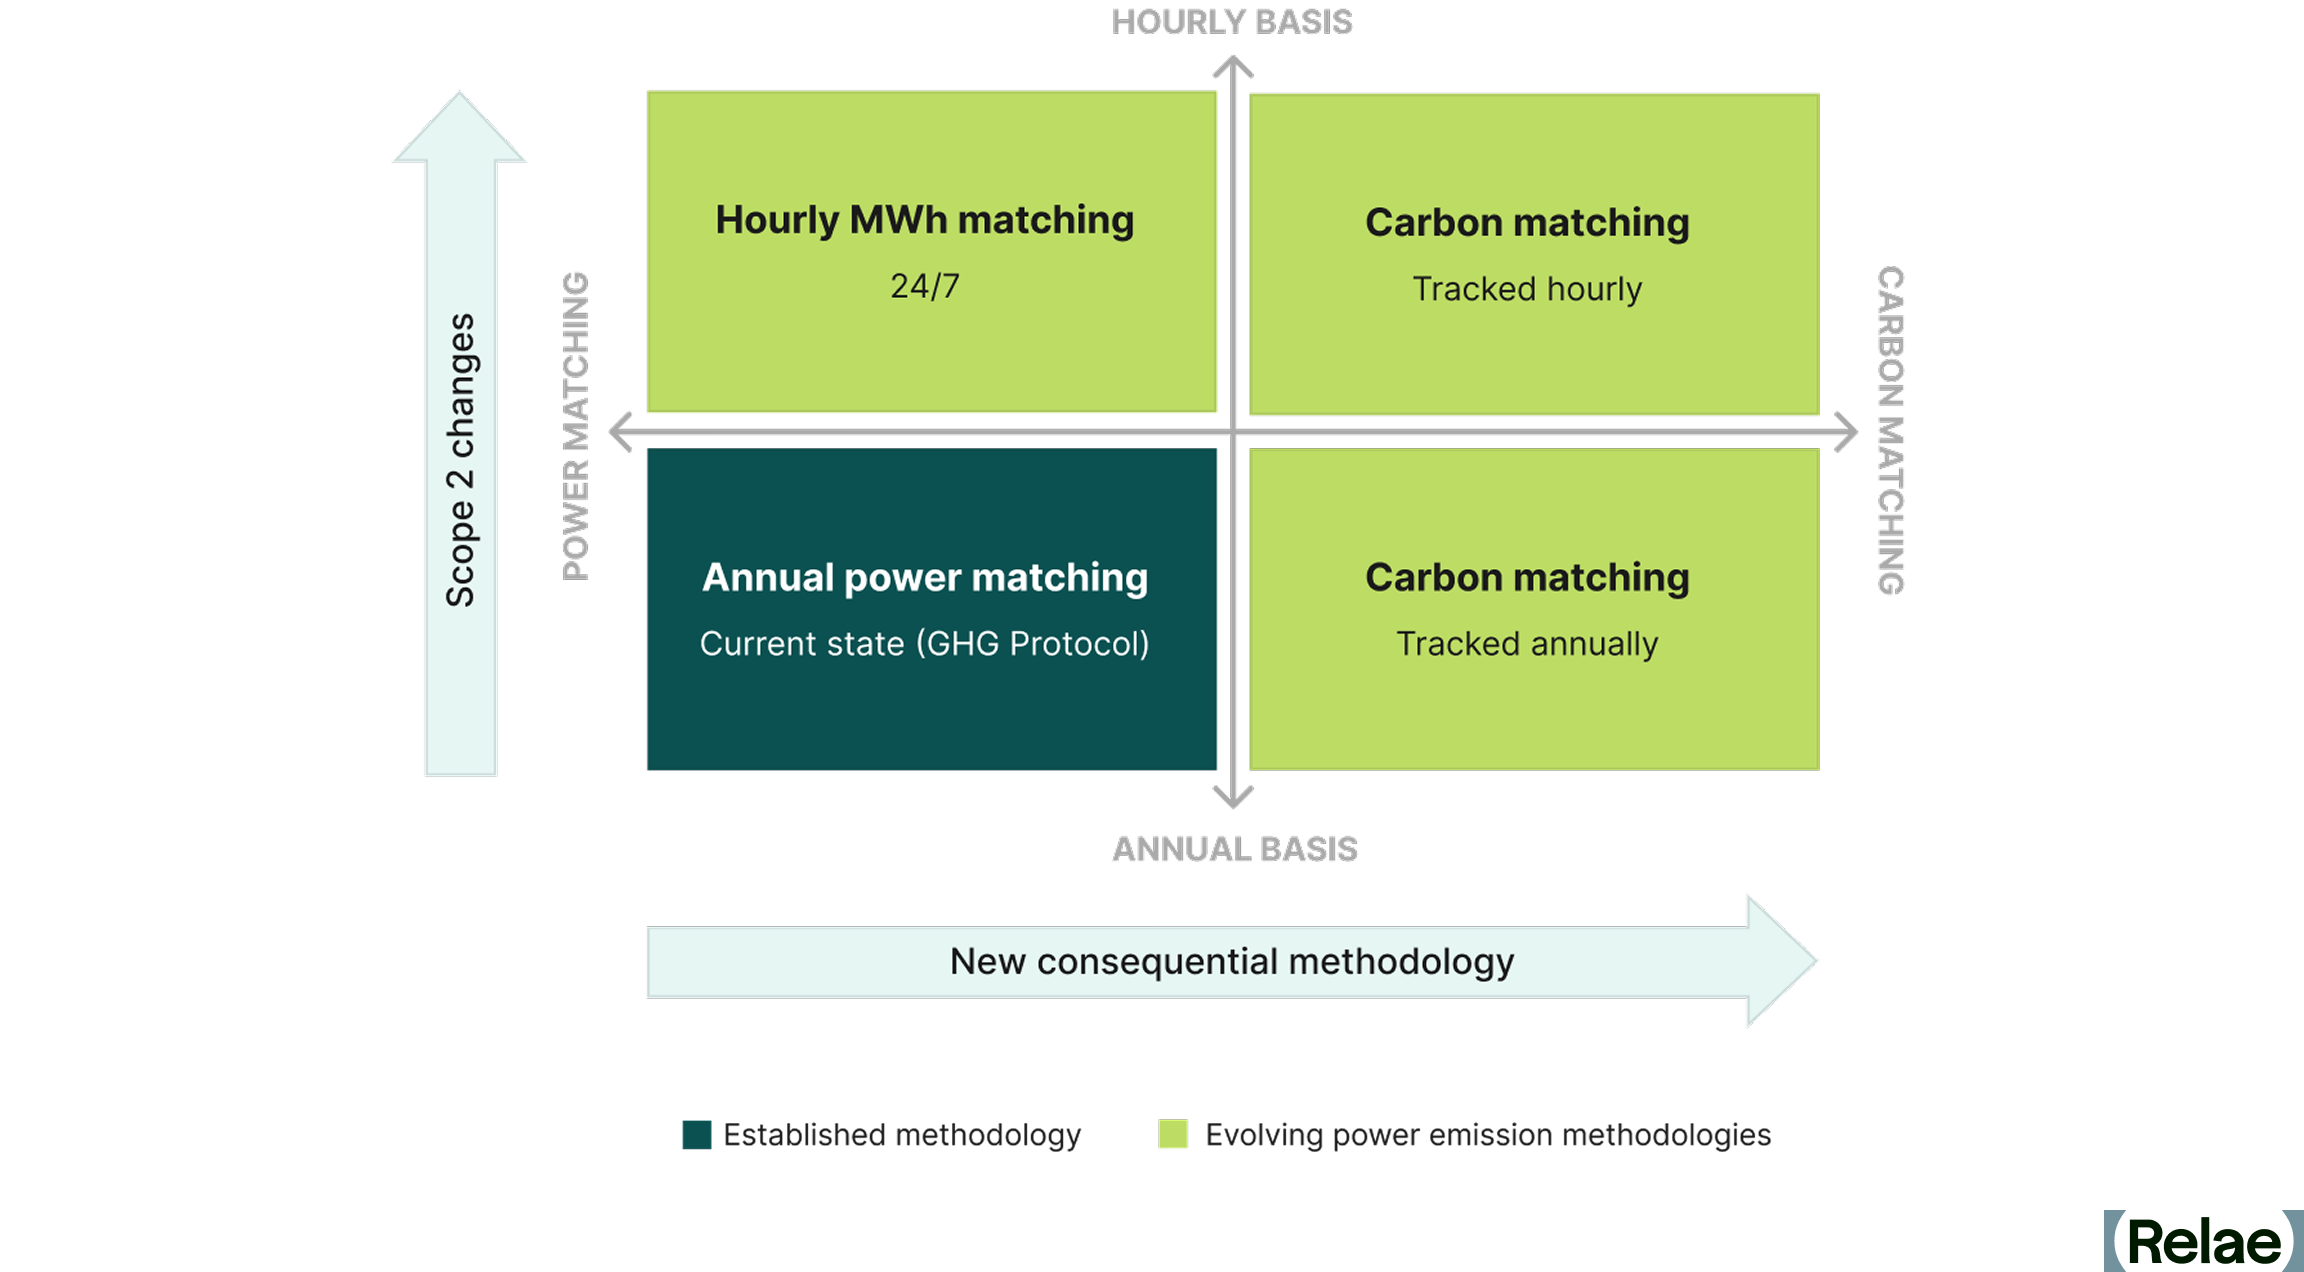
The hourly matching proposal (24/7): Companies would match RECs to consumption hour by hour within the same grid region, rather than annually across any North American grid.
"A REC generated on a Texas wind farm would not be able to be used for electricity consumed in New York," Millot explains.
The consequential approach: This proposes a carbon matching methodology, which estimates emissions caused by a load and estimates the emissions a renewable project displaces.
"Projects in the Carolinas are avoiding 0.6 or 0.7 tons of CO2 per megawatt hour, whereas a California project is probably closer to 0.2 or 0.3," Smith explains.
Projects in the Carolinas deliver more than double the climate impact per REC under the consequential rules. In this methodology, the load and generator do not need to be located in the same region.
While the proposed rules and new methodologies work through the public consultation process, it will be important for companies to start to anticipate the potential impacts on their climate goals and strategies.
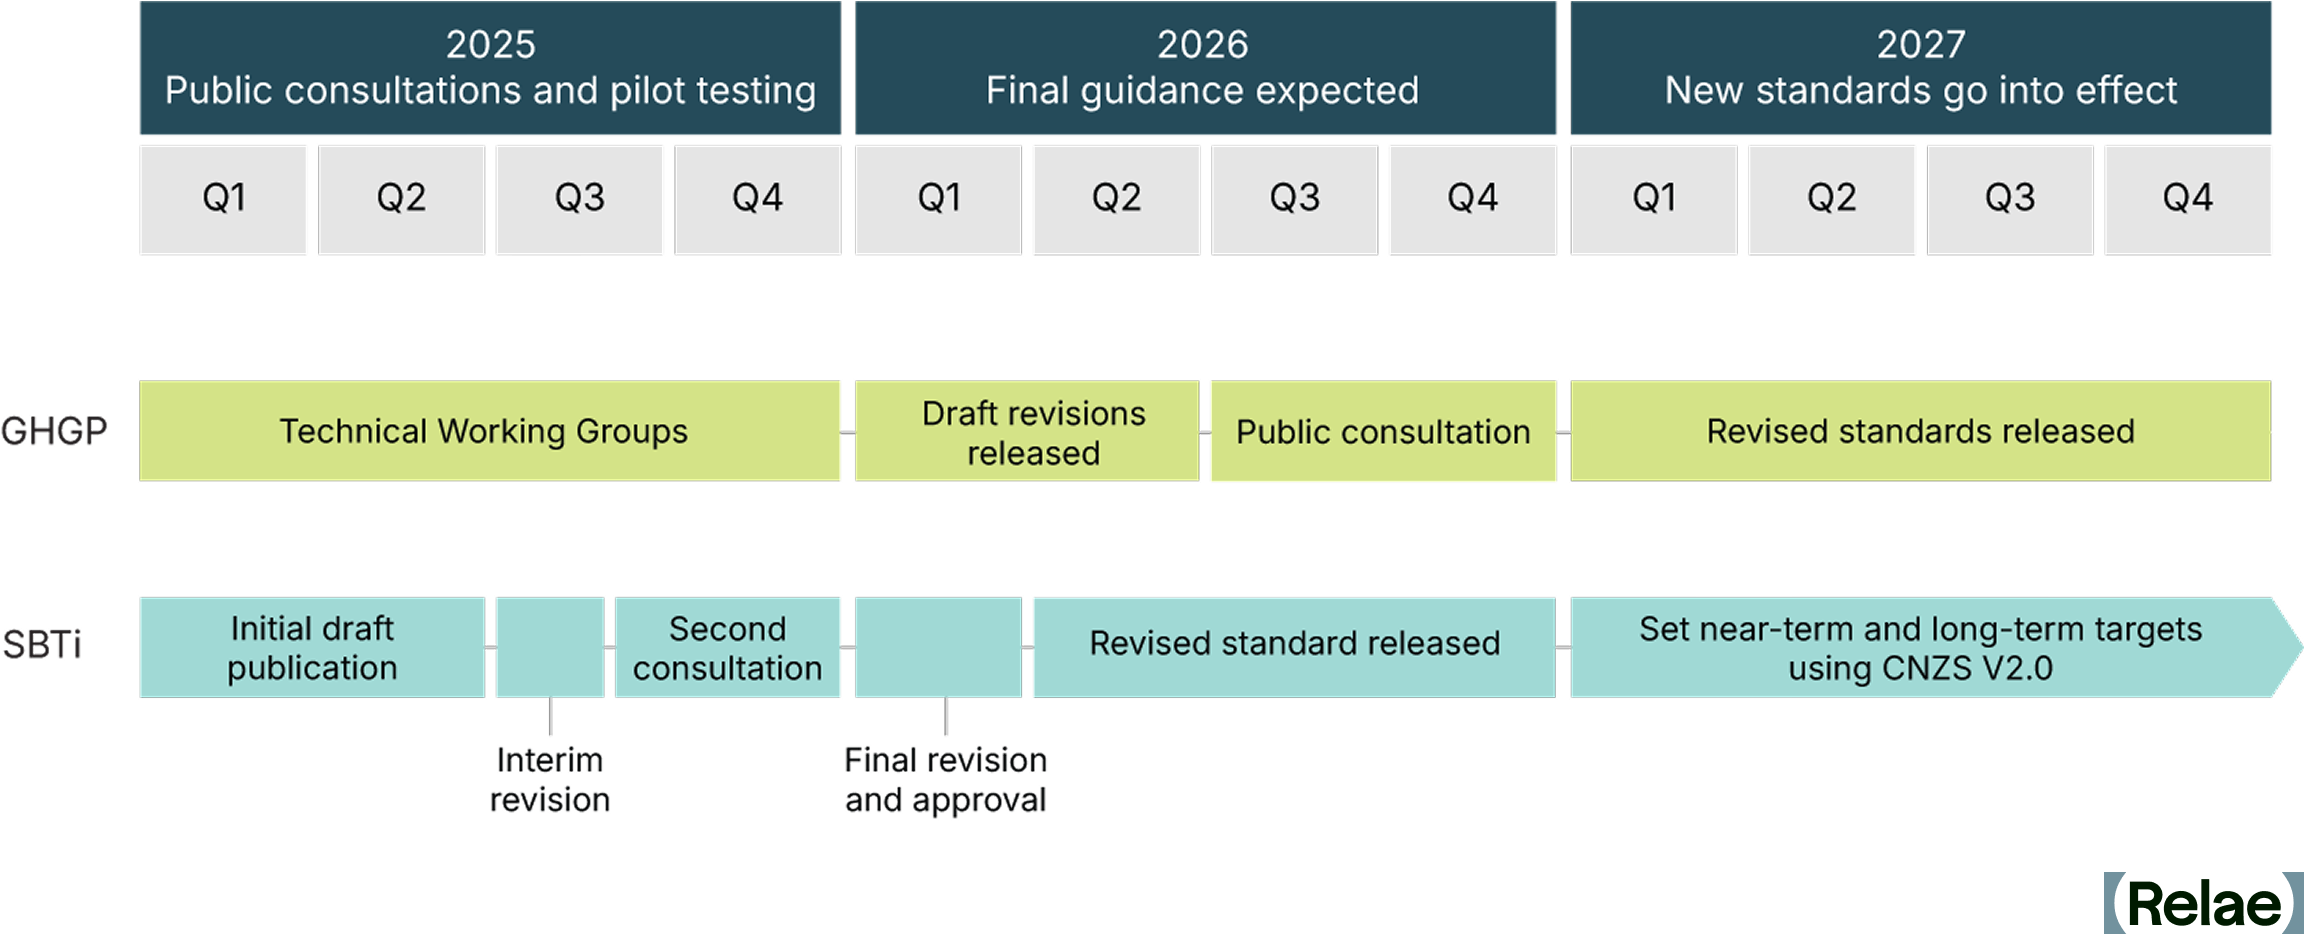
Timeline for Scope 2 Accounting Changes
Both the Scope 2 and Consequential Electricity-Sector Emissions consultations closed January 31, 2026, after GHG Protocol extended the original deadline. The GHG Protocol is analyzing feedback with a second consultation and final standards expected by 2027, though the exact timeline is still being finalized.
Companies are encouraged to participate in the public consultation. The GHG Protocol is asking for comments on critical questions, such as:
- Should proposed rules apply to energy consumers of all sizes?
- Which geographical boundaries should be used for locational matching?
- Should existing contracts be grandfathered in?
The public consultation period is an opportunity to shape the standards that will govern electricity-related emission accounting for years to come.
Why Act Now Instead of Waiting
With final rules still in development, companies with scope 2 emission reduction goals or science-based targets face a decision: Wait for clarity or act now.
Several factors favor early action:
- Inclusion of legacy contracts. "There are a lot of indications from the committees that existing long-term contracts will be grandfathered in," Pearce notes. The draft considers a legacy clause that would allow organizations to apply pre-existing contractual agreements, even if they don’t comply with new rules.
- Throttled renewable project development. Interconnection delays for new renewable energy projects, elimination of clean energy tax credits by 2028, and limitations on foreign materials needed to develop renewable energy project components mean that new REC supply may be harder to access in future years.
- Renewable project development timelines. "There's generally a lag, sometimes six to 18 months" between contract signing and project operation, Pearce explains. That means even if you sign today, the RECs won’t be generated for up to 18 months from the signing date.
- High-impact opportunity. Through careful project selection, renewable energy investment can go beyond the annual energy match requirement and incorporate additional impactful metrics, such as higher avoided emissions and positive social impacts.
Renewable Energy Buying Options for Companies
Previously, companies have been able to buy renewable energy through the following three paths; however, they all come with their own tradeoffs.
Traditional REC Buying Options
- REC spot markets make up most corporate renewable procurement. However, they mainly come from existing projects rather than financing new development, which is critical to expanding renewable energy supply to meet rising decarbonization needs.
- Virtual power purchase agreements (VPPAs) are highly impactful but require large power loads and the ability to manage long-term financial risks. Unavailable to most companies.
- Utility green tariffs have limited availability throughout the US (depending on the utility(s) that serve your load) and vary in quality.
Alternative REC Procurement Approach
For companies that want to go beyond the REC spot market and are not large enough to pursue a VPPA, there’s an alternative procurement option available: a high-impact forward REC contract. These multi-year contracts commit to purchasing RECs from specific new projects before they're built, providing the upfront revenue certainty developers need to secure financing at a fraction of the scale and complexity of a VPPA.
Comparing Renewable Energy Procurement Options
The Path Forward
Despite rapidly increasing grid demand, renewable project headwinds, and changing accounting rules, companies can still meet 2030 scope 2 goals.
What companies should do now:
- Watch for the next round of GHG Protocol consultation on Scope 2 revisions
- Evaluate forward REC contracts to lock in terms before rule changes
- Prioritize high-impact RECs that deliver measurable climate and social benefits
Shifting Playbook for Corporate Power Procurement
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s proposed scope 2 revisions would shift many large power buyers from annual renewable energy certificate (REC) accounting to 24/7 hourly matching and reveal a larger emissions gap than most inventories currently report.
- Of all the US grid regions modeled, the emissions gap between annual and 24/7 hourly matching is widest in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the markets where data center load is growing fastest.
- Relae's modeling quantifies the shift from annual to 24/7 hourly matching: serving a 4-gigawatt (GW) data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM, a roughly 800-megawatt premium in PJM that translates directly into cost and siting strategy.
- Closing that gap requires investments in clean, firm generation technologies, like natural gas with carbon capture and storage (CCS), battery storage, and geothermal. The optimal mix varies by market and load profile, which means modeling current and future emissions positions under 24/7 accounting to understand the best procurement options for a specific portfolio.
Annual REC Accounting No Longer Holds at Data Center Scale
For years, large corporate energy buyers have relied on a straightforward approach: purchase renewable energy certificates (RECs) or sign virtual power purchase agreements (VPPAs) to offset market-based scope 2 emissions. Under the current GHG Protocol guidance, these instruments allow companies to claim low or zero emissions regardless of when or where clean energy is actually generated. When corporate clean energy demand was modest, this fueled new renewable project development while aggregate grid emissions were trending down.
That approach worked, until now. Energy demand from data centers and hyperscalers is surging. The Federal Energy Regulatory Commission (FERC) reported more than 50 GW of data center capacity operating in the US at the end of 2025, much of it concentrated in regions where local clean generation cannot keep pace. When corporate clean energy demand was modest, the gap between contractual claims and physical generation was small enough that few questioned this argument. At hyperscaler levels, with load concentrated in a handful of grids, that gap is becoming too large to ignore.
From a climate perspective, well-designed renewable procurement has created real impact by channeling corporate capital into new clean generation, and reducing CO2 emissions anywhere to benefit the climate everywhere. From a grid perspective, power consumption and generation must balance in real time, and the flow of electricity is constrained by the physics of the transmission system. Some regulators, investors, and standard-setters argue that corporate clean energy claims should be grounded in this second, engineering perspective rather than the first. The GHG Protocol's proposed revisions reflect that view, and would force buyers to defend their claims against it.
Relae’s modeling of this 24/7 framework in PJM and ERCOT helps quantify its costs and emissions implications in the markets where the stakes are highest.
What Does 24/7 Hourly Matching Mean for Scope 2 Accounting?
The biggest proposed change to the GHG Protocol’s current Scope 2 Guidance is the move from annual power reporting and matching to a 24/7 approach. Instead of calculating emissions with an annual emissions factor (EF) based on their independent system operator (ISO) or eGRID region for each megawatt-hour (MWh) consumed, companies would need to use hourly-specific EFs.
Companies would still be able to retire RECs to reduce their market-based emissions. However, companies would need to show that these RECs came from clean energy that was generated on the same grid, in the same hour as their facilities consumed power. This makes annual, location-agnostic REC retirement, currently the dominant practice, insufficient for 24/7 market-based accounting.
Both the time restriction (hourly matching) and the location restriction (generation on the same grid as consumption) will make it more difficult for companies to retire RECs. For example, because today's methodology is location-agnostic, a New York-based company can retire RECs from a Texas wind farm (purchased unbundled or via a VPPA) to reduce its reported market-based scope 2 value. This has allowed renewable development to follow the best resource sites rather than the load. Similarly, the time of day that the wind farm generates energy is irrelevant, as long as it is approximately in the same calendar year.
Under the proposed revisions, retiring these RECs would no longer be acceptable for the New York company, since they would fail both location- and hourly-matching requirements. As a result, companies with large REC portfolios today may no longer be able to retire them in order to reduce their market-based scope 2 emissions, if the proposed revisions take effect. These companies may face significant unmatched consumption under 24/7 accounting, especially during evening peaks or grid stress events when fossil-based generation fills the gap.
Annual Matching vs 24/7 Hourly Matching
The figure below illustrates the gap between what a representative large buyer reports under the current annual location- and market-based methodologies, versus what an hourly 24/7 analysis reveals.
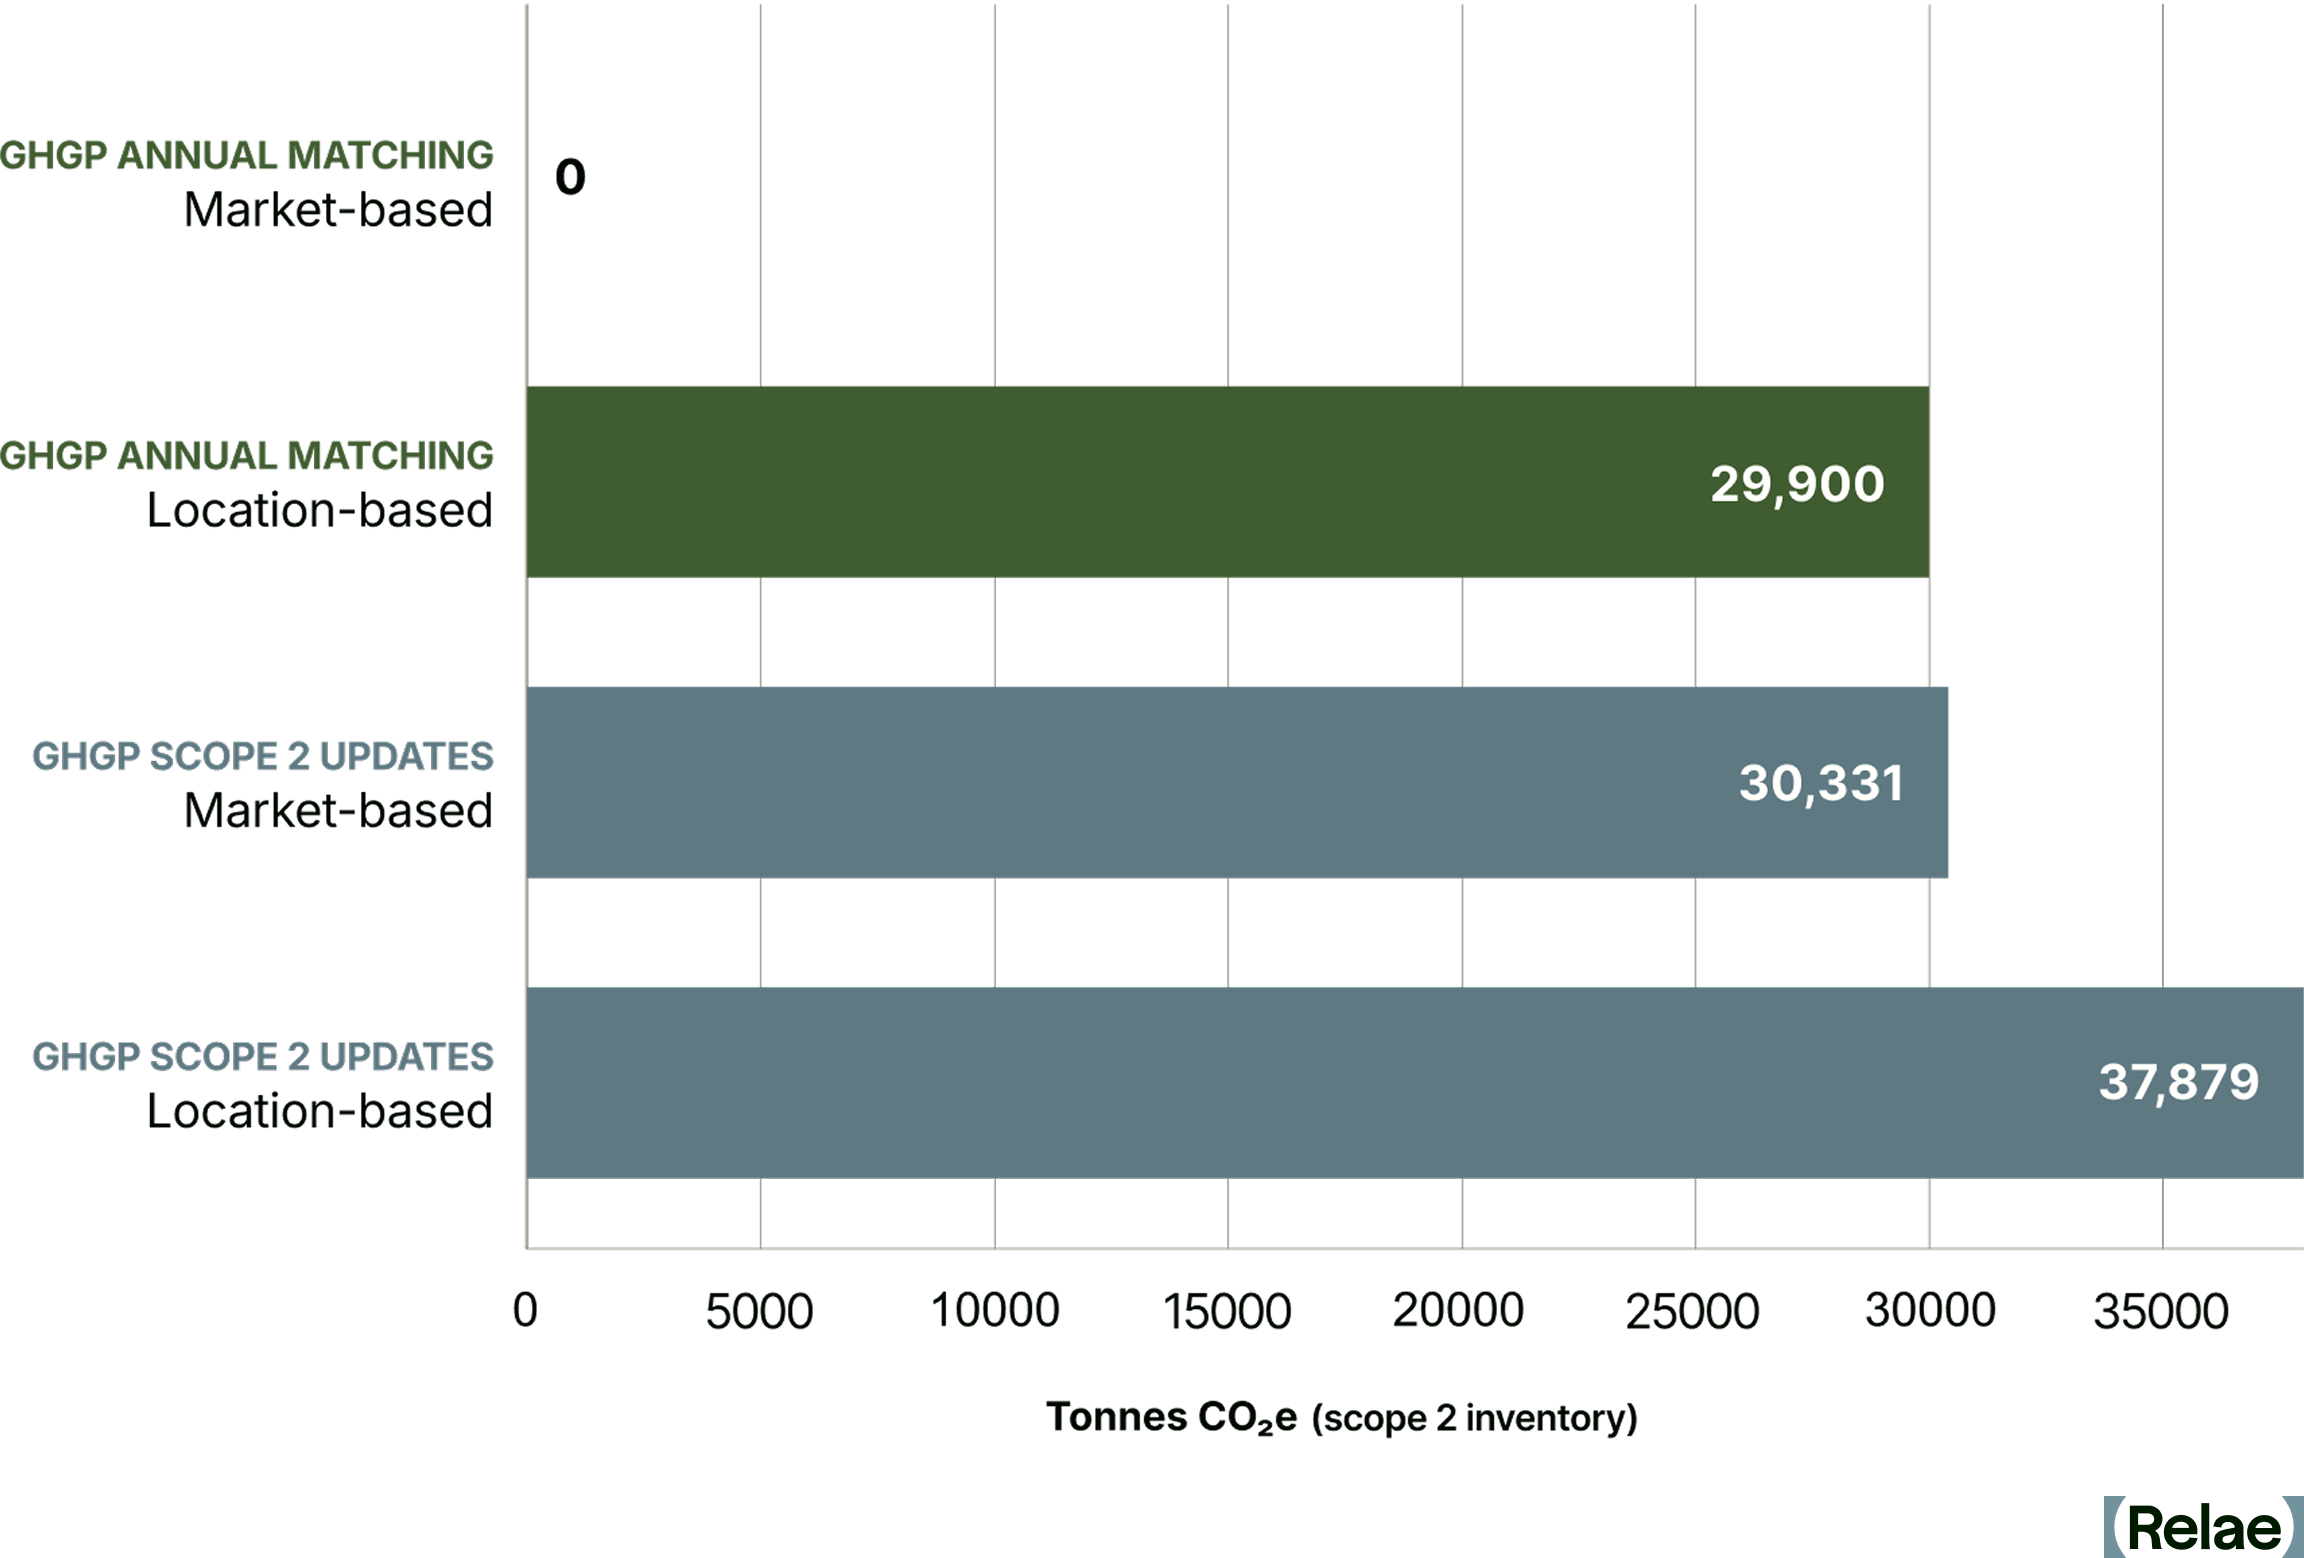
Understanding this emissions gap is the essential first step for buyers to make informed decisions about which instruments to retain, which contracts to renegotiate, and where new investment will matter most. If the proposed scope 2 revisions are enacted, companies procuring clean energy will be disincentivized from buying RECs sourced from variable renewables in distant locations, and instead will find it more favorable to invest in same-grid clean, firm generation, such as geothermal, nuclear, and renewables plus storage. RECs from these projects would qualify to be retired against market-based scope 2 emissions under the proposed revisions, where today's distant-wind or off-peak-solar RECs would not.
Where Pressure Is the Highest: ERCOT and PJM
Two markets stand out for projected hyperscaler load growth: PJM, which covers the extended mid-Atlantic region, and ERCOT in Texas. Both are on track to absorb massive increases in data center demand over the next decade, and both expose the limits of annual REC accounting in ways that will be hard to ignore under the new proposed framework.
PJM: 60% Fossil Generation Means High Marginal Emissions
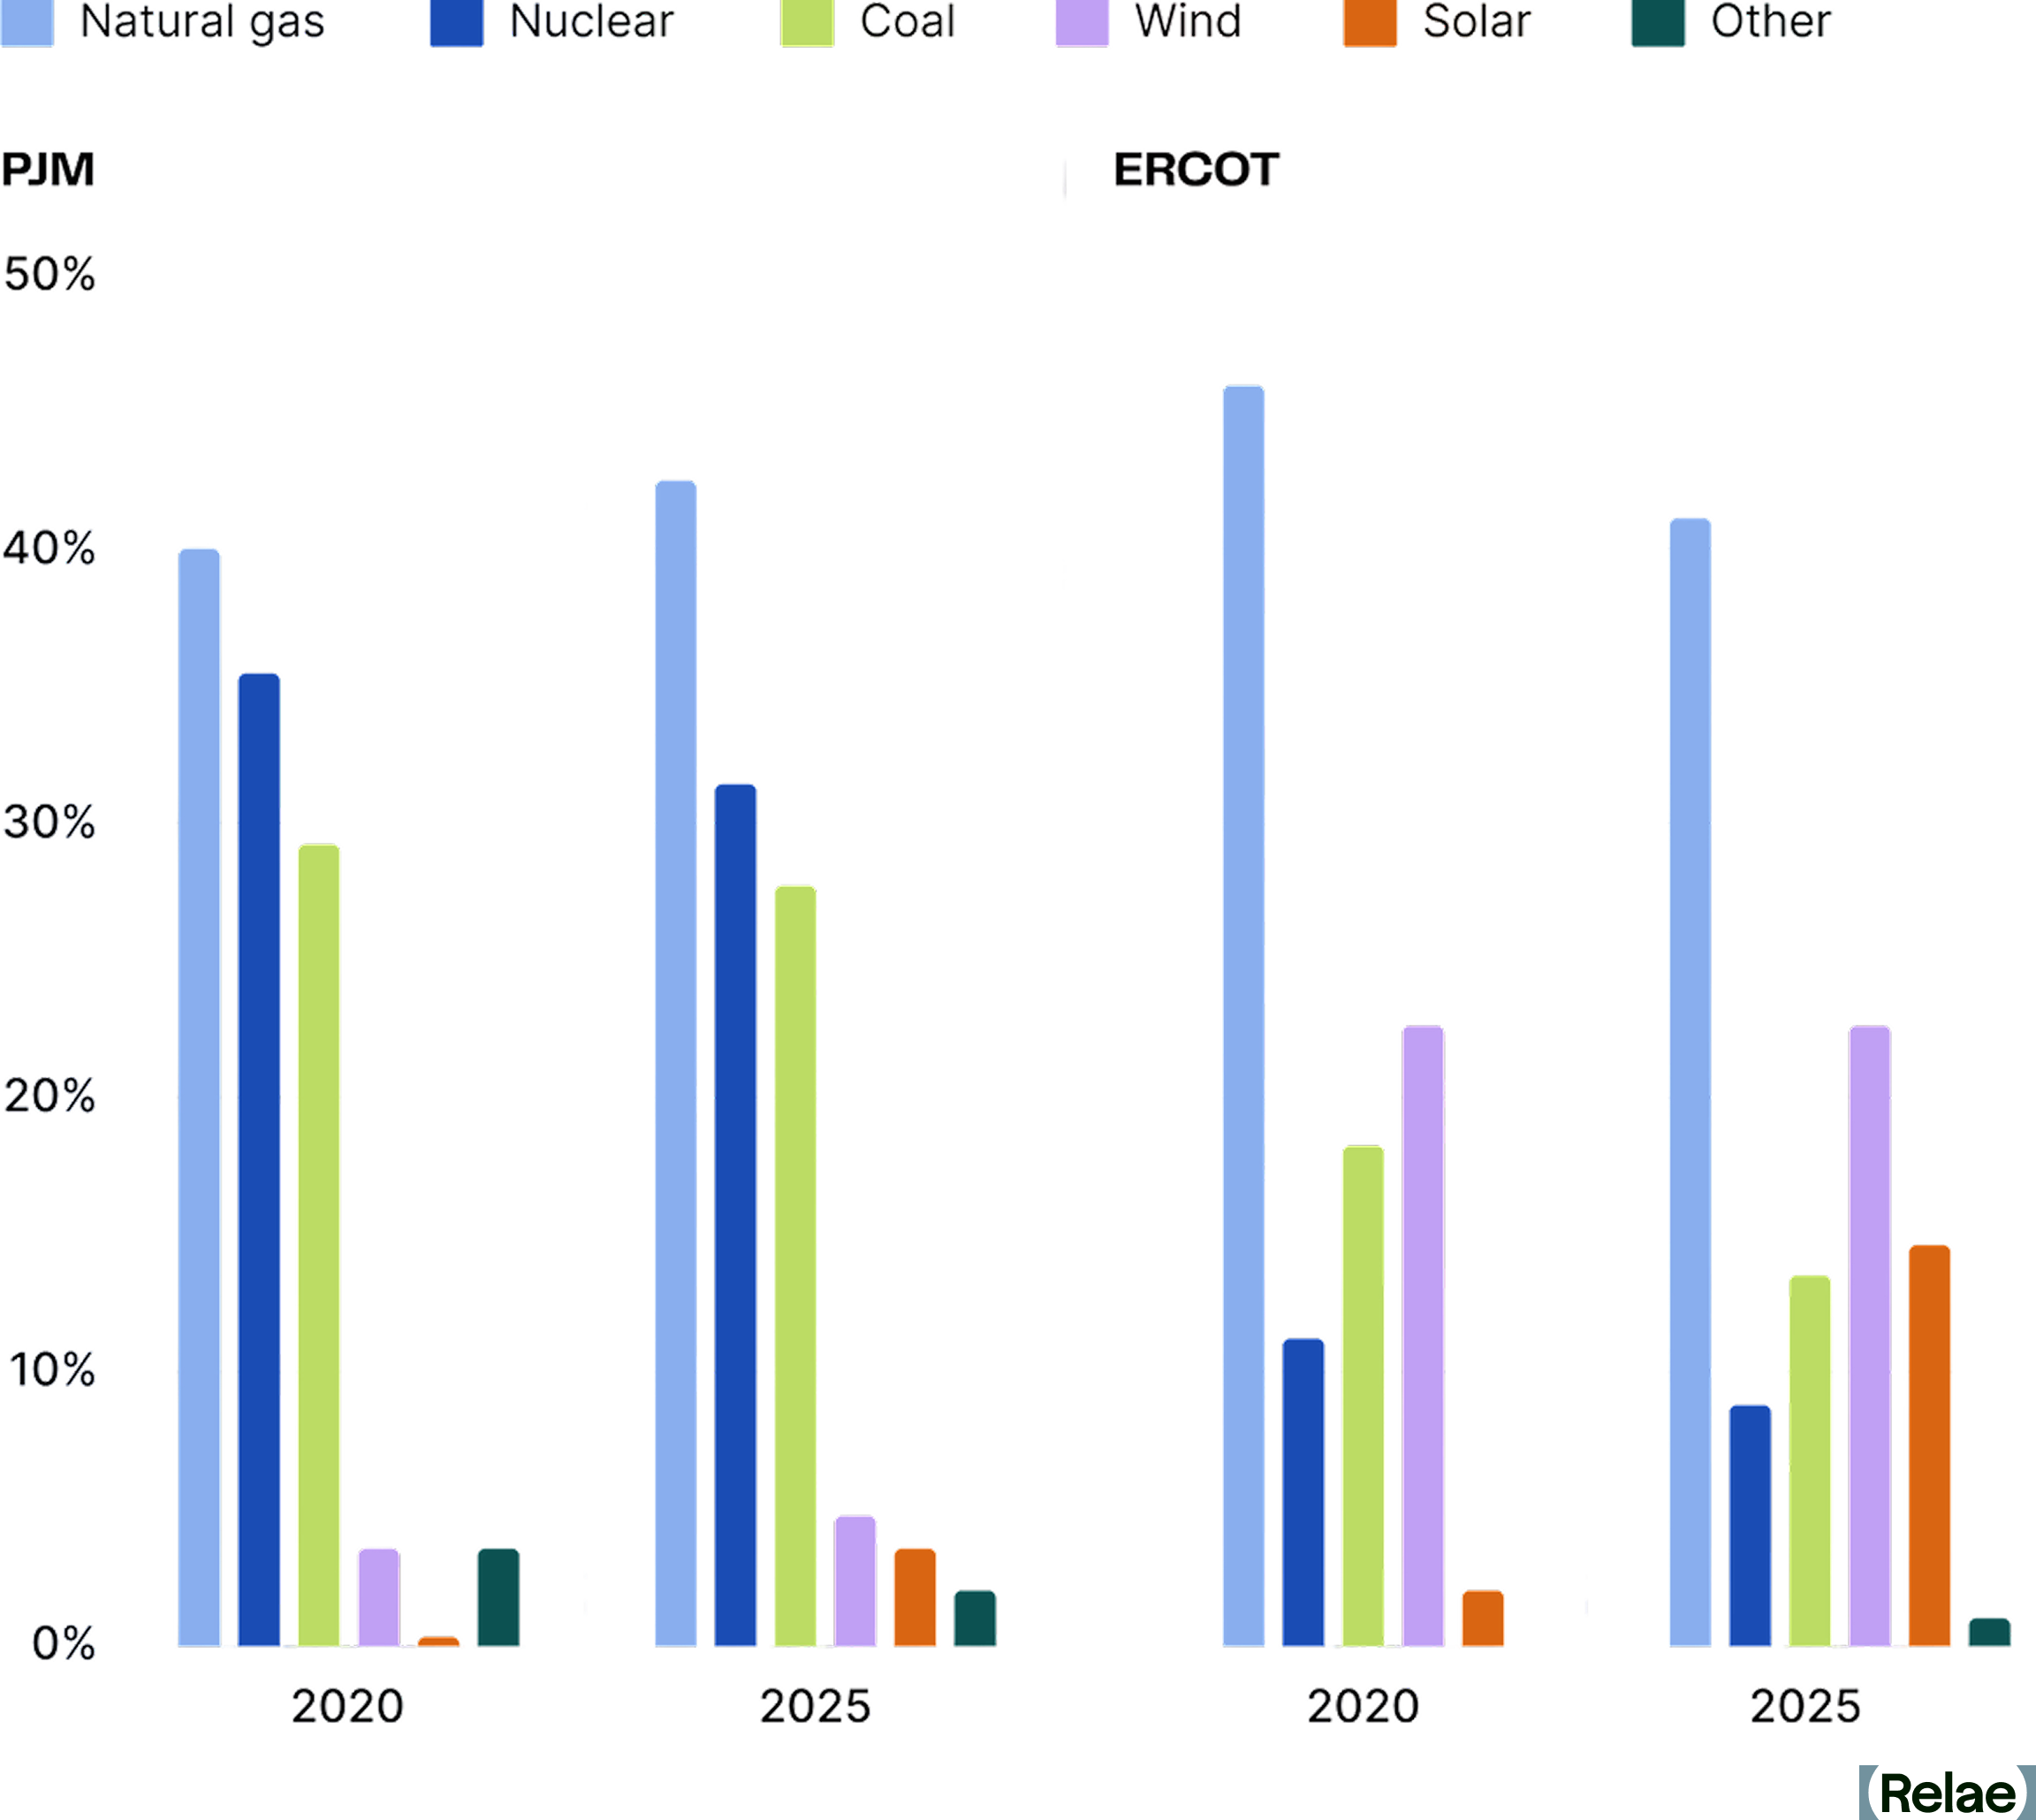
PJM is one of the largest and most complex wholesale electricity markets in the world. Its generation mix still includes 60% coal and natural gas, which means hourly emissions intensity remains high, particularly during evening peaks and grid stress events when fossil generation dominates the dispatch stack.
Buyers relying solely on annual REC retirement may show low market-based scope 2 emissions today, but a 24/7 analysis tells a different story. For PJM-based buyers, this means hourly matching gaps will be largest during evening and overnight hours, when nuclear and storage become disproportionately valuable relative to additional solar.
ERCOT: Solar and Wind Don’t Peak When Demand Does
Texas has abundant wind and solar, with solar generation growing nearly 7x since 2020, but those resources don’t always run when demand peaks. While fossil-based generation has declined since 2020, it still comprises more than half of ERCOT’s generation. Solar dominates midday, wind peaks in the evening, and natural gas fills the gaps, especially during high-demand evenings or extreme weather events.
Buyers with large ERCOT footprints may find that VPPA portfolios, which generate most of their clean energy in off-peak hours, already satisfy the proposed location-based test but fail on hourly matching. Battery storage and demand flexibility could help bridge the gap.
Figure 3 below quantifies that gap in both markets by showcasing the carbon-free energy (CFE) score in ERCOT and PJM, as well as the additional capacity required for a 4 GW load to achieve a 100% CFE target. The CFE score is the share of grid-supplied electricity in a given hour that comes from carbon-free sources, and is the metric the proposed scope 2 revisions would use to evaluate hourly matching. A 100% CFE target means electricity consumption is matched to carbon-free generation in every hour of the year.
In the left panel, a representation1 of each market's 2030 hours are sorted by grid (CFE) score, from the dirtiest hour on the left to the cleanest on the right. Neither grid approaches 100% carbon-free on its own, and the shaded areas represent the unmatched hours a buyer claiming 100% clean energy through annual instruments would actually carry under 24/7 accounting. The gap is the maximum unmatched hours a buyer might be exposed to, as some RECs procured through annual matching may qualify under the new rules, if satisfying the locational and hourly requirements.
The right panel translates that gap into action. The additional co-located clean generation and storage required to serve a representative 4 GW load (roughly 5% of the forecast 2030 C&I load in ERCOT and 4% in PJM) at a 100% hourly CFE target, on top of what the underlying grid already provides.
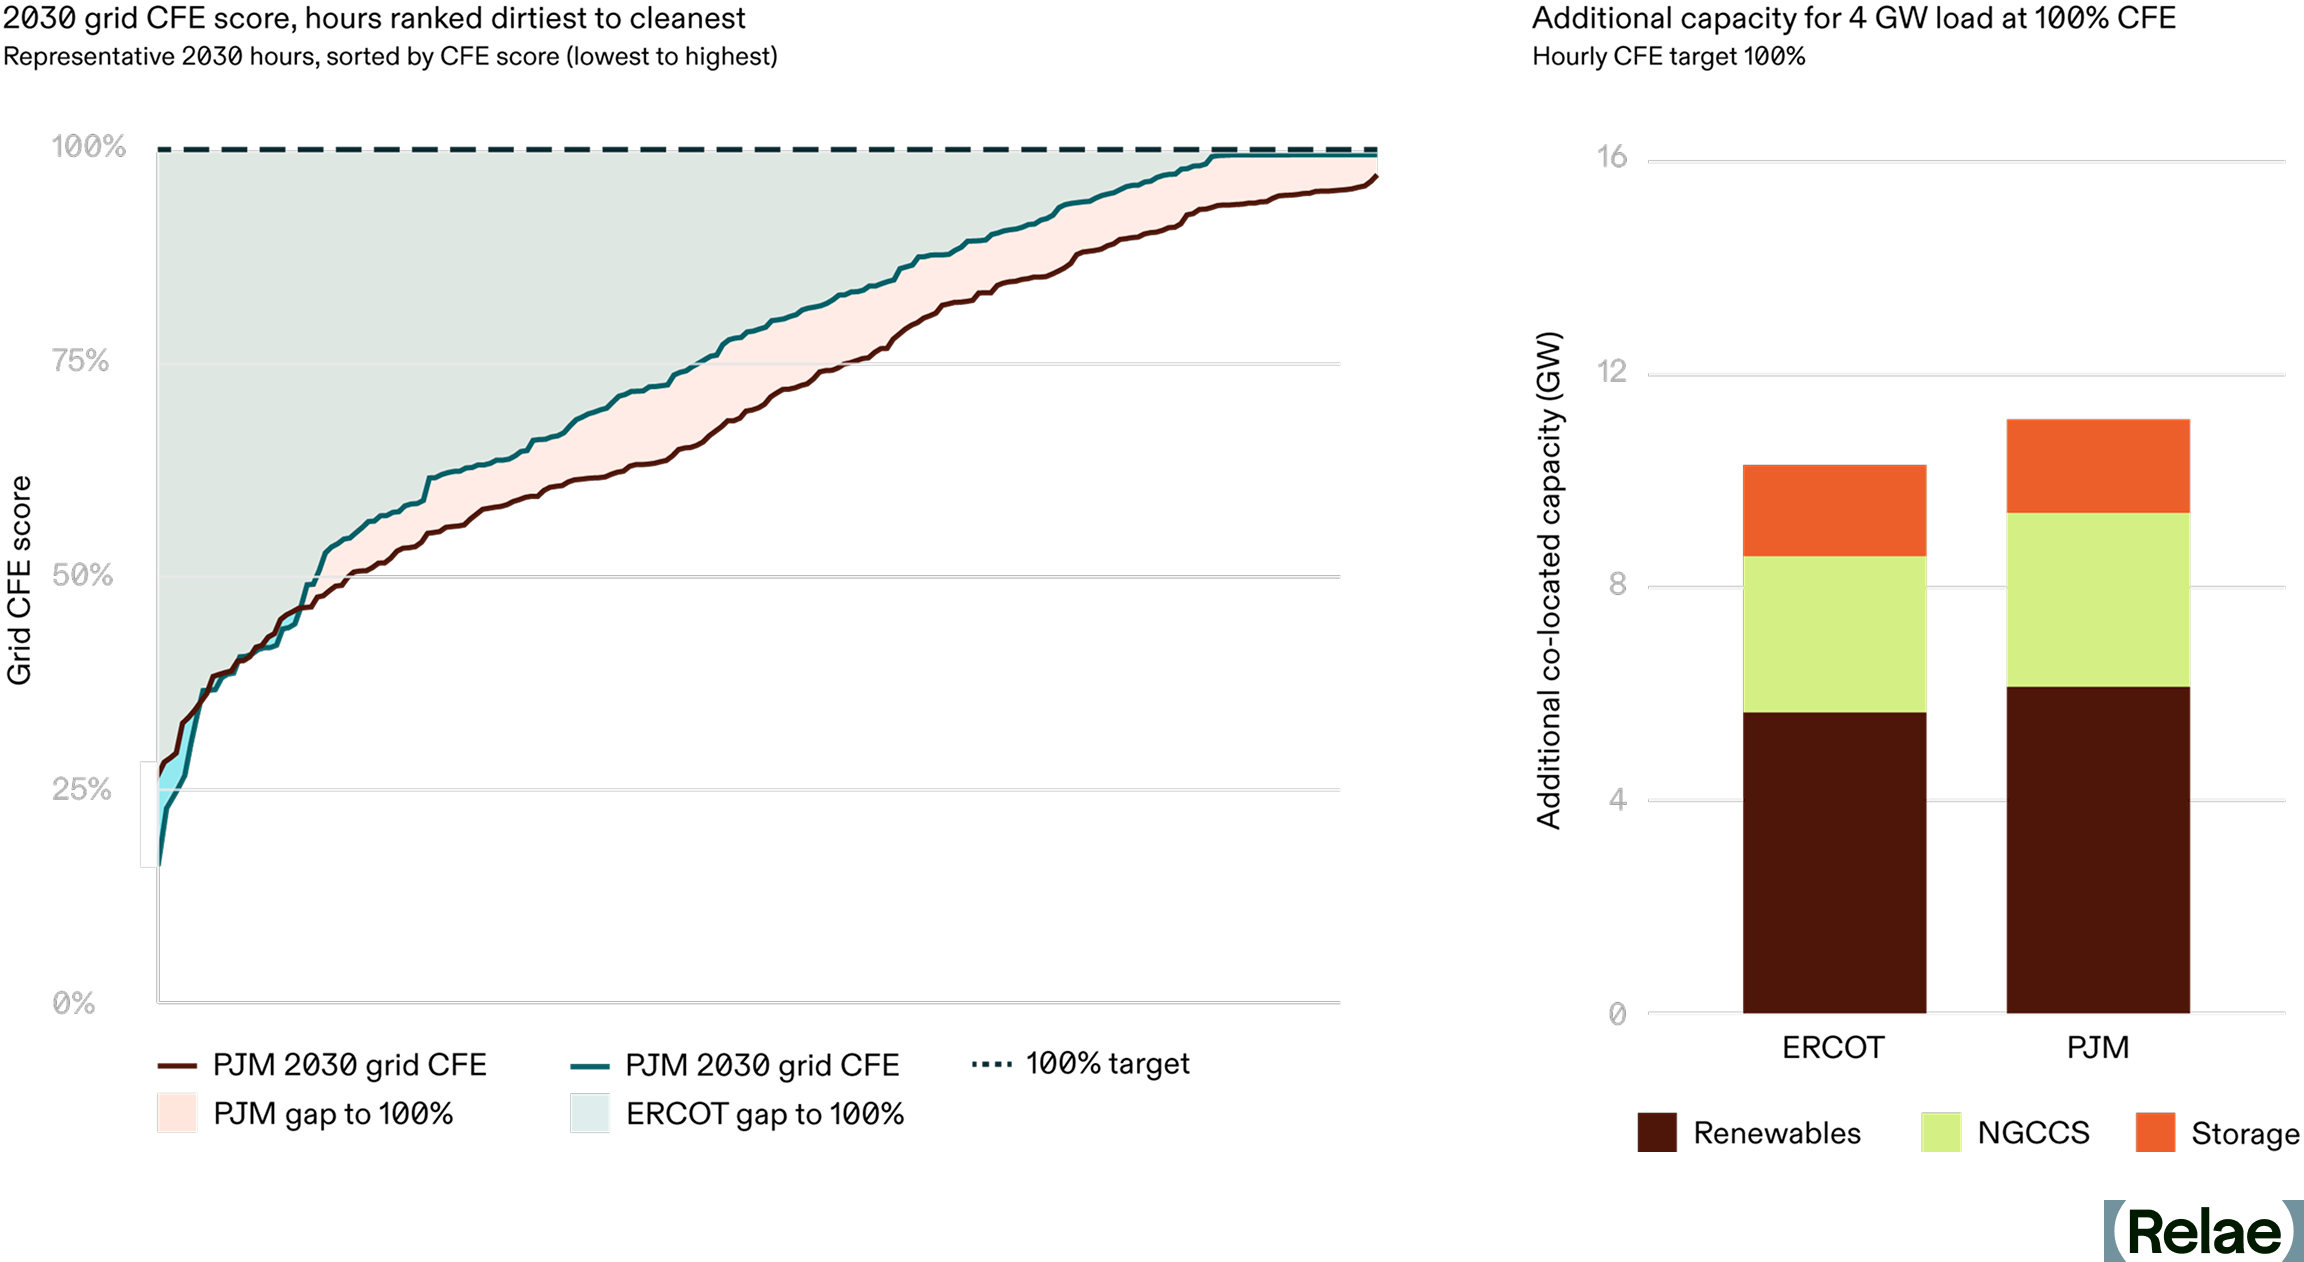
A few patterns are worth highlighting. First, the left panel confirms that PJM’s grid will still spend materially more hours below 100% carbon-free than ERCOT’s in 2030, a direct consequence of the coal- and gas-heavy generation mix described above. Notably, ERCOT's curve reaches 100% in a meaningful share of hours (windows when the grid is running entirely on carbon-free resources), while PJM's never does, meaning some fossil generation is dispatched in every hour.
Second, the ISO a buyer operates in drives a meaningful difference in build-out: hitting 100% hourly CFE for a 4 GW load takes 9.6 GW of additional capacity in ERCOT and closer to 10.5 GW in PJM. This indicates the advantage of achieving hourly and locational matching in already clean grids, which may influence a buyer choosing where to site new workloads.
Renewables have the largest share of the additional capacity in both markets (5-6 GW), paired with significant long-duration energy storage (~2 GW), while natural gas with CCS provides meaningful clean, firm capacity (~3 GW). ERCOT’s storage share of capacity is slightly larger, reflecting the midday-solar/evening-load mismatch, while PJM leans a bit more on natural gas with CCS, where clean, firm generation does more of the heavy lifting due to lower wind speeds and solar irradiance than Texas.
The right panel also illustrates why clean, firm technologies (natural gas with CCS, advanced nuclear, and enhanced geothermal) are likely to be included alongside renewables and batteries in any serious 24/7 portfolio. With only renewables and batteries, hitting the same target requires about double the total generation and storage capacity. In both markets, targets that look achievable today on an annual REC basis will require materially more capital and a different mix of resources, under 24/7 accounting.
Top Questions Large Power Buyers Need to Model Before the Rules Change
The GHG Protocol revisions are not finalized, and the timing of any mandate remains uncertain, which is exactly why modeling cannot wait.
A useful self-test for any large power buyer is: can your team answer the following today with defensible numbers?
- What is your hourly CFE score across your largest load centers, and how far does it sit from your reported market-based emissions?
- Which of your existing VPPAs and REC contracts hold value under 24/7 accounting, and which become effectively stranded?
- What mix of resources delivers the incremental clean, firm capacity that closes your gap in PJM, ERCOT, or wherever your load is concentrated at the lowest cost?
- If your next gigawatt of load were sited in a different ISO, how would your emissions position change?
Clean firm projects do not appear off the shelf. Advanced nuclear, enhanced geothermal, and natural gas with CCS all carry multi-year development timelines, and corporate offtake agreements are often what get these projects financed in the first place. Buyers who engage now help shape the project pipeline that will be available in their target markets in 2030, and can lock in offtake terms before competition for the most valuable sites tightens. Buyers who wait until the methodology is final will be working with shorter lead times, fewer development partners, and less leverage to specify projects that fit their load profiles and hourly matching needs.
Frequently Asked Questions
What is 24/7 hourly matching, and how does it differ from today's REC accounting?
Today's scope 2 accounting lets companies retire renewable energy certificates (RECs) from any grid, at any time of year, to offset their emissions. The GHG Protocol's proposed 24/7 hourly matching would require RECs to come from clean generation on the same grid, in the same hour a facility consumes power, making most of today's location-agnostic RECs ineligible for market-based accounting.
Why are PJM and ERCOT under the most pressure from this shift?
Both markets are absorbing the fastest-growing data center load in the country, and both still lean on fossil generation to meet demand outside peak renewable hours. PJM's generation mix is 60% coal and gas, while ERCOT's solar and wind often don't peak when demand does, so buyers in these markets face the largest gaps between their annual REC claims and their actual hourly carbon-free energy score.
How much additional clean capacity does it take to close the gap?
Relae's modeling finds that serving a 4 GW data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM. That capacity mix leans on renewables and long-duration storage in both markets, with natural gas with CCS playing a larger role in PJM, where wind and solar resources are weaker.
What should power buyers do before the GHG Protocol revisions are finalized?
Start modeling now. Buyers should know their hourly carbon-free energy score, understand which existing VPPAs and REC contracts hold value under 24/7 accounting, and identify the lowest-cost mix of clean, firm resources that closes their gap. Clean firm projects like advanced nuclear, enhanced geothermal, and natural gas with CCS take years to develop, so buyers who engage early have more influence over the project pipeline and better offtake terms.
Modeling the 24/7 Emissions Gap with Relae
For large power buyers assessing what the proposed GHG Protocol revisions mean for their power procurement portfolio, Relae's Advanced Power Emissions Analysis solution models the gap between current market-based reporting and what 24/7 accounting would reveal—by market, load profile, and technology stack.
AI Scale and Climate Commitments: A 2026 Outlook
The AI and Climate Execution Challenge
Data center energy capacity in the US is projected to increase from 25 GW to 120 GW by 2030—a fivefold increase. Hyperscalers are projected to invest $7 trillion globally in data center infrastructure through 2030, with approximately $2.8 trillion invested in the US.
While 2025 was defined by a 'scale at all costs' scramble for compute, in 2026, the new mandate is responsible scale: reconciling voracious power demands with aggressive net-zero commitments and rising energy costs.
Grid constraints determine the geography and velocity of growth, forcing companies into complex trade-offs between speed-to-market and “clean, firm” power, which can take years to develop. Evolving carbon accounting rules are shifting procurement strategies and infrastructure choices at this trillion-dollar scale, creating a “carbon debt”—embodied emissions that will stay on the books for decades. In 2026, the competitive advantage likely belongs to those who integrate power, hardware, and climate strategy from day one.
Powering AI: Grid Reliability, Constraints, and Interconnection
Grid infrastructure faces reliability challenges from aging systems and capacity constraints. Interconnection queues stretch three to five years for renewables, while large electrical load interconnection lacks consistent standards.
Federal Regulatory Response
The federal government is moving to standardize these processes, with a critical decision point in 2026. For companies planning data center deployments in 2026, understanding these regulatory shifts is likely essential to realistic timeline and site selection planning.
On October 30, 2025, the US Department of Energy (DOE) leveraged Section 403(a) of the DOE Organization Act to direct the Federal Energy Regulatory Commission (FERC) to issue a rulemaking to “ensure efficient, timely, and non-discriminatory load interconnections” for large (>20 MW) electrical loads.
By April 30, 2026, FERC is expected to issue a final rule on large electrical load interconnections for grid operators, providing federal regulations for approval pathways, timelines, and rates.
Public comments on DOE’s advanced notice of proposed rulemaking were due on December 5, 2025, and grid operators, utilities, NGOs, and customers submitted over 150 comments reflecting a wide range of perspectives.
While federal standardization should reduce procedural uncertainty, it doesn't create new grid capacity. Even with clearer approval pathways, the underlying supply-demand mismatch remains a primary gating factor for growth.
Bridging the Supply-Demand Gap
Data center energy demand is surging, but new clean electricity generation takes years to build. This mismatch between accelerating demand and slow-building supply is forcing the industry to pursue solutions on two timelines: near-term load flexibility strategies that unlock existing capacity, and long-term generation investments that build new power supply.
Load Flexibility: Near-Term Grid Access
Load flexibility is emerging as a possible path to faster grid connection. Oracle, NVIDIA, Emerald AI, and Salt River Project's joint research demonstrated 25% power reduction during peak hours through workload tiering. The demonstration shows that if data centers reduce consumption during peak times (roughly 1% of the year), it unlocks 126 GW of currently constrained capacity that could be available now.
Large power loads increasingly face incentives or mandates to demonstrate flexibility as part of interconnection agreements, making this an access requirement, not an optional efficiency measure. For example, Senate Bill 6 in Texas mandates that data centers and other large loads must reduce their consumption during certain grid peak times. Many other state legislatures are passing legislation that will impact data centers.
Storage has shifted from smoothing renewables to enabling multiple strategies: making intermittent renewables firmer, providing grid reliability services, and supporting 24/7 matching. Storage may emerge as a solution to allow data centers to reduce grid consumption during peak hours while maintaining operations.
Relae helps clients design load flexibility strategies under evolving regulatory frameworks: evaluating behind-the-meter generation options, sizing storage for peak reduction scenarios, and structuring interconnection configurations that preserve optionality across accounting methodologies.
Clean Firm Power: Long-Term Generation
Hyperscalers remain committed to clean, firm generation that’s reliable: power that's both low-carbon and dispatchable 24/7. Natural gas with carbon capture and storage (CCS) is emerging as a critical bridge technology. Google's 400 MW CCS power agreement with Broadwing, expected online in 2029, demonstrates commercial demand at scale.
In our analysis evaluating CCS pathways, commercial viability depends on rigorous assessment of permitting timelines, capital and operating costs, storage geology, vendor compatibility, and 45Q tax credit optimization. Execution has been most prevalent where technology intersects with regulatory approval and storage access.
Hyperscalers are also investing across geothermal, nuclear, including Small Modular Reactors (SMR), hydrogen, and fusion. Long-duration energy storage has also been an area of focus. Each has different risk profiles and opportunities across technical maturity, permitting, commercial viability, emission accounting methodology, dispatchability, and political support.
Evaluating these pathways requires multi-dimensional frameworks. Each technology faces distinct challenges: SMRs struggle with execution complexity, geothermal with extended development periods, and hydrogen with production-dependent carbon intensity. Tax credit eligibility (particularly 45Q for CCS and 45V for hydrogen) significantly impacts project economics.
Both power generation and data center Infrastructure site selection require integrating environmental and social vulnerability data to avoid community conflicts that delay or stop projects.
Power Accounting Rules Determine Clean Energy Procurement
The Greenhouse Gas (GHG) Protocol extended the public consultation period for proposed scope 2 guidance changes to January 31, 2026. The results will determine clean energy procurement strategies and the carbon value of load flexibility for the next decade.
The proposed shift in electricity emissions accounting could increase clean energy procurement costs for buyers. The accounting methodological debates matter for hyperscalers: 24×7 energy matching versus carbon matching. The issues of deliverability (being located in the same grid region) and additionality (being new, rather than repurposed, generation) are also hotly debated.
These different frameworks strongly influence whether natural gas with CCS, nuclear, geothermal, or battery-backed renewables are considered optimal for a site, and whether load flexibility has carbon value.
Companies need to model scenarios across advanced power emissions methodologies, evaluating portfolio costs and carbon performance before final standards are published in 2027. Companies are also signing forward renewable energy certificate contracts (RECs) and structuring power purchase agreements (PPAs) now to preserve optionality across scenarios.
AI Infrastructure Emissions at Scale
Data center construction creates substantial scope 3 emissions, and their relative importance depends on grid carbon intensity. For facilities powered by average-carbon grids, scope 2 operational emissions dominate. But for data centers powered by very low-carbon electricity (renewables or nuclear), scope 3 embodied emissions can represent 40% of total lifetime greenhouse gas emissions.
In AI data centers, IT equipment drives the majority of embodied emissions. Chips and memory account for 67%, followed by structural materials at 17%, with server power supplies, aluminum, and other components comprising the final 16%.
Direct procurement of low-carbon materials faces constraints: limited supply, geographic concentration, and contracting complexity. Environmental Attribute Credits (EACs) provide an interim pathway by decoupling environmental benefits from physical materials, but require rigorous quality standards and verification to ensure real emissions reductions.
Our high-quality EAC criteria, developed with Microsoft, establish standards that separate market-making from greenwashing. Levelized Cost of Carbon Abatement frameworks make materials decisions comparable to power decisions, treating infrastructure decarbonization as portfolio optimization, not separate workstreams.
Carbon Removal: Addressing Residual Emissions
Complete supply chain decarbonization by 2030 isn't feasible. Despite aggressive efforts to procure clean power and reduce construction emissions, residual emissions will remain significant. For hyperscalers with net-zero commitments, carbon dioxide removal (CDR) has shifted from an optional component to a structural necessity. Microsoft remains the world's largest CDR buyer, and Google increased purchases 14-fold from 2023 to 2024.
CDR credit quality varies widely. Companies must apply science-based principles to evaluate credits. Our Criteria for High-Quality CDR, developed in collaboration with Microsoft, establishes six science-based principles for evaluating credits—critical as emerging hyperscaler and other corporate demand high-integrity supply.
AI and Climate: Looking Ahead
The window for strategic maneuvering is narrow. The AI infrastructure buildout is happening now, and the decisions made in 2026 will impact a company’s cost structure and carbon profile for years.
Companies treating power, infrastructure, and decarbonization as separate workstreams will face compounding constraints. The winners of the AI era will be those who integrate power, infrastructure, and carbon strategy into a single, cohesive system.
Top Questions on FERC's Co-Location Compliance Order for PJM, Answered
Key Takeaways
- On April 16, 2026, two weeks before the Department of Energy’s (DOE) April 30 deadline for action on the Large Load Proceeding, FERC, the Federal Energy Regulatory Commission, provided a significant update:
- FERC issued its compliance order on PJM's Bring Your Own Generation (BYOG) tariff; the order approved four interconnection paths, rejected two PJM proposals, and directed PJM to refile by May 18.
- FERC's June 2026 order settled a key question around enforcement mechanisms for co-located projects. FERC rejected PJM's Two-Strike proposal (which would have terminated contracts on second violation), allowing only penalties and suspension from the three new transmission services, materially reducing developer downside risk.
- Notably, BYOG arrangements built on the rejected elements of the compliance filing face restructuring risk before that refile. For deals that clear it, however, energization could begin as early as this summer.
- These proceedings reflect the underlying industry concerns about speed, reliability, and cost equity, shifting the risks and costs of new generation from ratepayers to the large loads, such as data centers, themselves.
- Developers, investors, and project teams can use quantitative grid and load modeling to navigate these risks successfully, converting regulatory exposure into priced engineering decisions.
A New Rulebook for Bring Your Own Generation in PJM
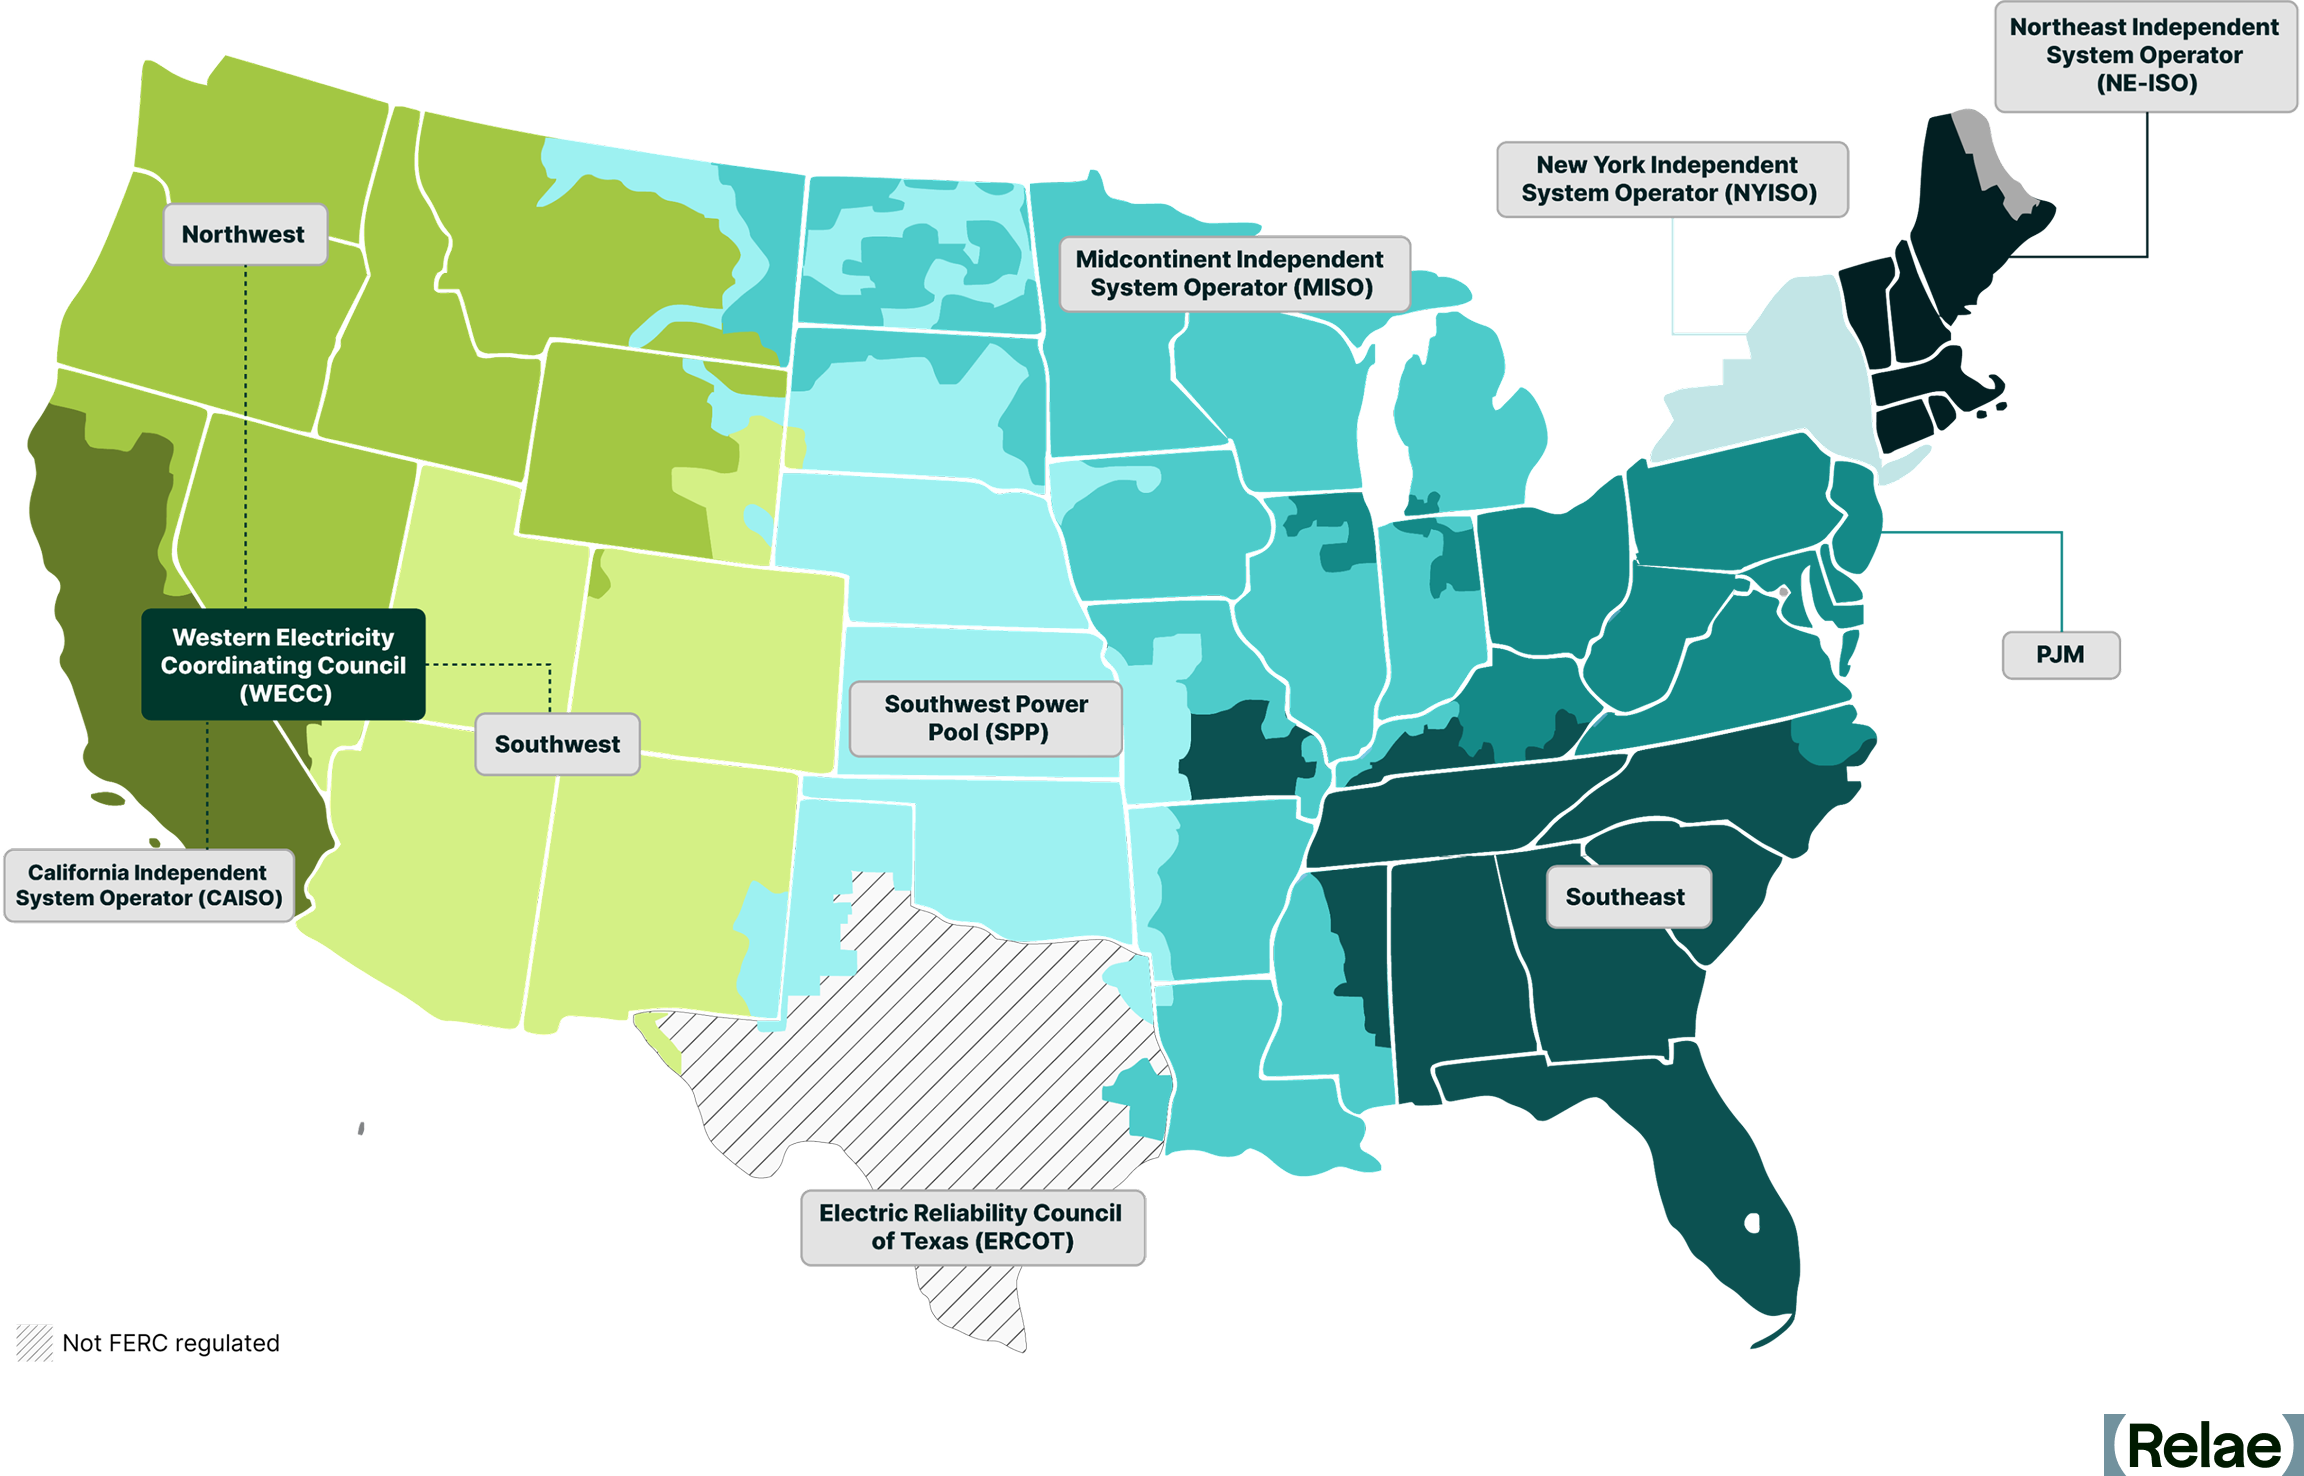
PJM Interconnection (PJM) hosts the highest concentration of data center load growth in the US, managing regional transmission across 13 states in the Eastern US, and commercial operation dates for new generation projects in its current interconnection queue stretch into the early 2030s. Bring Your Own Generation (BYOG) has become the fastest speed-to-power path around that bottleneck.
BYOG allows large loads, such as data centers, to draw power directly from a co-located generation source connected to the bulk power grid, enabling developers to avoid lengthy interconnection queues and costly transmission upgrades, while drawing limited to no power from the bulk power grid.
The Federal Energy Regulatory Commission’s (FERC) April 16 order is now the rulebook that governs the tariffs that facilitate these BYOG arrangements. Any deal built on the paths FERC closed off must now find a way to align with one of the four approved mechanics before PJM's May 18 compliance refile. Deals that clear the refile could begin to energize as early as this summer.
Below are the top questions the Relae power advisory team is fielding most from hyperscalers, large commercial power buyers, and power producers navigating the mechanics of PJM’s BYOG tariff and the engineering realities of running a co-located project.
What Is Co-Location?
Co-location refers to a power generation facility sited in close proximity to a large load, such as a data center, that interconnects directly to the bulk power grid. The generator serves that load contractually via a power purchase agreement (PPA), with power flowing through the meter.
BYOG is the predominant co-location model in PJM. Under a typical BYOG arrangement, on-site generation covers the majority of the data center's load (~90%), with only a small residual portion (~10%) supplied from the grid. Each co-located project effectively functions as its own mini-grid, with explicit operational obligations that are less forgiving than standard transmission service (NITS).
Why Did FERC Keep Behind-the-Meter (BTM) and Co-Location Separate?
While BTM and co-location may look similar, they sit in different regulatory buckets. That said, the line between them is less clear-cut than it once was. FERC found existing BTM rules inadequate to address the grid impacts of large co-located loads and directed PJM to treat co-location as a distinct framework.
At the same time, BTM rules, including how tariffs and distribution charges are applied, remain under revision in a separate PJM proceeding. The two tracks moving in parallel have contributed to the conflation of the frameworks in industry discussion.
How Does Co-Location Differ from BTM Generation?
- Co-location, as this order defines it, is a bulk grid-interconnected arrangement. The host generator remains on the same interstate grid, maintains its interconnection service agreement, and continues exporting power to the grid. The co-located load connects through an approved interconnection mechanic and takes transmission service under a PJM tariff product.
- BTM is a distinct arrangement. The generator sits on the consumer's side of the utility meter and serves the load through a private line, without an interconnection agreement. The load may typically have a grid connection; however, in some circumstances, the generation may be fully off-grid or islanded. By setting a megawatt (MW) threshold for BTM, larger loads with co-located generation may no longer net out their load to reduce transmission and grid charges. FERC's jurisdiction over a BTM arrangement is narrower, and the tariff mechanics that apply to co-location do not apply in the same way.
FERC's rejection of PJM's proposed BTM rule changes illustrates this distinction. The commission is keeping the two categories separate on purpose. Ultimately, FERC’s intention seems to signal that large loads co-located with generation may not be adequately reflected in grid and transmission upgrade costs when these assets are behind the meter. Historically, BTM assets were exempt from these costs because their relatively insignificant power contributions had no meaningful financial impact on the bulk power grid.
That said, the BTM track is still moving. PJM's BTM application rules, including the netting-off mechanism that lets BTM loads avoid utility tariffs, remain under review in parallel proceedings.
For developers, regulatory clarity on co-location and BTM is increasingly critical. In April 2025, FERC upheld its rejection of the Talen-Amazon Susquehanna nuclear BTM interconnection agreement proposal, declining to rehear arguments on the initial decision. To many experts, the split ruling signaled that the structure of PJM’s interconnection service agreement (ISA) is inadequate for large loads operating behind the meter.
However, in the initial challenge to the Talen-Amazon proposal, utility companies argued that the arrangement would unjustifiably shift transmission costs to other PJM customers. Ultimately, in June 2025, Talen Energy entered into a 1,920 MW, front-of-the-meter power purchase agreement with Amazon Web Services, which does not require FERC’s approval.
FERC Has Always Regulated Generators, Not Loads. What Changed?
The April 16 order lands inside a larger jurisdictional shift. FERC does not typically regulate load interconnection; its authority sits with the bulk power grid. Under Orders 888 and 2003, FERC has regulated how generators connect to that system (with standardized study deposits, readiness requirements, and withdrawal penalties) while load interconnection has historically been regulated at the distribution level under state jurisdiction.
That generation-only approach to FERC regulation worked for three decades. Now, the scale of AI data centers and other large loads creates interstate impacts that state-level load regulation cannot fully address. Generation co-location breaks the pattern by routing the load through a FERC-regulated generator interconnection agreement rather than a state-regulated load-serving entity, pulling it into federal jurisdiction.
In December 2025, FERC declared PJM's existing interconnection rules (tariff) unjust and unreasonable in the PJM Co-Location Order and directed PJM to revise the tariff. The April 16 order is FERC's review of that rewrite.
As FERC Commissioner David Rosner wrote in his concurrence to the December 2025 PJM Co-Location Order: "We are trying to meet surging demand while upholding two fundamental values that underpin the electric industry in our country: first, that all customers have a right to receive electric service on a timely basis, and second, that electric service should be reliable and affordable for all customers. Given the scale of new large loads putting demand on our grid today, it is clear that fostering both of these values requires intervention."
Which Four Interconnection Mechanics Did FERC Approve?
The April 16 order (Docket ER26-1088-000, 195 FERC ¶ 61,030) approves four ways for a data center to plug into the PJM grid. Each solves a different bottleneck: available capacity, queue position, study timing, or pre-studied capacity. All four rely on existing PJM and FERC tariff mechanics rather than new constructs, a deliberate choice to reduce legal exposure and speed up adoption.
- Sub-full-capacity interconnection service (available capacity). The data center co-locates with an existing host generator, and interconnects at less than the host generator's full capacity, using the portion of the existing interconnection rights the generator does not need.
- Request acceleration at Decision Points I and II (queue position). Co-located load applications can move ahead of the standard queue at defined checkpoints, subject to PJM's study results. Co-located loads place less demand on the bulk power grid than new large loads without co-located generation, justifying the accelerated treatment. To qualify, projects must demonstrate there will be no significant network updates required or network impact, among other readiness milestones.
- Provisional Interconnection Service, or PIS (study timing). Interim interconnection services are provided during the full study, giving developers a bridge to early operations.
- Surplus Interconnection Service, or SIS (pre-studied capacity). Use of unused capacity at an already-studied generator’s interconnection point, without triggering a new full study.
The four mechanics are different ways of answering the same operational question—how a co-located data center plugs into the grid without triggering a multi-year re-study of the host generator's interconnection—enabling faster speed-to-power.
Which Generators Gain Most From Surplus Interconnection Service?
SIS is the most commercially interesting of the four mechanics for existing generator owners because it monetizes previously stranded capacity.
The generators that benefit most include:
- Retiring or derated thermal units with unused megawatts of interconnection rights at high-value points (for example, retiring coal plants in PJM's eastern and mid-Atlantic footprint).
- Existing nuclear and large thermal plants near concentrated load growth, particularly in Dominion, American Electric Power (AEP), and ComEd territory (the Northern Virginia, Columbus, and Chicago metro zones), where PJM load is most concentrated.
- Storage-paired assets where the underlying generator has capacity headroom that the storage does not fully use (for example, solar-plus-storage or gas-plus-storage sites where the battery sits below the full interconnection rights).
For illustration, a host generator running at roughly 85% of its interconnection rights with a forced outage rate near 5% has material surplus capacity (10%) available to a co-located load, depending on how PJM studies the combined profile.
Owners of underutilized interconnection rights now have an approved tariff path to extract value from them by attracting data centers to co-locate with these generators.
What Transmission Service Does a Co-Located Load Receive?
Connecting to the bulk power grid and taking service from it are two separate decisions. PJM's default transmission service for any load on the system is the Network Integration Transmission Service (NITS), the standard contract for firm power year-round. NITS commits PJM to serve a customer’s full load at any and all times, meaning that PJM may need to wait for generation and/or transmission upgrades before offering it to a large load.
Recently, PJM reopened its generation interconnection queue after pausing to study its backlog of proposed projects. With 800 proposed projects representing approximately 220 GW in new capacity in 2026, this growth signals progress, but it does not address the underlying permitting and financing challenges that have prevented projects already in the queue from being built.
The BYOG mechanics are variations that waive or defer parts of NITS for faster speed-to-power. PJM delivers the resulting service through three tariff product types:
- Firm contract demand: The co-located load holds firm transmission service (consistent with most aspects of NITS) and operates like any other firm load on the system. Availability is site-specific, depending on the point of interconnection. Unlike other NITS customers, entities contracting firm contract demand transmission on behalf of co-located loads cannot exceed the contracted demand level, and loads would be subject to a penalty if they withdraw additional energy beyond the contracted demand capacity.
- Non-firm contract demand: The load accepts interruption risk in exchange for faster interconnection or lower-cost service, making it better suited to loads with operational flexibility. It is available at more interconnection points than firm service, but power delivery is subject to curtailment based on real-time grid conditions. This service intends to provide brief and intermittent energy access from the bulk power grid, during available periods, under unanticipated circumstances, such as downtime for the co-located generator.
- Interim NITS: A bridge product that provides firm service on an interim basis while the co-located generator is still under construction. The load energizes early; once the generator and any transmission upgrades are complete, the project transitions to a standard NITS arrangement, and the generator can participate in the broader PJM market. However, while the load pays the NITS rate, the load is subject to curtailment under system emergency conditions, posing reliability challenges.
In practice, a 1,000 MW data center co-located with a 900 MW on-site generator would request 100 MW from PJM under one of these three products.
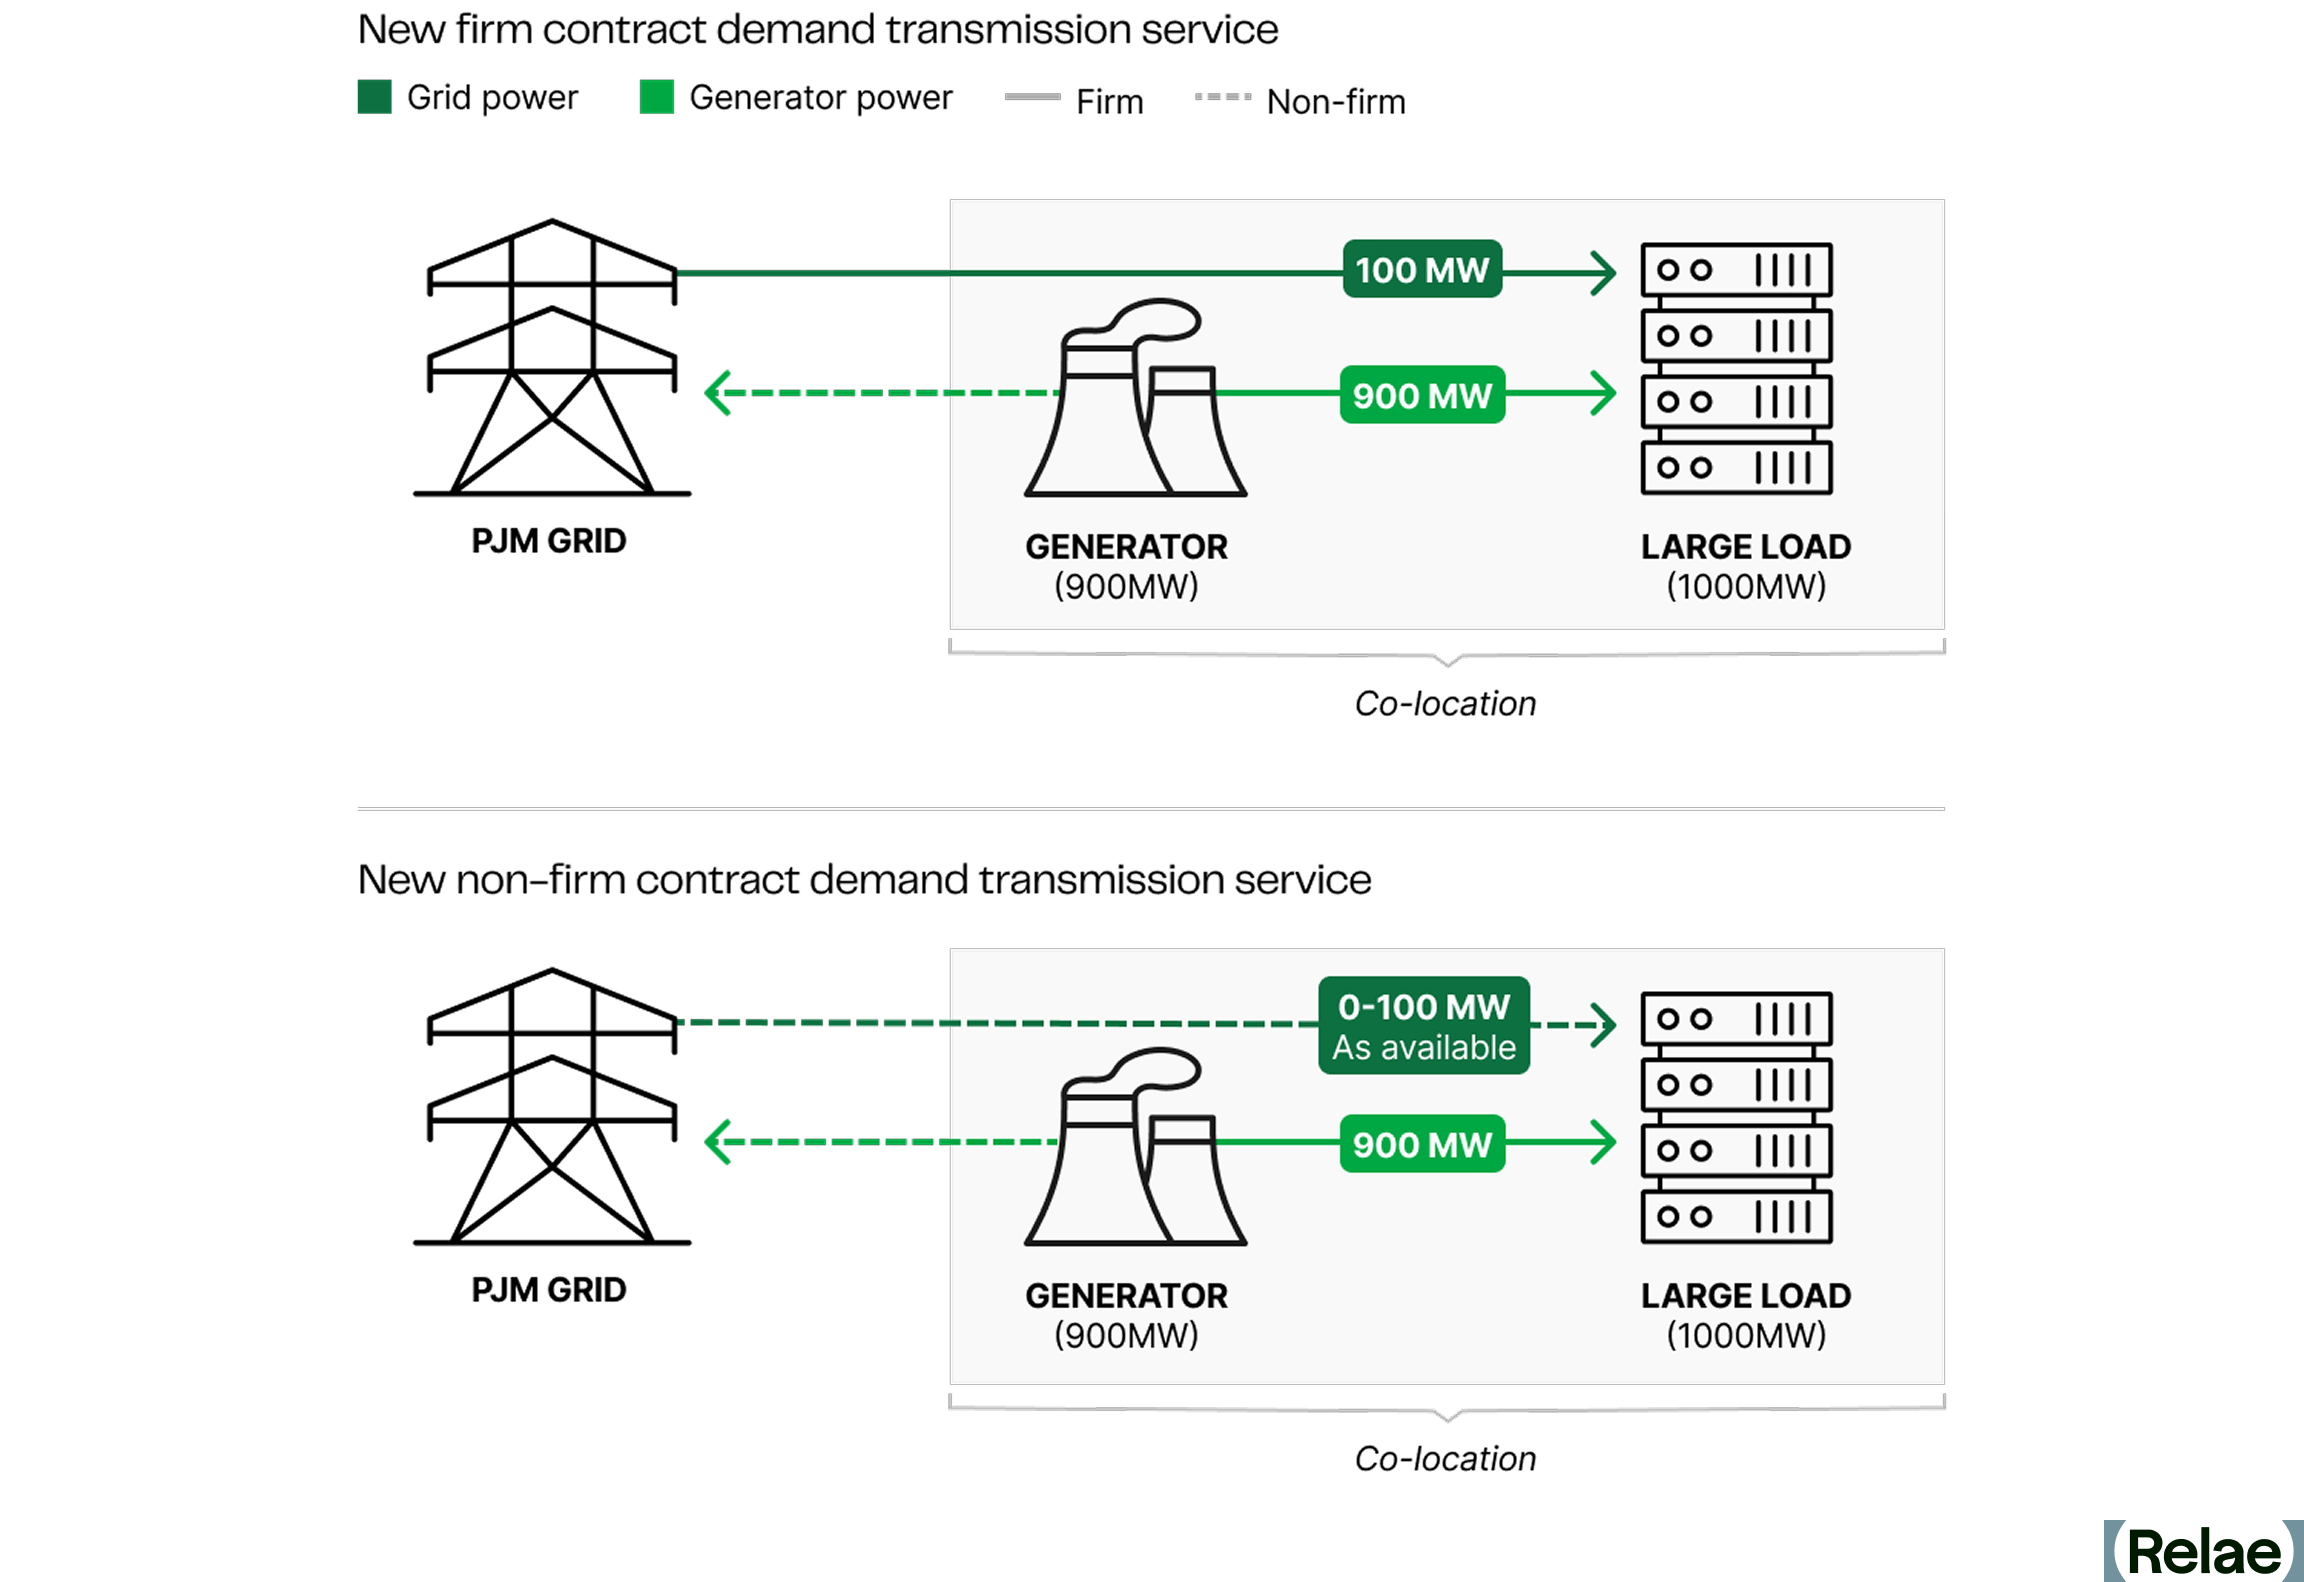
The interconnection mechanic (how the load connects) and the tariff product (what service the load receives) are two distinct decisions. For example, in the case of an interim NITS, a data center and co-located load could connect through a Provisional Interconnection Service (PIS). Other co-located loads may connect by submitting a request for acceleration at Decision Points I and II to secure firm contract demand service. The connection mechanism and tariff will vary based on each co-located load’s unique characteristics and project configuration.
For clients evaluating specific sites, the right path depends on how much of the host generator's interconnection capacity is available, how sensitive the load is to interruption, and how fast the site needs to energize. Grid modeling allows project teams to quantitatively assess their risk exposure before committing to a tariff product.
Which Two PJM Proposals Did FERC Reject?
Two elements of PJM's original filing did not make it through the April 16 order.
- Point of Change in Ownership substitution: PJM proposed swapping in "Point of Change in Ownership" for FERC’s mandated term "Point of Interconnection" in the definition of Co-Located Load. FERC rejected the swap as an unexplained deviation from the Co-Location Order's definition and because it could let transmission owners delay or effectively veto the Point of Change in Ownership location, creating uncertainty for co-located projects.
- BTM application-rule changes: PJM tried to fold changes to its BTM application rules into this same compliance package. FERC rejected that on the ground the changes did not fall within the scope of the initial order. BTM remains a separate regulatory track; the April 16 order does not settle it.
Project configurations built on either rejected proposal need restructuring before PJM's May 18 refile.
The order also directs PJM to add the PIS definition to the Open Access Transmission Tariff (OATT), Part I, section 1 (paragraph 26), and flags items in paragraph 29, including assessment of the reliability of co-located loads paired with electric storage, as out of scope.
These determinations should not be seen as FERC rejecting these tariff changes, but rather deeming them outside the scope of the order. They are open questions that belong in a separate docket. The direction to include PIS while declining to address issues not included in the compliance proceeding demonstrates FERC’s focus on speed-to-power, clarifying the rules for new co-located generators to connect to the grid more quickly.
What Is the Two-Strike Reliability Rule, and Why Does it Matter?
The rules for violating a co-location interconnection service agreement are still being developed, but FERC has urged PJM to issue robust protections to maintain reliability and cost allocation equity.
For both firm and non-firm contract demand transmission service, PJM will apply a penalty rate to transmission service customers who withdraw more energy from the grid than was contracted. The precise design of these rates for unreserved use is scheduled for a paper hearing this spring; however, developers should cautiously size and appropriately model load and generation sizes, as the penalties for jeopardizing PJM’s reliability are not limited to rates.
While penalty rate design for unreserved use is underway, PJM proposed a strict Two-Strike reliability rule for co-located projects. If a co-located customer failed to adequately implement automated loadshedding or generator tripping mechanisms during unusual grid conditions, PJM has previewed severe consequences:
- First strike: a 120-day operational pause for review.
- Second strike: termination of the transmission service contract and return to the NITS interconnection waitlist.
The entire purpose of pursuing a co-located large load configuration is to ensure speed-to-power while maintaining reliability. In a June 2026 order, FERC conceded that there are legitimate reliability concerns with co-located generation misoperation; however, PJM’s proposal to disqualify customers with multiple misoperations is unnecessarily strict. FERC ultimately agreed PJM has the authority to charge penalties to and temporarily suspend services for customers that fail to shed load or curtail, but cannot disqualify customers for misoperation. Data centers will need to rigorously model and design their co-located load and generator facilities with the understanding that multiple reliability violations could strand billion-dollar assets for multiple years.
Which BYOG Deals Need Restructuring Before the May 18 Refile?
Any deal built around the Point of Change in Ownership substitution or the BTM application-rule changes that FERC rejected needs restructuring.
In addition, co-located projects that relied on one of the four approved mechanics, but used PJM tariff language from the original December filing, may also need re-papering against the language PJM submits in its forthcoming May 18 compliance filing. Until PJM files that package and FERC accepts it, the operative document is the April 16 order itself.
Counterparties should confirm that operational controls, curtailment rights, and dispute mechanisms in the contract align with the proposed Two-Strike regime and the approved mechanics the project uses.
What Does Grid Modeling Reveal for a Co-Located Project?
Non-firm service is the lowest-cost tariff product for the portion of load the co-located generator does not serve, but availability depends on real-time grid conditions. Grid modeling is how developers size that exposure before signing.
Take the same 1,000 MW data center paired with a 900 MW on-site generator, contracting 100 MW of non-firm service for the residual load. Grid modeling might show non-firm power dropping out in roughly 15% of hours during the summer peak.
If the on-site generator also carries a 5% forced outage rate, the developer faces a meaningful probability of a compound event: grid supply drops out at the same moment the on-site unit trips offline.
In that window, the data center has three options, none of them free:
- Curtail load.
- Shift the load to another site.
- Draw more from the grid than the contract allows, which triggers a Two-Strike violation.
Grid modeling converts that risk into decisions the developer can price. A developer can test whether adding 50 MW of battery storage, contracting 150 MW of firm service instead of 100 MW of non-firm, or adding a smaller backup generator delivers the best risk-adjusted return.
Battery Storage Economics: Do the Numbers Still Pencil in Today’s Market?
Key Takeaways
- Batteries have competed away the revenue that financed their first wave. In Texas, ancillary prices have fallen about 90% since 2023, and price spikes driving arbitrage revenue are becoming ever less frequent.
- The business has moved from trading energy to selling capacity. In Texas, tolls work as private capacity contracts, and resource adequacy payments make up roughly 70% of battery revenue in California. Project economics increasingly pencil on a fixed $/kW-month basis rather than price spikes.
- Long-term contracts help shift the risk, but they don’t fully close the gap. Under a 15-year toll, a new battery needs about 22% less revenue, but that is still nearly three times what Texas batteries earned in the market in 2025.
- Buildout now depends on who will pay for capacity. Merchant revenue alone no longer covers a new battery, so growth hinges on how many buyers will sign capacity contracts worth nearly three times what Texas batteries earn in the market.
Battery Revenues Are Falling While Deployments Keep Rising
US developers are expected to install about 24 GW of utility-scale battery storage energy systems (BESS) in 2026, about 60% more than the record 15 GW added in 2025, according to the EIA. Yet in Texas, where batteries earn most of their money in the market, a typical battery earned roughly 85% less in 2025 than in 2023.
Is this unjustified overbuilding by an industry that has grown too fast? Some battery executives argue this is not overbuilding, because merchant revenue earned in wholesale markets is no longer the business. In their view, falling merchant revenue matters less because longer-term offtake contracts, such as 15-year tolls with utilities and large power buyers, make lower revenue financeable. As a result, today’s installations bank on batteries being paid as capacity assets rather than as pure energy arbitrageurs.
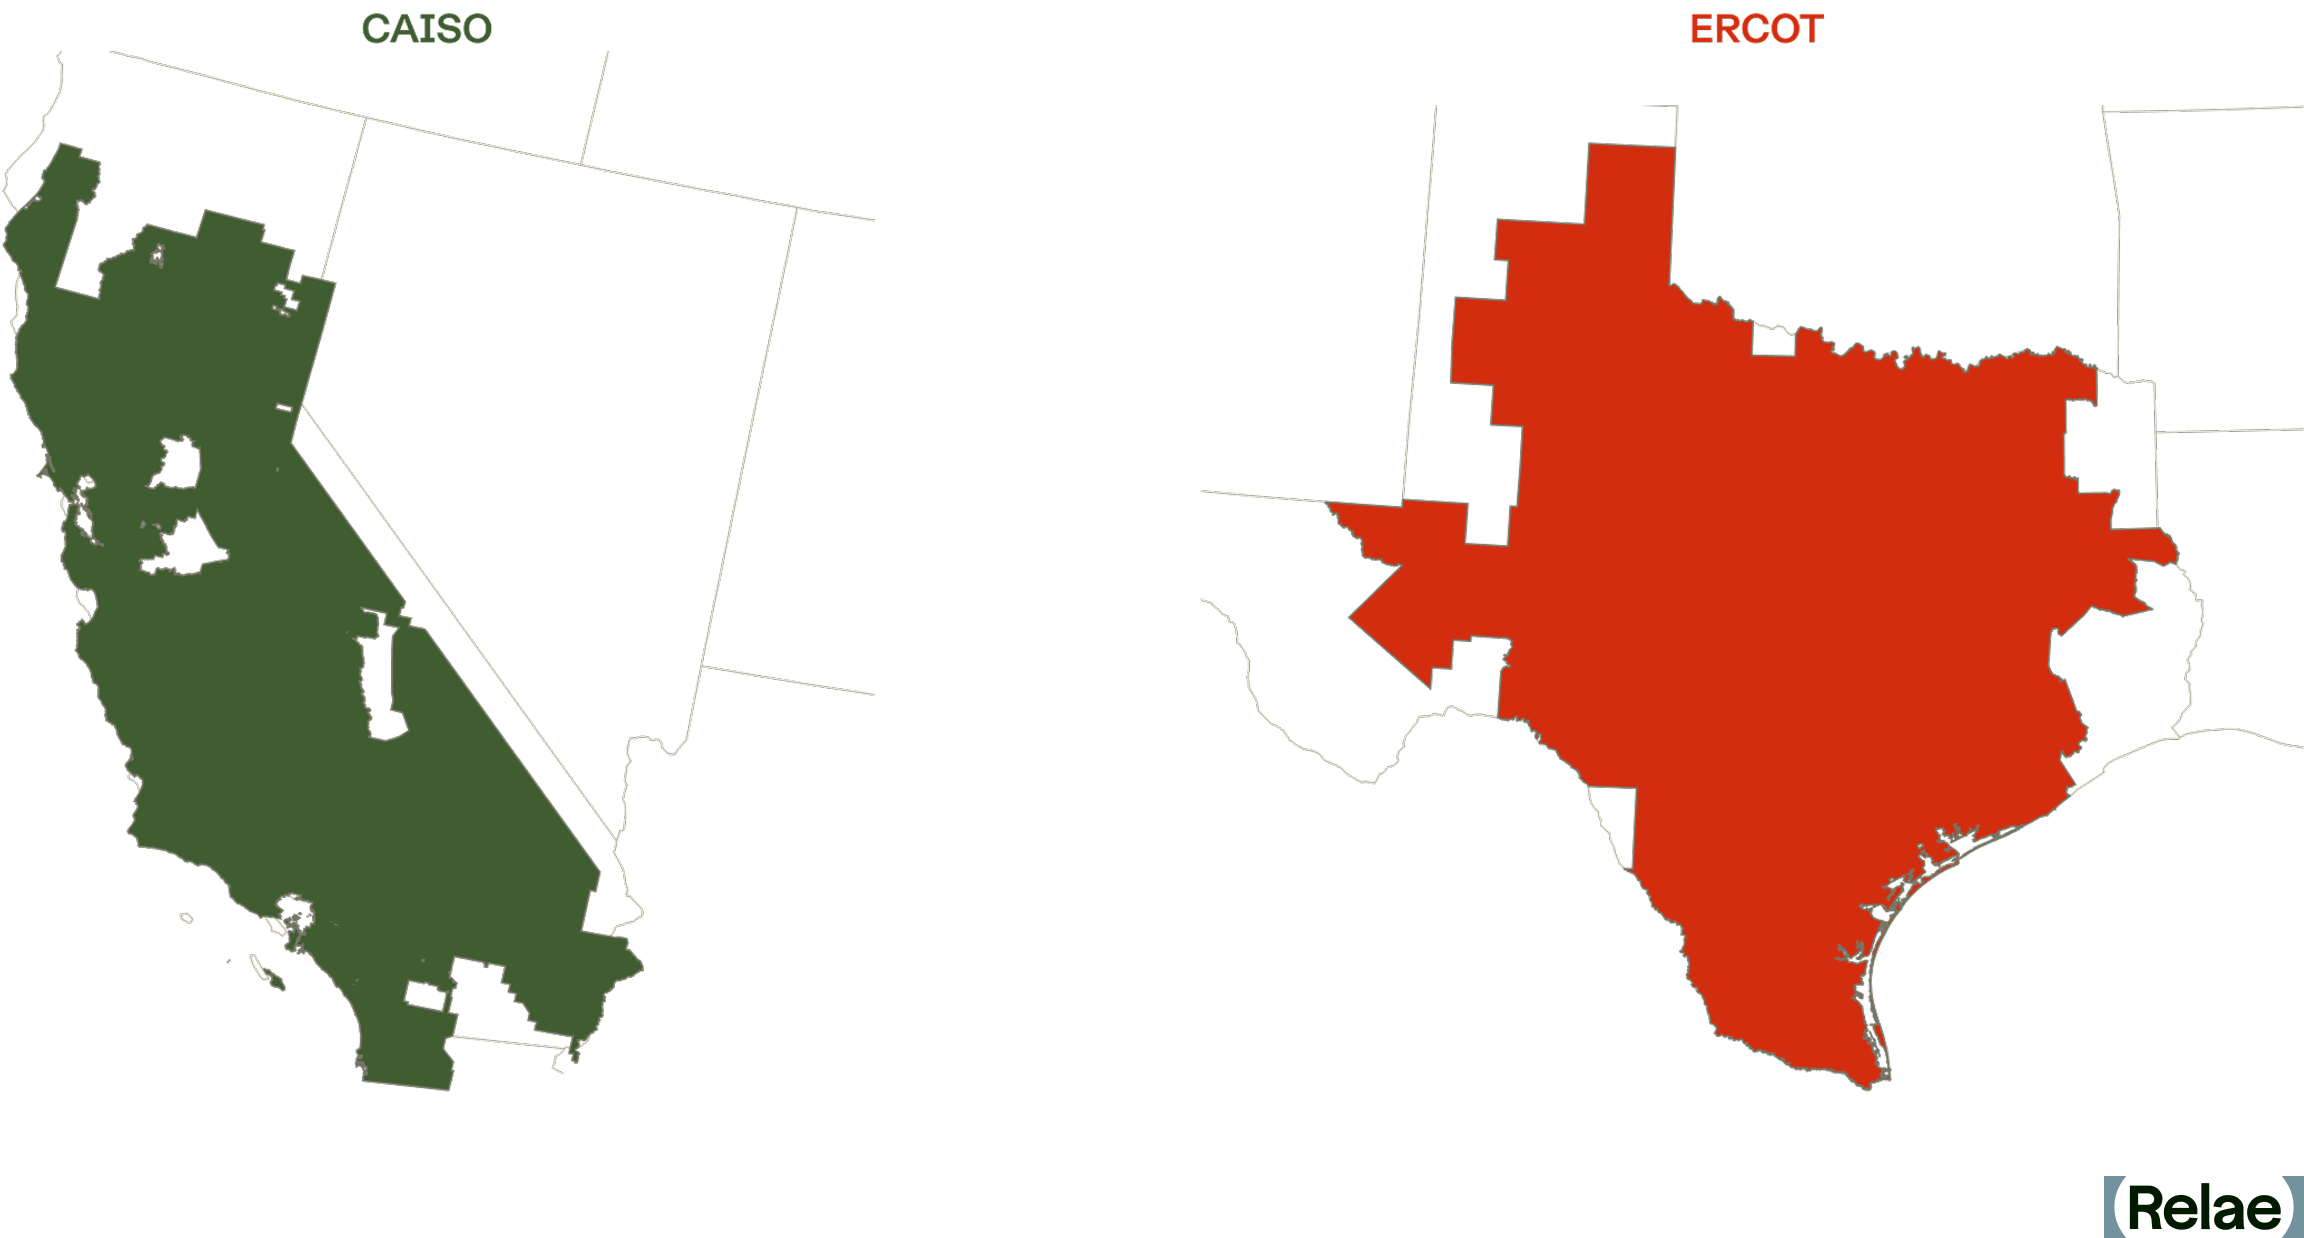
We tested those claims against market data from Texas (ERCOT) and California (CAISO) between 2022 and 2026. Our core finding is that project economics in both markets are increasingly reliant on fixed $/kW-month earnings rather than arbitrage revenue.
How Does a Grid Battery Make Money?
A battery has three ways to earn:
- Energy arbitrage (merchant: paid per MWh traded, hour-by-hour): charging when power is cheap and discharging when it is expensive. Its value depends on the daily spread between the highest- and lowest- priced hours.
- Ancillary services (merchant: paid per MW held in reserve, bought a day ahead): payments for standing ready to keep the grid stable, such as frequency regulation and reserves, whether or not the battery is called on to deliver energy.
- Capacity contracts (contracted: fixed $/kW-month for many years): a utility or large buyer pays a fixed monthly fee, often called a toll, for the right to use the battery, and takes on the market risk itself. It is the most stable of the three.
Texas batteries earned almost entirely from the first two. California batteries have earned from all three, and as market revenue has fallen, resource adequacy (RA) contracts–the mechanism through which load-serving entities meet the state’s capacity requirements–have become their main source of income.
That additional revenue stream is crucial in CAISO, making up roughly 70% of battery revenue by 2025, as net market revenue declined from $103/kW-year in 2022 to under $40/kW-year in 2025. Outcomes differ, too: California still curtails large amounts of midday solar despite its growing battery fleet, while ERCOT’s batteries have flattened price peaks.
How Texas Batteries Lost Their Merchant Revenue
Ancillary services filled up first. In 2022-23, ancillary services supplied more than 80% of Texas batteries’ revenue. But these markets are small and fixed in size. ERCOT buys about 3 GW of the fast reserves batteries excel at, and 6–8 GW of ancillary services in total.
The battery fleet passed the first mark in mid-2023 and the second in spring 2024; it is now about 19 GW of registered capacity. Average ancillary services prices fell 85-95% between 2023 and 2025, and ERCOT's day-ahead ancillary services spending fell from about $1.5 billion to $174 million. California’s ancillary markets saturated even earlier: batteries already won about 70% of its regulation-up procurement in 2022, and about 90% since 2024. Its ancillary services spending, much smaller than ERCOT’s to begin with, fell by about 60%, from $237 million in 2022 to $95 million in 2025.
Price spikes disappeared, too. ERCOT's average daily spread between its four highest- and four lowest-priced hours fell from $163/MWh in 2023 to $48/MWh in 2025, even as natural gas prices rose. Yet the typical day, adjusted for gas prices, looks much as it did in 2022. What vanished is scarcity: hours when real-time prices topped $1,000/MWh fell from about 60 in 2023 to 2 in 2025.
Batteries discharge into exactly those hours, and there are now enough of them to flatten the peaks. Controlling for gas prices, renewables, and demand, each additional gigawatt of batteries is associated with a 9% narrower daily spread.
Merchant revenue collapsed. Texas batteries earned about $193 per kW-year in 2023 and only about $29 in 2025, according to Modo Energy’s fleet index. California batteries’ market revenue fell from about $80 to under $40 per kW-year, before resource adequacy payments. Merchant revenue alone is no longer enough to finance a new battery in either market.
Costs fell too, but not by as much: NLR’s benchmark installed cost for a four-hour system fell about a third from its 2022 peak to 2024, from roughly $517 to $334 per kWh in 2024 dollars. Costs then turned up again: Lazard’s levelized cost of storage rose in 2026, to near the top of its range since 2020, as tariffs cut access to cheaper Chinese cells and new foreign-entity-of-concern (FEOC) rules pushed buyers toward other suppliers.
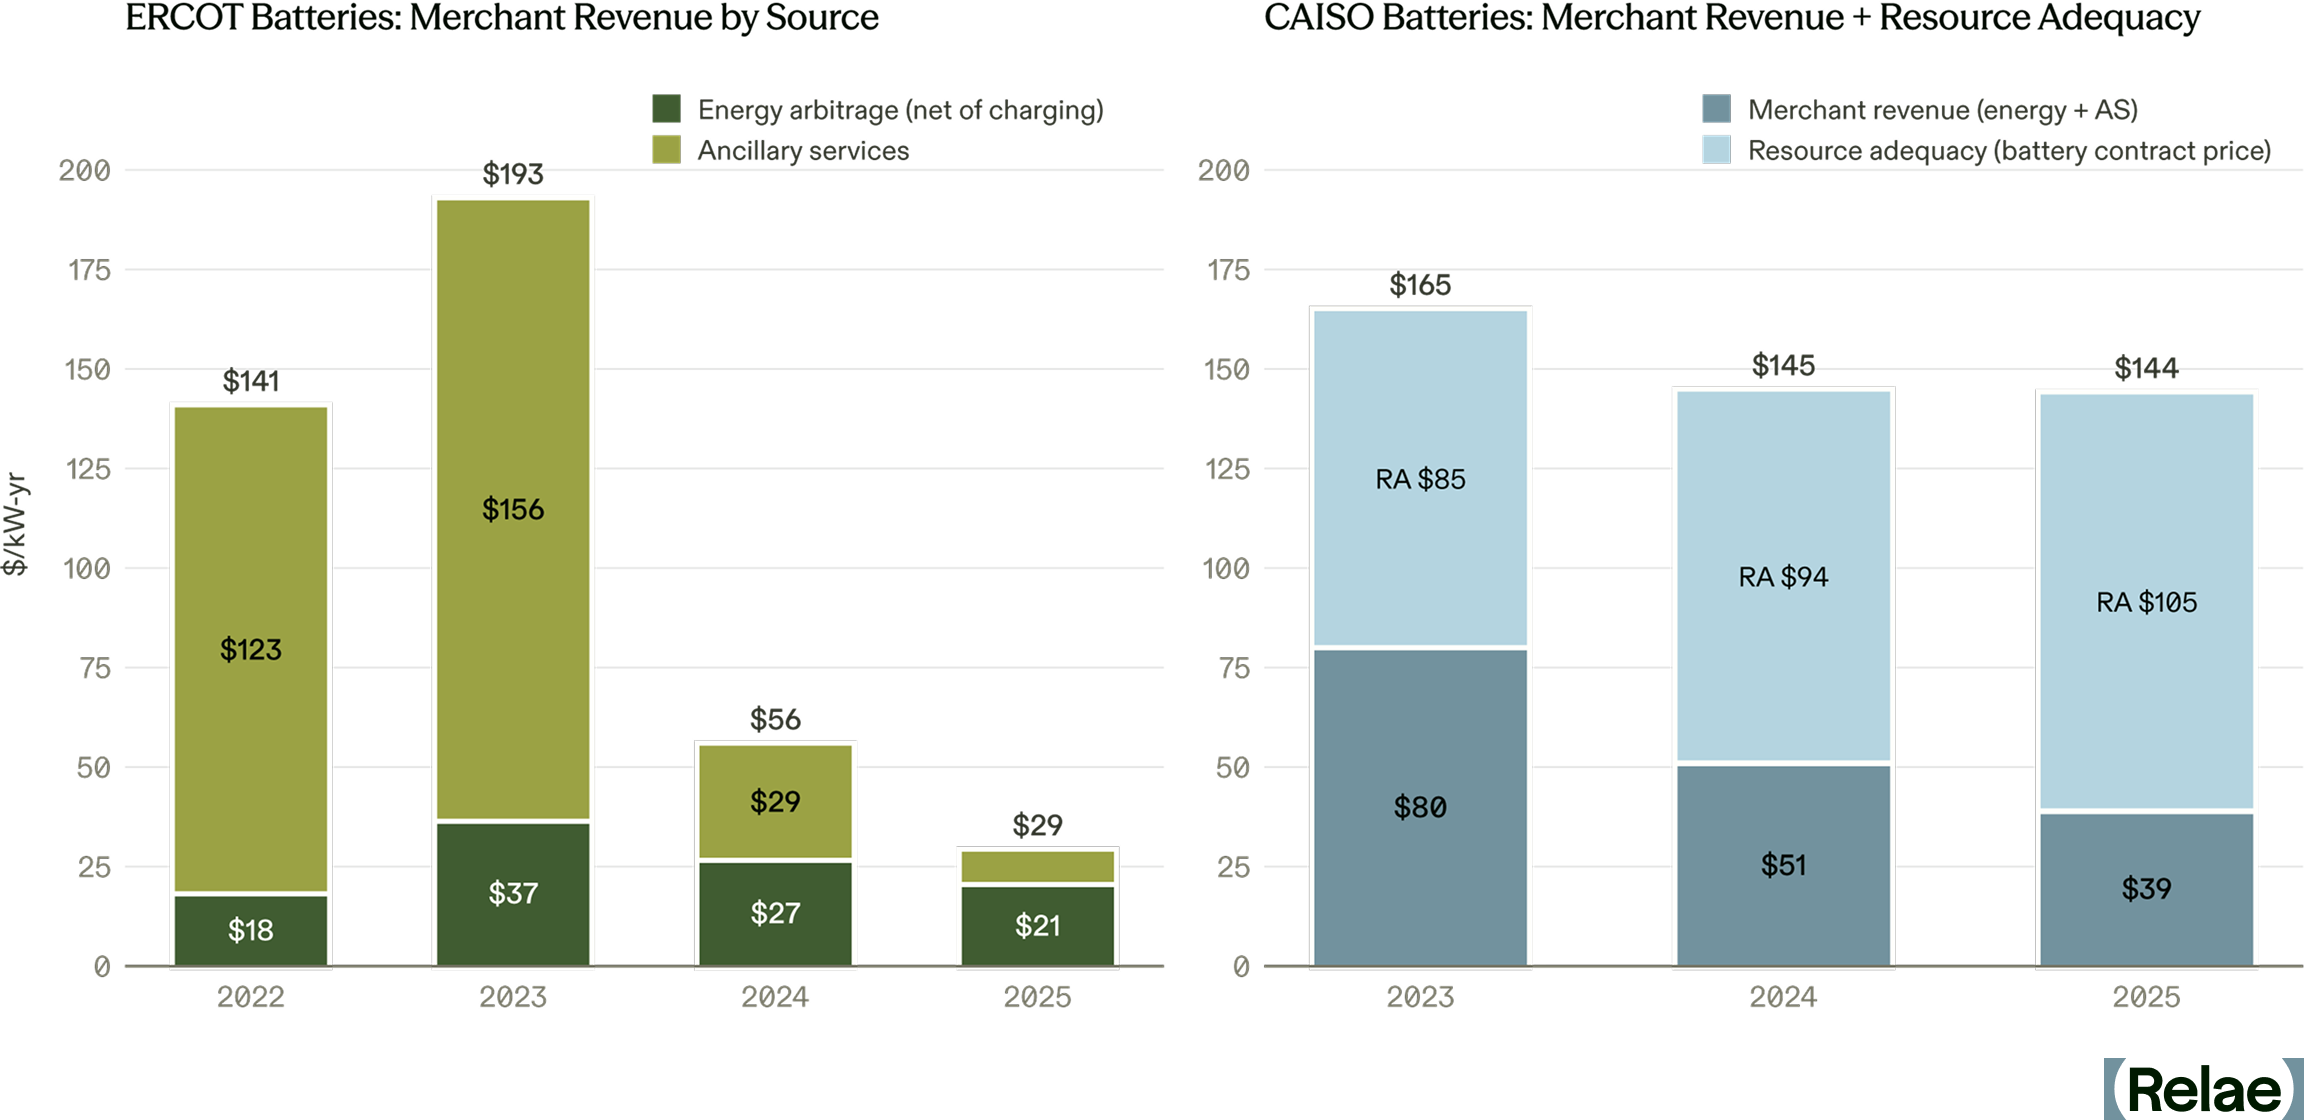
The Battery Business Has Moved From Energy to Capacity
As merchant revenue declines, storage developers are increasingly turning to capacity contracts to support revenue requirements. This has an important advantage: contracted cash flow can carry more debt at a lower cost. Under illustrative financing assumptions, moving a battery coming online in 2028 from merchant to a 15-year toll lowers its cost of capital from about 12.6% to 7.2%.
Using NLR’s projected installed capital costs for 2028, that cuts the annual revenue a two-hour system needs to break even by about 22%, from $105 to $82 per kW-year ($64-101 across NLR’s low- and high- cost cases). However, that is still nearly three times what Texas batteries earned in the market in 2025. Given this gap, new BESS installations might appear to be uneconomic.
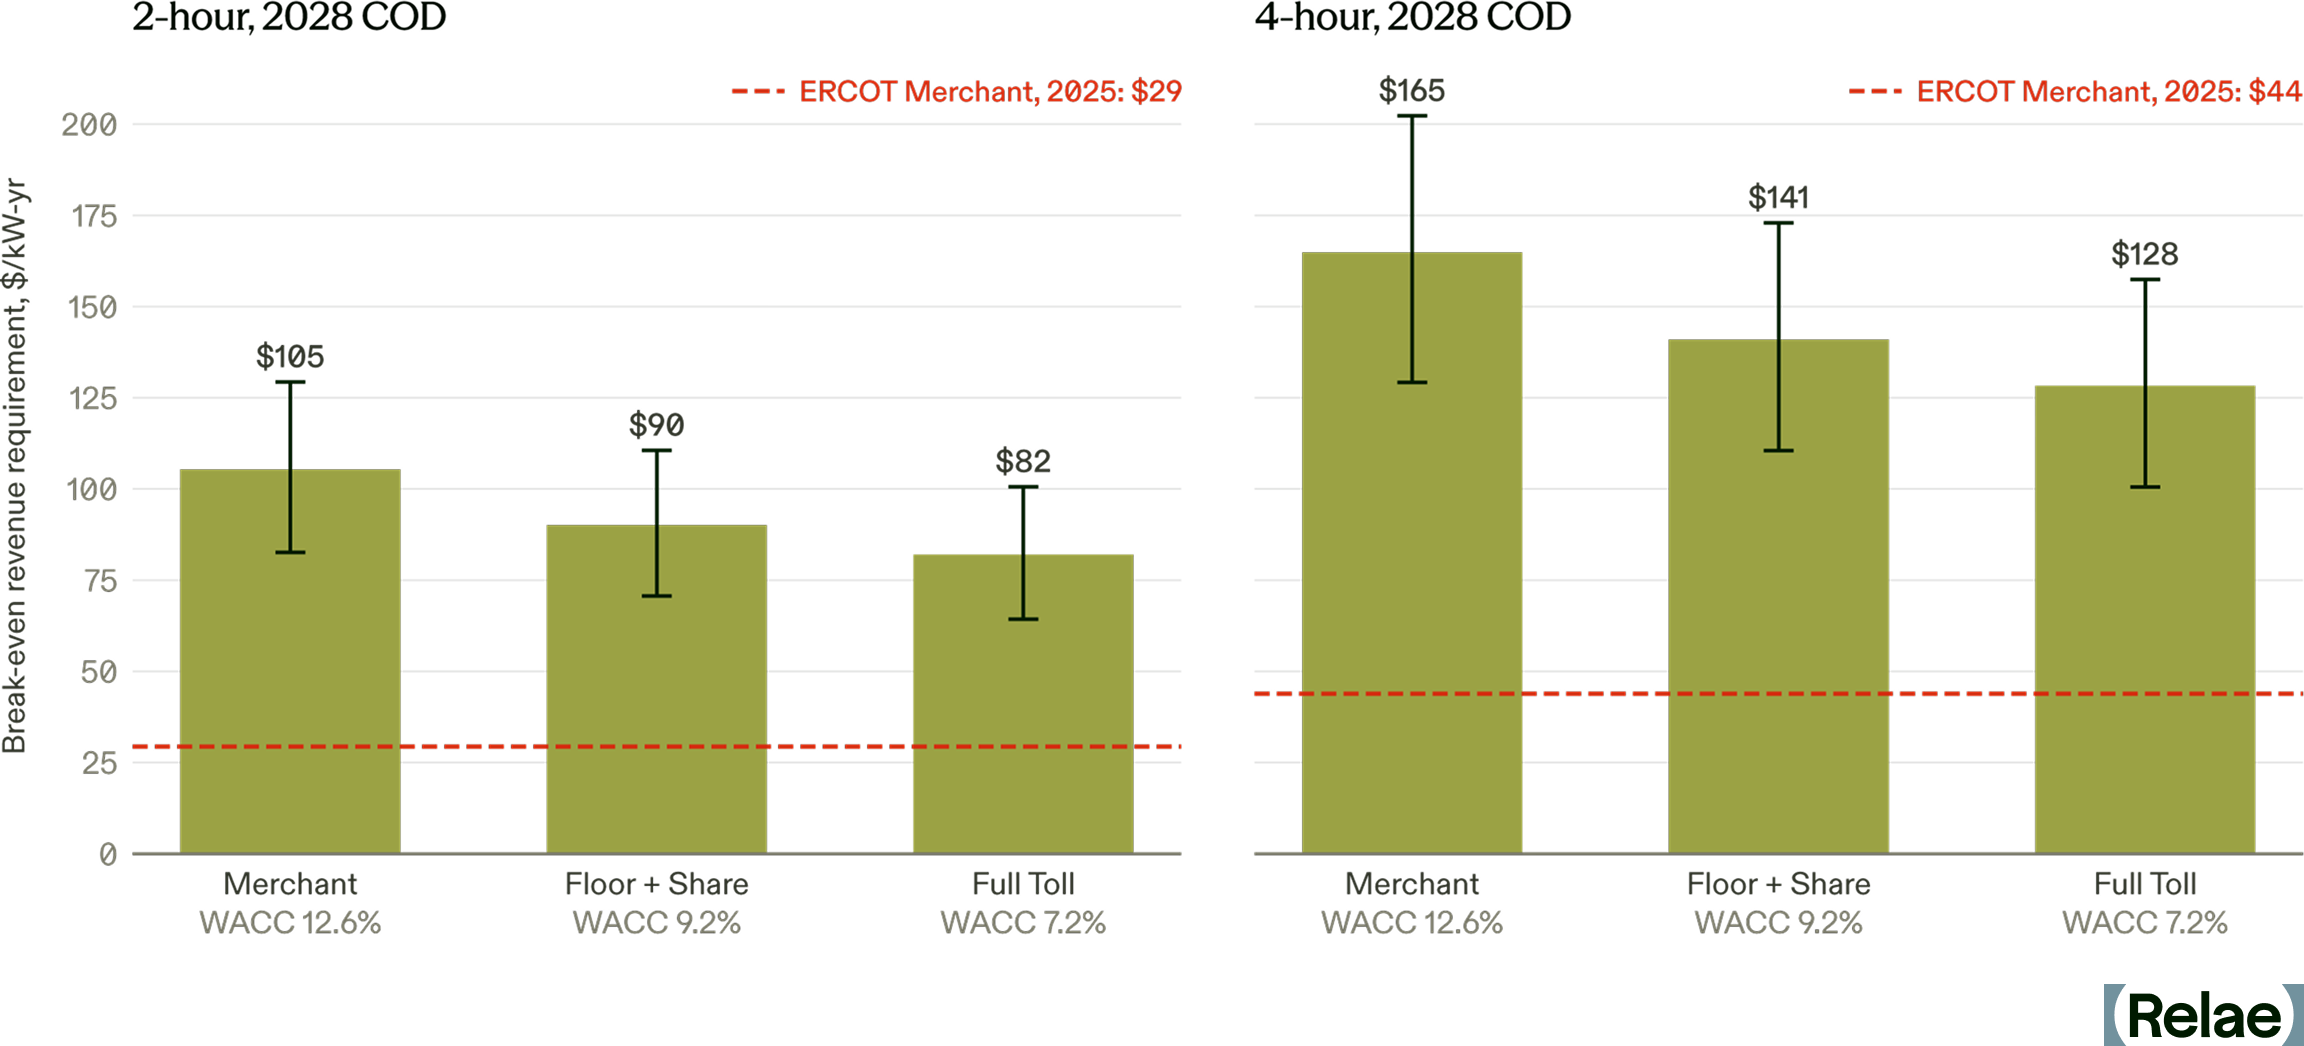
Why Are Developers Still Building BESS?
However, new BESS installations continue to be built. This is partly because many battery storage projects coming online now were financed on 2022-23 revenue (the average project can take over four years from entering the interconnection queue to operation), and partly because new contracts, such as tolls, are priced on capacity, not energy: the supplier is obligated to keep certain amounts of capacity available over a given time period, independent of energy delivery.
In Texas (which has no capacity market), such tolls are, in effect, private capacity contracts. In California, resource adequacy already plays that role: batteries’ RA contracts averaged about $9 per kW-month in early 2025.
An owner needs roughly $7 per kW-month for a two-hour battery (about $11 for four hours) to break even, in line with the roughly $7 per kW-month cap on a 20-year battery storage agreement Austin Energy approved in May 2026. By contrast, the energy and ancillary revenue an offtaker could capture by dispatching it is about $2.50–3.50 per kW-month. The difference is what buyers pay for firm capacity: insurance against scarcity events like Winter Storm Uri, capacity to meet their own load obligations, or a hedge against scarcity returning as demand grows.
The Next Battery Wave Depends on Who Pays for Reliability
Batteries have done what they were built to do: absorb volatility and steady the grid. In doing so, they competed away the revenue that financed the first wave. At today’s prices, merchant revenue no longer covers a new battery. The build continues on projects financed in 2022–23 and on capacity contracts worth nearly three times what Texas batteries earn in the market. Whether the buildout continues depends on how many buyers will pay that premium.
Deployment continues to grow in both markets. ERCOT registered about 4.2 GW of new batteries in January to July 2026, against 2.8 GW a year earlier. But the pace is slowing: Texas’s fleet grew about 50% in 2025 after nearly doubling in 2024, and interconnection queues are thinning: ERCOT battery applications fell by half in the second half of 2025.
Wholesale markets financed the first boom. The next wave depends on buyers who value reliability, including utilities, retailers, and large loads such as data centers, and on how cheaply that risk can be priced and capitalized. Data centers in particular put a high value on firm power: research inferring their willingness to pay from cloud computing prices puts it at up to $13,600 per MWh for frontier AI chips on guaranteed service, far above ERCOT’s $5,000 per MWh price cap.
For developers and investors, the question is no longer how much the market will pay, but who will sign, and for how long. For more on how interconnection queues shape how many storage projects get built and how queue wait times vary by technology, see Relae’s interconnection research.
Relae’s Power & Energy advisory team helps developers, investors, and large energy buyers understand and price the value of storage. This includes behind-the-meter modeling, resource portfolio optimization, and interconnection queue analysis.
Frequently Asked Questions
Why are battery storage revenues falling if deployment keeps growing?
Batteries have become victims of their own success. They earned most of their early revenue from two sources: ancillary services and high wholesale market prices. Texas now has more batteries than ancillary services the grid needs, so those prices have collapsed. And because batteries discharge during the most expensive hours, there are now enough of them to flatten the price spikes that used to pay the most.
What is a battery tolling agreement?
A toll is a long-term contract in which a utility or large buyer pays a battery owner a fixed monthly fee for the right to direct how the battery is used. The buyer keeps whatever the battery earns in the market and takes on the risk if that falls short. The owner gets a steady income it can borrow against.
Who is signing these contracts?
Mostly utilities, retailers and power traders, who need capacity to serve their customers or want protection against price spikes. In California, utilities sign capacity contracts with batteries to meet the state’s resource adequacy requirements. Large loads such as data centers place a high value on reliable power, but few have signed contracts with grid batteries so far; most of their battery deals are for on-site power.
Will battery storage buildout slow down?
Not yet. Texas is still adding more batteries each year, largely projects that were planned and financed when revenues were higher. But the pipeline behind them is thinning: new battery applications in ERCOT’s interconnection queue halved in the second half of 2025. Whether buildout holds up depends on how many buyers will pay for capacity at a premium to what the market pays today.
The Business Case for Carbon Accounting: What It Is and Why It Matters
Key Takeaways
- Carbon accounting is a regulatory and strategic necessity, with policies like the European Union’s Corporate Sustainability Reporting Directive (CSRD) and California’s SB 253 requiring emissions tracking.
- Many companies track emissions inconsistently, underscoring the need for structured, repeatable carbon accounting to ensure accuracy and impact.
- Accurate carbon data drives efficiency and risk management, helping organizations reduce costs, streamline supply chains, and comply with climate regulations.
- Scope 2 emissions are increasingly challenging to quantify, especially for data centers and power-intensive operations. Grid-average emissions factors mask location-specific and time-specific variations that drive real procurement and siting decisions. Precise scope 2 accounting requires understanding which generators actually serve the load, when, and under what grid conditions.
- Scope 3 emissions have historically been a complex challenge, requiring better supplier engagement, standardized reporting, and expert guidance to support accuracy.
Carbon Accounting: More Than Compliance, a Strategic Advantage
Companies increasingly recognize the business value of reporting carbon emissions: it reduces regulatory risks, attracts sustainability-focused investors, enhances market competitiveness, and drives cost savings through efficiency. Transparent emissions reporting strengthens brand trust and aligns companies with global sustainability standards, ultimately turning climate accountability into a strategic advantage.
Yet, many companies struggle with incomplete and inconsistent tracking. According to the State of Corporate Climate Commitment, 80% of corporate professionals surveyed have tracked emissions at least once, but only 52% do so annually. Without a structured process and reliable data, businesses face compliance risks, financial penalties, and missed cost-saving opportunities.
This guide provides a clear roadmap to effective carbon accounting, equipping businesses with the knowledge to navigate regulations, enhance data accuracy, and implement effective strategies for compliance and operational success.
[stat]
What Are the Benefits of Effective Carbon Accounting?
By embedding annual carbon accounting into operations, organizations can enhance sustainability efforts while achieving financial and strategic benefits. Key benefits include:
Enhancing Transparency and Accountability
By providing accurate and verifiable emissions data, companies can showcase corporate responsibility and build a foundation of transparency. Aligning with recognized standards like the GHG Protocol strengthens confidence among investors and regulators. As climate disclosure laws tighten globally, ensuring credible emissions reporting reduces regulatory risks and enhances stakeholder trust. This commitment to authenticity minimizes the risk of greenwashing and strengthens brand reputation.
Guiding Regulatory Compliance and Risk Mitigation
Businesses navigating evolving environmental regulations must proactively align with policies to avoid financial and legal risks. Mandated emissions reporting, under policies like the European Union’s Corporate Sustainability Reporting Directive (CSRD) and Carbon Border Adjustment Mechanism (CBAM) as well as California’s SB 253, ensures compliance and enhances corporate accountability. Staying ahead of these evolving requirements prepares businesses for future policy shifts and safeguards their long-term resilience.
Improving Operational Efficiency and Reducing Costs
By analyzing energy consumption patterns, organizations can identify operational inefficiencies, optimize supply chains, and implement cost-saving measures while reducing carbon emissions. For example, evo, an outdoor experiences company, collaborated with Relae (formerly Carbon Direct) to assess its carbon footprint. This analysis revealed opportunities to reduce emissions across facilities, products, and shipping. By promoting sustainable practices throughout their supply chain, evo enhanced both environmental performance and operational efficiency.
Building a Competitive Advantage in a Low-Carbon Economy
Building a competitive advantage in a low-carbon economy requires prioritizing emissions transparency and sustainability. Companies that integrate emissions transparency into their operations build stronger relationships with supply chain partners and meet consumer demand for responsible brands. Aligning corporate values with sustainability fosters long-term customer loyalty and enhances market positioning.
Driving Strategic Planning and Net-Zero Alignment
Setting and tracking net-zero commitments requires structured, data-driven carbon reduction roadmaps. Businesses that measure emissions annually are more likely to set public sustainability goals and take action. Carbon accounting supports clean energy transitions, fosters supply chain collaboration, and integrates carbon removal strategies to address residual emissions. By embedding emissions measurement into long-term planning, organizations facilitate resilience and profitability in an evolving business landscape.
Carbon emissions measurement correlates to climate action: 61% of companies that calculate their footprint annually have both set a public goal and begun working toward it.
What Is Carbon Accounting? The Basics You Need to Know
Carbon accounting is the systematic measurement, analysis, and reporting of an organization's greenhouse gas (GHG) emissions. Using standardized metrics like carbon dioxide equivalent (CO₂e), companies can assess emissions across operations and supply chains, identify high-impact areas, and set and track progress toward emissions reduction targets. When conducted annually, carbon accounting supports regulatory compliance, risk management, and decarbonization strategies essential for long-term sustainability.
The GHG Protocol is the most widely used framework for carbon accounting, setting the baseline for how organizations measure and report their emissions. It classifies emissions into three scopes:
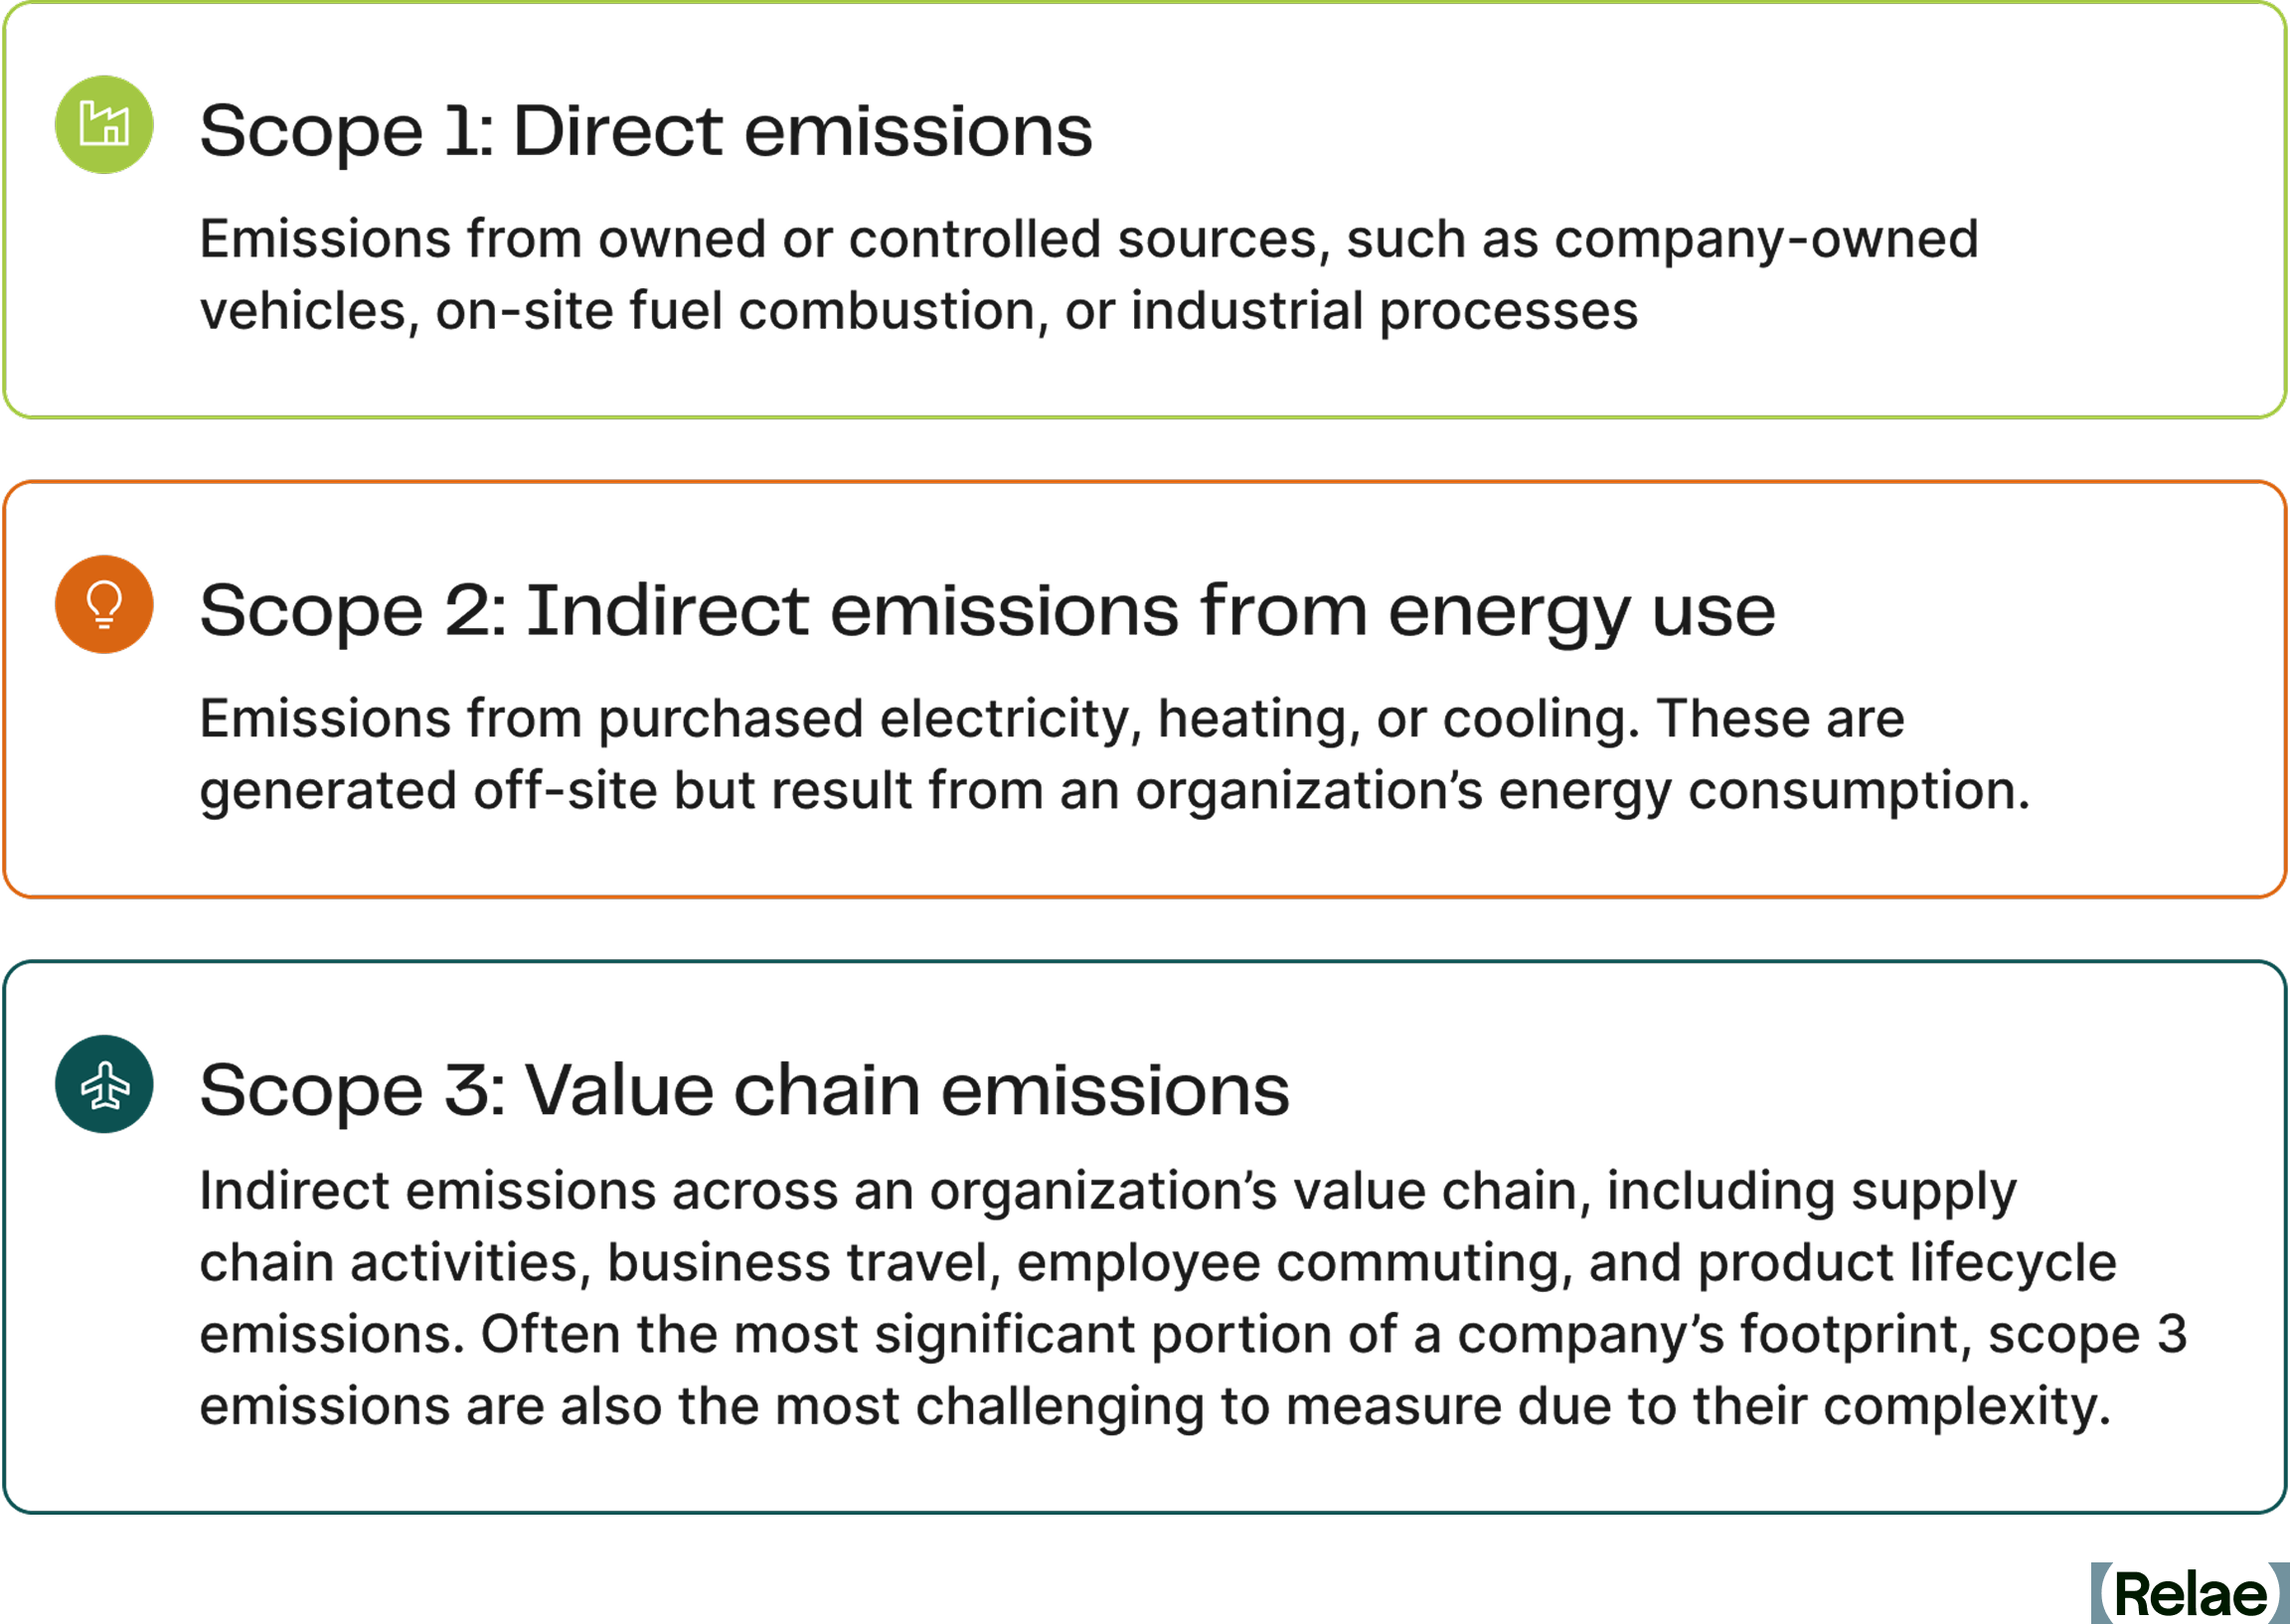
Keep in mind that scope 2 emissions are increasingly difficult to quantify using traditional methods, which fail to account for real-time grid fluctuations and locational energy variations. Cutting-edge, advanced carbon accounting methodologies now provide more precise tracking, particularly benefiting large power consumers like enterprise data centers and hyperscalers.
Scope 3 emissions also continue to pose a great challenge, requiring extensive data collection and supplier coordination, complexities that are difficult to navigate without expert guidance.
The Corporate Carbon Accounting Process: A Step-by-Step Guide
The carbon accounting process involves systematically measuring, analyzing, and managing an organization’s greenhouse gas emissions across its operations, supply chain, or product life cycle.
- Collect emissions data across all three scopes (scope 1, scope 2, and scope 3).
- Categorize and quantify emissions from each source to estimate the total impact.
- Verify data and report findings to promote compliance, accuracy, and transparency.
- Develop and implement reduction strategies based on insights from the data.
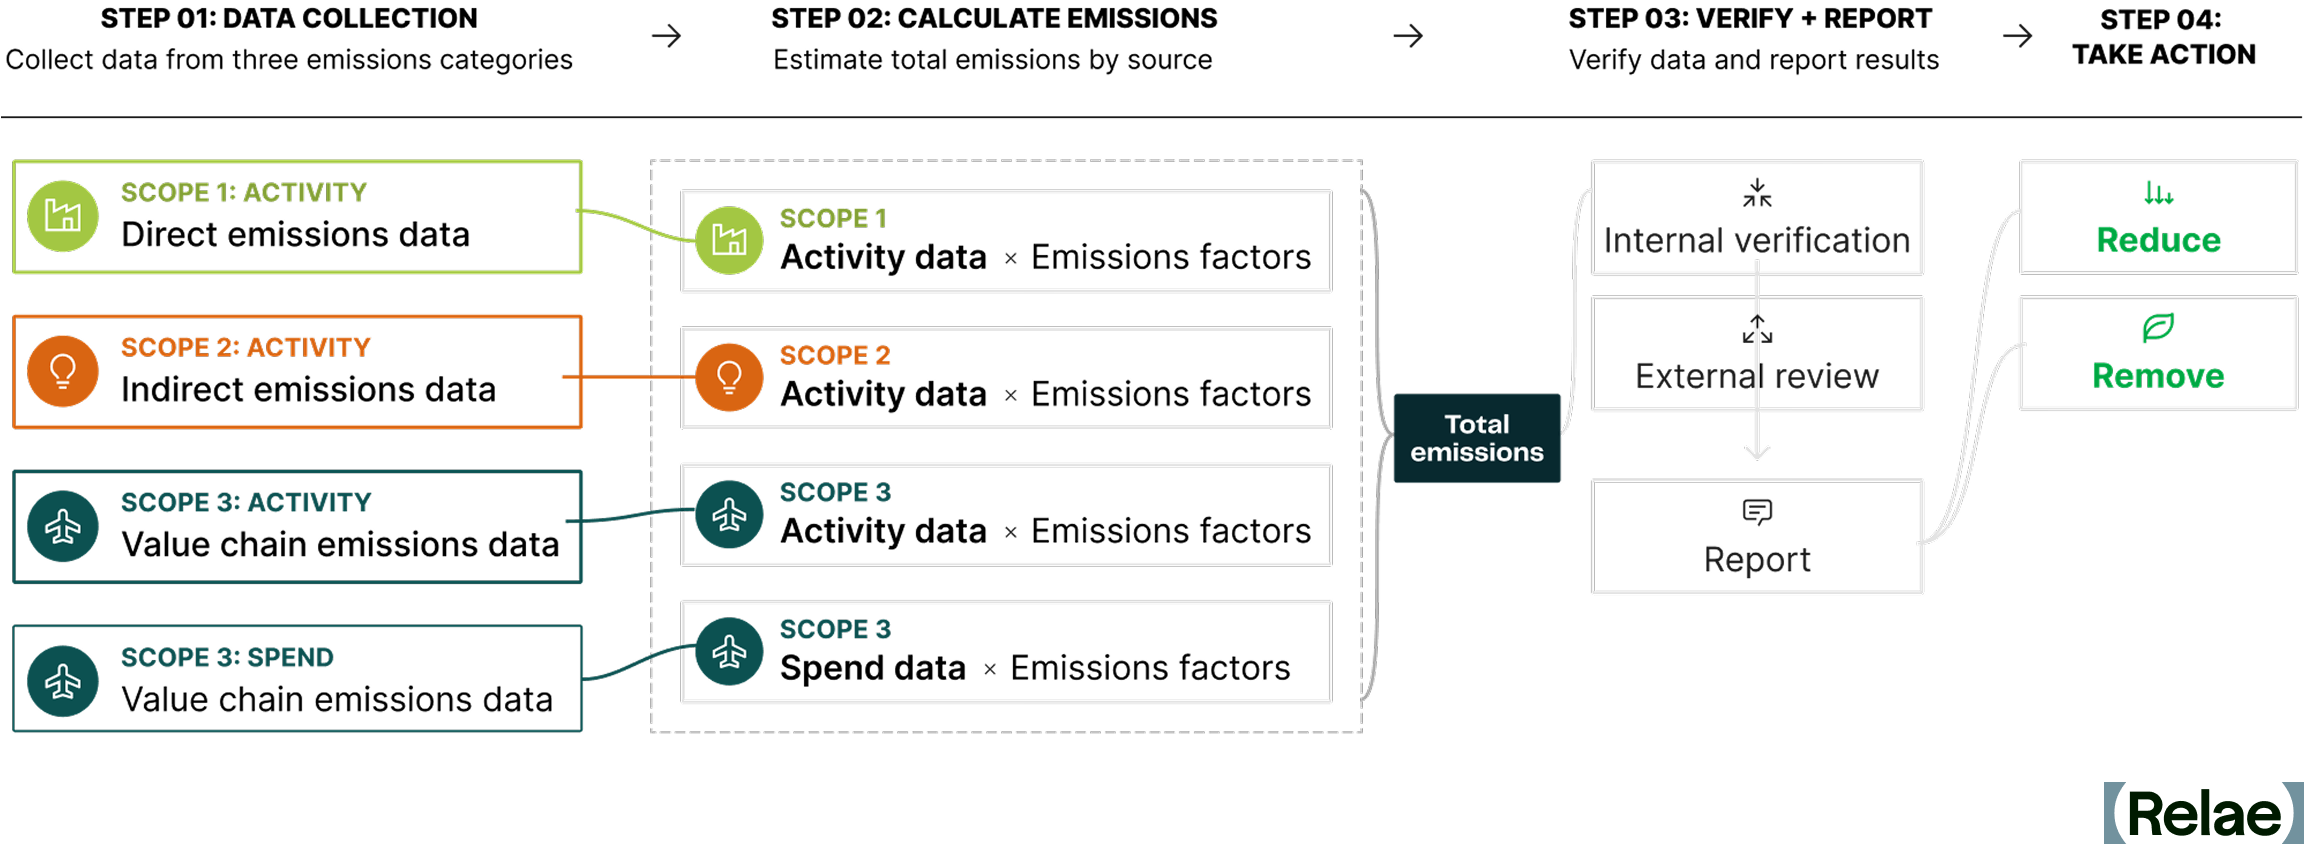
Activity Data Versus Spend Data
Carbon measurement primarily relies on two data types: activity data and spend data.
- Activity data includes direct measurements reflecting the physical amount of an emitting source, such as fuel consumption (in liters or gallons) or travel distance (in kilometers or miles). It accurately represents emissions from a particular operational emission source and allows for measurable decarbonization strategies.
- Spend data serves as an alternative when activity data is unavailable. It estimates emissions based on financial expenditures related to goods, services, or travel. While less precise, it is useful for approximating scope 3 emissions, where direct measurement is often challenging.
Tips for Accurate Data Collection
Effective carbon accounting relies on seamless collaboration across departments, suppliers, and external data sources. Key strategies include:
- Stakeholder engagement: Finance, operations, procurement, and sustainability teams must coordinate to track and validate emissions data. Engaging suppliers is essential for capturing and reducing scope 3 emissions.
- Addressing data gaps: When data is unavailable, proxy data can be used to estimate emissions, but it should be a temporary solution while organizations work toward obtaining accurate, real-world data.
- Standardization and verification: Implementing consistent methodologies and third-party audits enhances the credibility of carbon reporting, building stakeholder trust.
By leveraging precise data, understanding emission scopes, and adopting structured data collection methods, organizations can create a transparent, science-based approach to carbon accounting and lay the foundation for meaningful climate action.
Climate Standards Businesses Need to Know
Global standards and regulations define carbon accounting methodologies by establishing guidelines for how organizations set boundaries, measure, and disclose emissions. Several key frameworks and policies guide both the international and regulatory levels.
Guidance frameworks
GHG Protocol: The Foundation of Carbon Accounting
- The GHG Protocol is the most widely adopted framework for measuring and managing emissions across organizations globally.
- Developed by the World Resources Institute (WRI) and the World Business Council for Sustainable Development (WBCSD), it provides common standards for businesses, governments, and supply chains.
- Sector-specific guidance has been developed for industries such as energy, finance, manufacturing, and agriculture, which face stricter reporting requirements than service-based sectors.
- The GHG Protocol is currently undergoing its first major revision since its launch. Partnering with the International Organization for Standardization (ISO) to co-develop a consolidated corporate standard that merges the Corporate Standard, Scope 2 Guidance, Scope 3 Standard, and Actions and Market Instruments standard with ISO 14064-1. As of mid-2026, the effort is in active technical development, with a draft opening for public consultation targeted for mid-2027 and a final published standard expected by the end of 2028. Current standards stay in effect until that replacement is finalized, so nothing changes for reporting yet.
ISO 14064: Standardized Emissions Quantification and Reporting
- The ISO 14064 series, created by the International Organization for Standardization (ISO), offers detailed methodologies for greenhouse gas accounting.
- It includes guidelines for organization-level emissions quantification, reporting, and reduction projects.
- ISO 14064 serves as the foundation for independent verification and compliance with voluntary carbon markets, enhancing the credibility of emissions reduction projects.
Policies
EU CSRD: Expanding Mandatory Climate Disclosure
- The Corporate Sustainability Reporting Directive (CSRD) enforces detailed sustainability reporting requirements for companies operating in the EU.
- Following the EU's 2025 to 2026 Omnibus simplification package, CSRD's scope narrowed sharply. It now applies to roughly 5,000 large companies, with new thresholds of more than 1,000 employees and more than 450 million euros in net turnover (up from the original 250 employees and 50 million euros)
- In scope companies must still report scope 1, 2, and 3 emissions data aligned with the EU Taxonomy and European Sustainability Reporting Standards (ESRS).
California SB 253: State-Level Mandatory Emissions Disclosures
- California’s SB 253 Climate Corporate Data Accountability Act sets strict emissions reporting mandates within the US.
- It applies to companies with over US$1 billion in revenue doing business in California, requiring scope 1 and 2 emissions reporting by November 2026..
- CARB has said scope 3 reporting and third-party assurance requirements will be addressed in a subsequent rulemaking covering 2027 and beyond.
EU CBAM: Preventing Carbon Leakage and Promoting Decarbonization
- The Carbon Border Adjustment Mechanism Requirements (CBAM) requires importers of specific carbon-intensive goods to disclose embedded emissions to prevent carbon leakage and promote global decarbonization by ensuring that domestic and foreign producers face comparable carbon costs.
- During the transitional phase (2023–2025), importers were required to submit quarterly reports on embedded emissions.
- As of 2026, they must purchase CBAM certificates to compensate for the carbon footprint of imported goods.
Although carbon accounting requirements vary across regions and industries, they are all fundamentally rooted in the principles established by the GHG Protocol and ISO 14064. As global regulations like the EU CSRD and state-level legislation evolve, organizations must proactively align with these stricter standards to mitigate regulatory risks and support compliance with emerging sustainability expectations.
What Are the Industry-Specific Challenges of Carbon Accounting?
Carbon accounting presents unique challenges across industries due to varying operational structures, emissions sources, and reporting requirements. While the challenges outlined below focus on financial services, data centers, and philanthropies, similar complexities exist across manufacturing, transportation, healthcare, and other sectors. Tailored strategies are essential to effectively addressing these complexities.
Data Centers: Measuring and Reducing Scope 2 and 3 Emissions
Data center operators consume vast amounts of electricity making scope 2 emissions a major concern. In addition, data center developers and owners face significant scope 3 emissions from embodied carbon from the building materials and the IT hardware required to develop these assets. Effective strategies to reduce data center emissions include:
- Optimizing computing needs and power usage: Use real-time metering and AI-powered analytics to optimize electricity usage across time and locations.
- Procuring low-carbon electricity: Secure long-term access to compliant low-carbon electricity through power purchase agreements (PPAs) or high-impact renewable energy credits (RECs).
- Tracking life cycle emissions: To provide a comprehensive emissions assessment, account for embodied carbon in server manufacturing and end-of-life disposal.
Financial Services: Assessing Emissions From Investments and Portfolios
Financial institutions face significant challenges in evaluating scope 3 financed emissions from investments, loans, and asset portfolios. Key strategies to address these challenges include:
- Adopting industry standards: Frameworks like the Partnership for Carbon Accounting Financials (PCAF) can be used to standardize emissions calculations.
- Understanding asset level data: To accurately report on financed emissions, investors need visibility of emissions data, ideally at the company level.
- Prioritizing green investment strategies: Shift toward sustainable finance by integrating sustainability criteria and emphasizing green bonds or low-carbon funds or investments.
- Ensuring regulatory compliance: To enhance transparency, align with global disclosure frameworks like the International Sustainability Standards Board's (ISSB) IFRS S2 climate-related disclosure standard.
Philanthropies: Managing Emissions From Private Financing
Philanthropic organizations face challenges in tracking emissions across diverse funding activities, operational footprints, and investment portfolios. Effective strategies include:
- Assessing grantmaking impact: Many philanthropies support climate initiatives but may not track the carbon impact of grantees or funded projects. Establishing emissions metrics for grants can enhance transparency and effectiveness.
- Measuring operational emissions: While some philanthropies have relatively low direct emissions, travel, events, and office space still contribute to their carbon footprint. Implementing sustainable operations policies can help reduce emissions.
- Decarbonizing investment portfolios: Endowments and investment funds often hold assets with varying GHG emissions. Aligning investments with sustainability goals and engaging with asset managers on emissions reduction can drive impact.
Organizations across these sectors can enhance emissions transparency, improve sustainability efforts, and align with global climate goals by implementing industry-specific carbon accounting methods.
Navigating Evolving Standards and Scope 2 Complexity
Carbon accounting standards are actively evolving. In October 2025, the GHG Protocol released two proposals for scope 2 accounting revisions, with final standards expected by 2027. The proposals shift toward hourly and regional renewable energy matching, moving away from today's annual, region-agnostic approach. They also introduce consequential methodology that calculates actual emissions displaced by renewable projects, which varies significantly by region.
For organizations with 2030 climate targets, timing matters. Existing long-term contracts are expected to be grandfathered in under new rules. Meanwhile, new renewable projects face interconnection delays of 3 to 5 years, and the US power grid is experiencing sustained demand growth driven largely by data centers. These pressures converge: power demand is rising while new clean electricity supply is constrained.
Navigating these changes requires understanding emerging methodologies and their strategic implications. See our companion pieces on Navigating Scope 2 Accounting Changes and Scope 2 Emissions Explained for detailed context.
Frequently Asked Questions
How long does carbon accounting implementation take?
Initial measurement typically takes 3 to 6 months, depending on data availability and organizational coordination. Starting with data you already have (utility bills, fuel records) accelerates the process. Scope 2 and scope 3 require more extensive work than scope 1, so actual timelines vary based on which scopes are your focus.
What are the biggest obstacles to getting accurate emissions data?
Data siloes across departments (finance, operations, procurement track separately). For scope 2, grid-average factors mask location- and time-specific variations that actually drive emissions. For scope 3, extensive data collection and supplier coordination are required. Seamless collaboration across departments is essential.
Do we need to measure all three scopes to start?
Yes. Organizations should measure all three scopes. Start where your business is most materially affected, but eventually measure all three for compliance and complete visibility into your emissions sources.
How Does Geothermal Compare to Other Clean Firm Power Options?
Key Takeaways
- Geothermal shares the clean firm category with only three other technologies: nuclear, natural gas with carbon capture and storage (CCS), and solar or wind paired with long-duration energy storage (LDES).
- Buyers comparing geothermal to solar or unabated natural gas power contracts are comparing different products: one isn’t firm, the other isn’t clean, and both remain cheaper options because they satisfy less of what buyers currently need.
- Geothermal’s cost premium is real, but so is the value it delivers. Geothermal can reach 90%+ capacity factor, delivering dispatchable clean power around the clock, and it sidesteps the gas turbine manufacturing backlogs and pipeline infrastructure delays slowing other firm power technologies.
- Geothermal is closer to commercial readiness than most buyers realize. As demand for firm, low-carbon power intensifies, geothermal warrants a serious look alongside nuclear and gas with CCS.
Geothermal is Gaining Traction Despite Its Cost Premium
Hyperscalers, corporate energy buyers, and data center developers face unprecedented pressure to procure clean power. Wind and solar have played a major role in meeting this need, but they are intermittent, and load growth is accelerating and changing. This market pressure is creating bottlenecks that cannot be solved without new grid infrastructure and/or substantial additions of energy storage. Geothermal, which does not suffer from intermittency, has gained tremendous momentum as a challenger to wind and solar, yet it carries one seemingly glaring disadvantage: its cost.
Yet, major utilities and hyperscalers alike are lining up for geothermal offtake anyway: Southern California Edison and Google have signed separate contracts with Fervo, and Meta has two 150 MW agreements in place with Sage and XGS. These contracts are signaling a growing shift in power markets: not all megawatt-hours are created equal, and the cheapest contracts may no longer contain what buyers truly need.
Fast, Clean Firm Power: What Buyers Need Today
In the clean firm power evolution, clean came first. Buyers signed solar and wind power purchase agreements (PPAs) and matched their annual consumption with renewable energy contracts, or offset them with renewable energy certificates (RECs). With lax carbon accounting, solar and wind remain unbeatable on price. But annual emissions tallies conceal something important—a buyer can procure as much renewable electricity as it consumes over a year while still depending on the rest of the grid during the hours when those resources are unavailable. To close that gap, buyers need a source that delivers clean power around the clock, firmly in every hour, on demand.
Two unforgiving demands have followed since: speed and location. With today’s rapid buildout of new load, a power source needs to come online in time to deliver power when the customer needs it. It is also important to connect near a customer’s location because existing transmission assets are often fully subscribed. Failure on either axis can disqualify a project. However, a contract that can meet all attributes: clean in every hour, firm on demand, quick to deliver, and able to reach the load, might be the best (or only) option available. It is also likely to be considerably more expensive than those annual solar benchmarks that only met the clean condition.
Four Technologies Make the Clean Firm Power Shortlist
Given this strict set of constraints, what power options should buyers consider? The right set of technologies should aim to solve as many of the aforementioned conditions as possible, and that leaves a fairly tight shortlist:
- Solar or Wind paired with Long-Duration Energy Storage (LDES): To achieve the level of reliability that many buyers, including data centers, require, solar or wind would have to be paired with LDES, beyond 4–8 hours, to be able to cover evening hours and remain online during increasingly common extreme weather events. While there are promising LDES technologies on the horizon, most remain expensive and not yet widely commercial. Costs rise significantly compared to a standard solar or wind PPA, and viability varies by location. This will be increasingly competitive as storage costs fall, but not yet a mature firm-power solution at scale.
- Natural Gas with CCS: With large amounts of unabated natural gas generation coming online, CCS is an attractive option to mitigate a large portion of these emissions while retaining time to power (by building gas first and adding CCS later) and the dispatchability of gas-fired power. On the flip side, CCS is operationally complex, geographically restricted, and - unlike other options here - failure at any point in the CCS chain directly impacts the carbon intensity of power delivered. Gas-fired generation is also reliant on the gas delivery pipeline infrastructure, which may face capacity constraints. Finally, natural gas with CCS is 50% more costly per MWh than unabated firm gas.
- Nuclear: Nuclear is seeing renewed interest from a wide range of corporate buyers and investors. Conventional nuclear and small modular reactors (SMRs) are attracting funding and offtake deals. While nuclear power holds high potential, long development timelines, high capital costs, and technology risk remain barriers to commercializing the next wave of nuclear technologies.
- Geothermal: Geothermal can provide firm, dispatchable, and low-carbon power with capacity factors typically above 90%. Development timelines can be faster than nuclear in regions where resources are already proven, with some projects approaching commercial readiness now. Geothermal technology is still geographically constrained, but enhanced geothermal systems (EGS) are poised to expand their geographical flexibility by reducing the number of siting variables.
How to Evaluate the Right Clean Firm Power Technology for Your Project
How do these various options stack up? We compared them across six dimensions:
- Firmness: how reliably a resource can deliver power on the hour, on demand
- Carbon: the lifecycle emissions intensity when considering the operational emissions of the generating facility and the broader system carbon impacts required to meet any reliability gaps
- Time to power: a measure of how long it takes to get from “we need power” to delivery, including interconnection and schedule risk
- Cost (current): the likely cost of a PPA if signed today
- Execution risk: a measure of how likely a project’s claims regarding price, timing, and performance will hold
- Siting flexibility: a measure of how constrained a resource is to a specific geography
This frame is ultimately something the buyer should score themselves; below you will find our current read. Red (unfavorable) represents a weakness that can end an evaluation on its own, green (favorable) means the dimension won’t constrain the decision, and yellow (moderate) sits somewhere in between.
Comparing the clean firm power options is, perhaps ironically, challenging along the “clean” and “firm” lines. Every serious contender delivers low-carbon power around the clock, because that is the price of admission. Not one technology earns an unfavorable rating in those categories. And that is the catch: every weakness in the comparison table sits somewhere else. The dimensions that ultimately win (or end) these contracts may be the ones that the “clean firm” label can obscure or oversimplify.
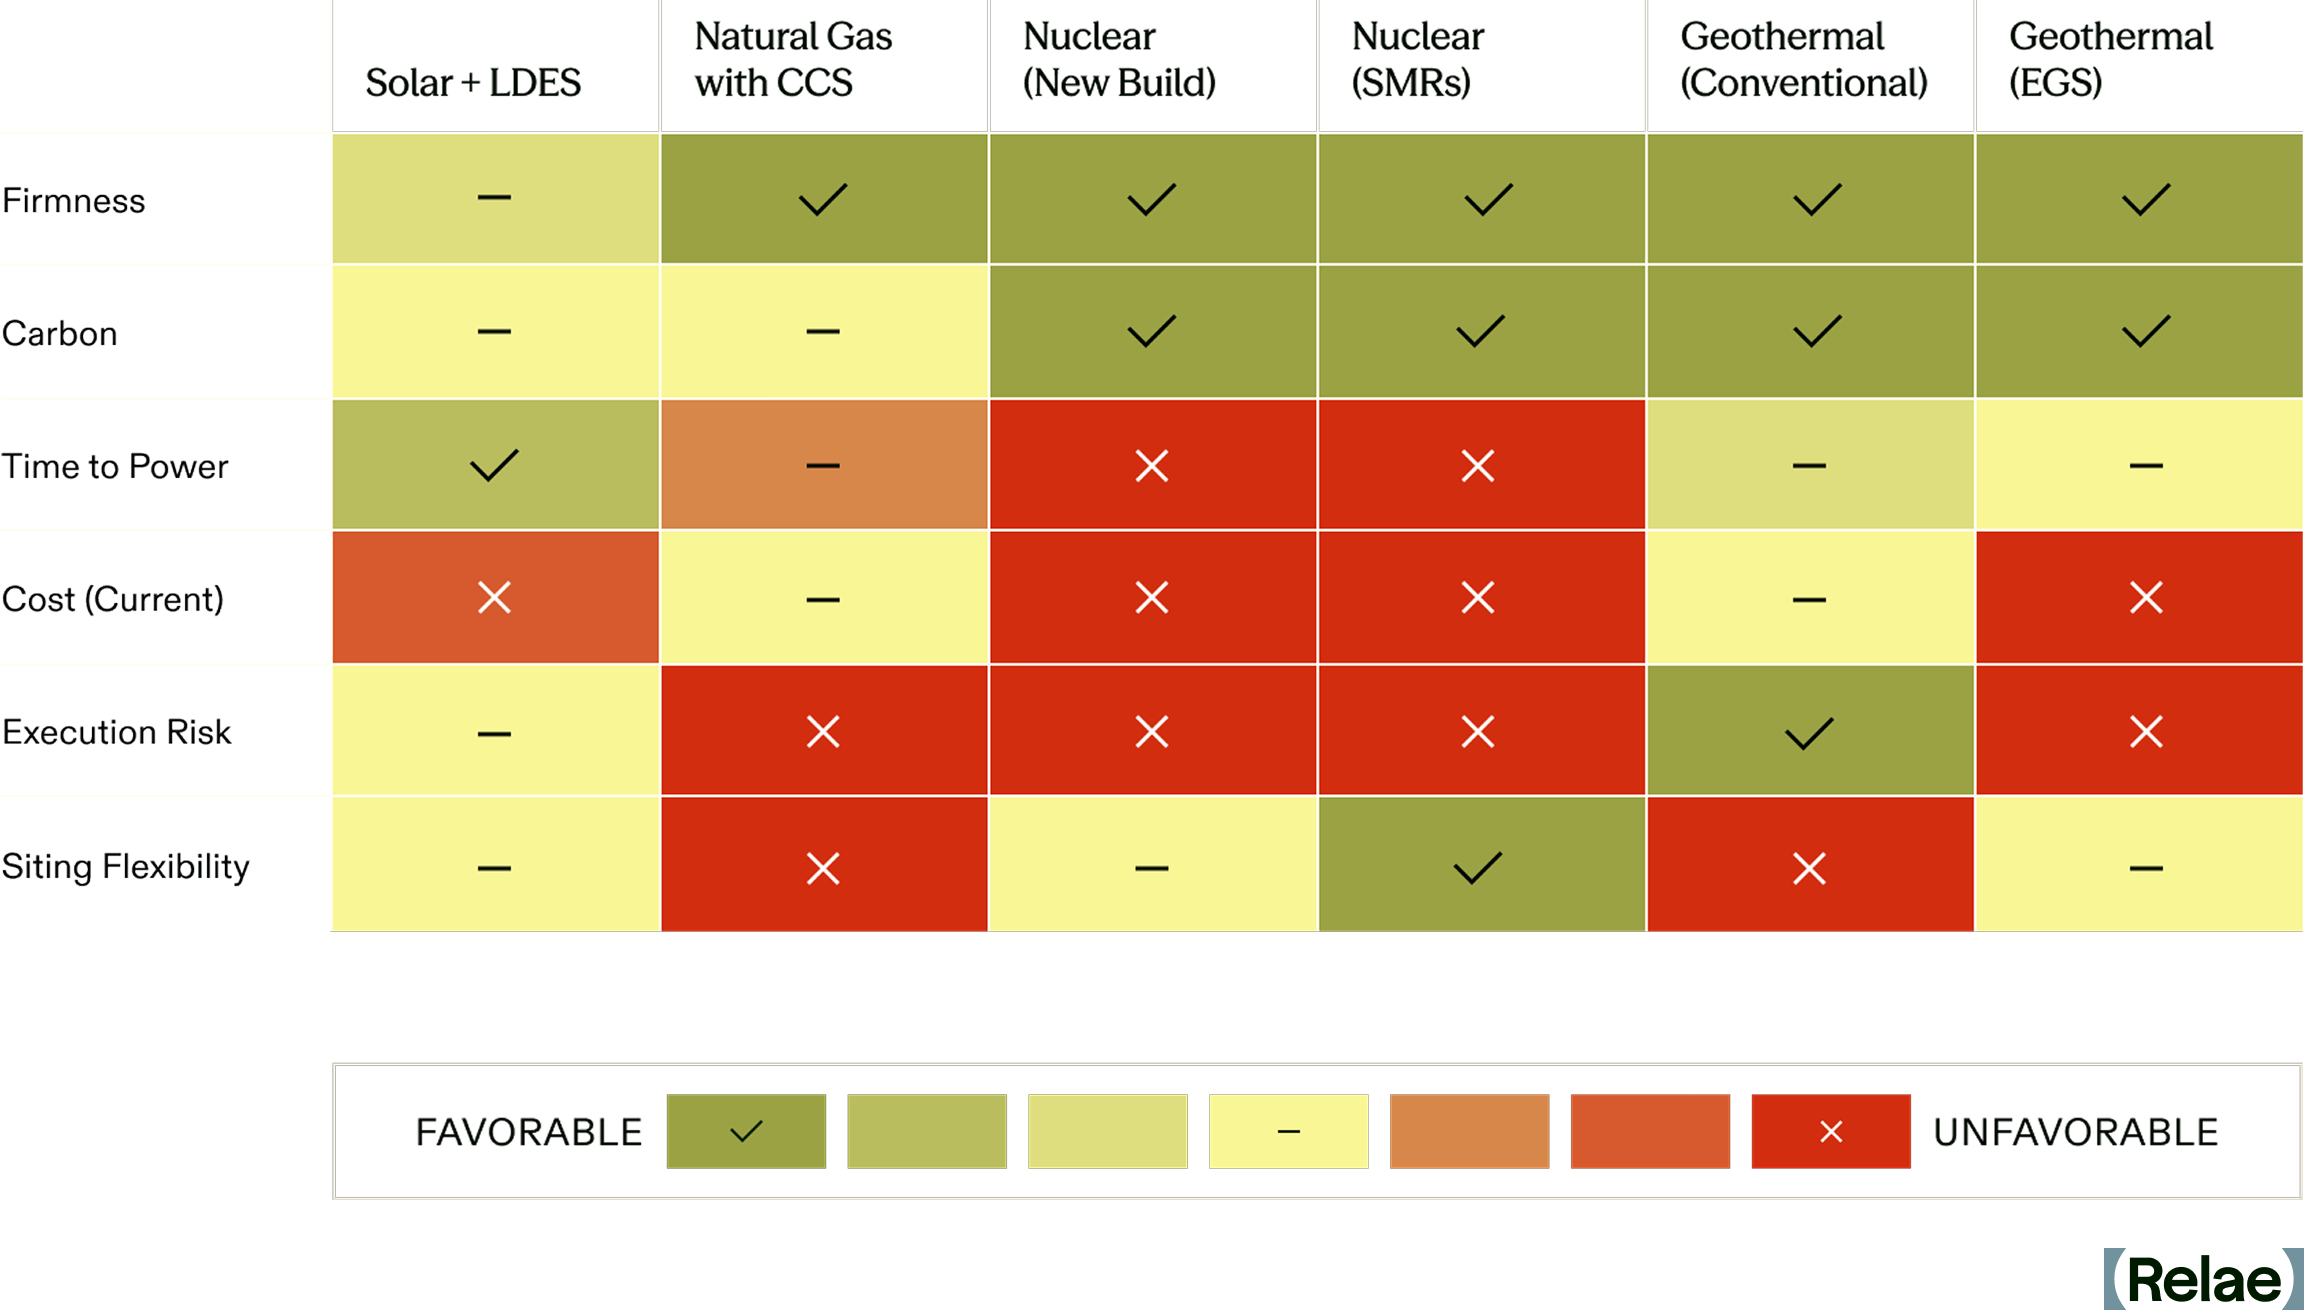
A resource that cannot be energized for a decade, or sited near load, or delivered at a price a buyer cannot defend internally, may be infeasible regardless of what else it offers. None of the four clean firm generation technology groupings clear every hurdle today, but they can satisfy different buyer priorities.
Solar or wind with LDES offers more buyer flexibility, at a price. Enough generation, storage, and other firming can deliver the reliability required, and the buyer sets that target. But the increments get expensive quickly, especially when reliability gaps remain long or unpredictable. Covering more hours means more storage and more generation to fill it, so each step toward firmness parity costs more than the one before it. Firming shortfalls also carry carbon consequences, depending on what gets called to compensate. Those emissions may be absent from GHG accounting ledgers, but that doesn’t stop them from hitting the atmosphere.
Gas with CCS is challenged by execution and siting because the product depends on a chain: gas generation, capture, transport, and a permitted storage site capable of permanent CO2 disposal at scale. Each piece can be developed and tested, but low-carbon electricity requires all of them to work together, which can only be demonstrated once all are built. A buyer cannot substitute a link, and cannot observe the whole chain before committing. Clean, in this sense, is conditional, and the delivered power could end up being far more carbon-intensive than advertised.
Nuclear ranks poorly on time, cost, and execution, but full-scale reactors and small modular reactors carry those weaknesses differently. A large reactor arrives in one piece, and its schedule and final cost come into focus as construction advances. By then, years and billions are committed; a buyer cannot learn from a fraction of a reactor before deciding whether to finish it. Small modular reactors are designed to break that capacity into increments a buyer could add as demand grows, which would ease the one-piece problem. But none are operating commercially in the US yet, and the signed deals target first power in the 2030s, so the modular promise is still years out.
Geothermal’s weaknesses work somewhat differently. Conventional hydrothermal is tightly constrained by location, which buyers can screen before choosing where to procure, or co-locate where possible. Next-generation geothermal, including EGS, could widen that geography considerably.
For EGS, the largest remaining uncertainty is execution: whether the developers can replicate successful drilling and reservoir performance at commercial scale. Part of that risk belongs to the rock, and no contract can make a reservoir perform. But drilling also produces information before the entire project has been built, and geothermal capacity can often be developed incrementally as needed. A buyer can require resource evidence before committing, tie later commitments to demonstrated performance, or spread procurement across projects rather than depend on a single field.
Geothermal’s flexibility has limits. A buyer who needs full capacity by a fixed date may have little room to wait for wells to perform before committing to the next phase. And successful wells do not eliminate risk in project expansion or guarantee performance in other locations. Execution risk stays with the resource. What geothermal offers is more opportunity to learn about that risk while a buyer can still do something about it.
Revisiting the Geothermal Premium
Geothermal contracts, especially EGS, remain expensive. But that premium looks different on this side of the comparison. Clean has a cost, but so does firmness, speed, reach, and execution. Every clean firm option pays for those attributes somewhere. Solar and wind contracts will remain cheap by comparison, but it’s the wrong comparison: the market signing geothermal contracts is pricing a much larger product.
That still leaves a hard decision. Geothermal and gas with CCS carry execution risk and siting constraints. Nuclear asks more of the buyer on cost and time. Firmed solar asks more as reliability requirements rise. The best option will change with each buyer, location, and project. Geothermal’s place in that choice is changing quickly. EGS is expanding where projects can be developed, drilling costs are falling, and commercial experience is growing. Those advances are bringing geothermal into consideration for buyers who previously had little reason to look its way.
And that may be the more revealing aspect of the geothermal market today: buyers are signing those contracts with the alternatives in full view. Their decisions offer an early indication of what clean firm power delivered in the right place and at the right time is worth, and which risks buyers are willing to carry to get it.
Frequently Asked Questions
Is Geothermal Cheaper Than a Solar PPA?
No, a geothermal power contract can be significantly more expensive than a solar PPA. But they're not the same product: solar meets annual clean-energy targets, while geothermal delivers firm, dispatchable power around the clock, which is why buyers are increasingly comparing it to nuclear and gas with CCS instead.
Is Geothermal Cheaper Than Solar with LDES?
Not necessarily on a per-contract basis, but the cost structures behave differently. Solar with LDES gets more expensive with every additional hour of reliability a buyer needs, since covering more hours means adding both more storage and more generation to fill it. Geothermal's premium, by contrast, is priced into the contract upfront as a firm, dispatchable product from day one.
How Does Geothermal's Risk Compare to Gas with CCS?
Differently, in a way that matters to buyers. Gas with CCS depends on a chain (generation, capture, transport, and storage) that can only be verified once the whole system is built, so a buyer can't test it piece by piece. Geothermal generates performance data incrementally through drilling, letting buyers require resource evidence or tie commitments to demonstrated results before committing further, though this data does not come free.
Which Deploys Faster, Geothermal or Nuclear?
Geothermal, in regions with already-proven resources. Fervo's Cape Station, for example, broke ground in 2023 and is on track for first power in late 2026 and 500 MW by 2028: a fraction of a typical new-nuclear large reactor timeline.
Scope 1 Emissions Explained: How to Track, Report, and Reduce Operational Carbon
Key Takeaways
- Scope 1 emissions are direct and controllable, making them a powerful starting point for decarbonization.
- Reducing scope 1 emissions can improve energy efficiency and lower operating costs.
- Reporting on scope 1 emissions is now required under new climate regulations, and companies that act now will gain an edge.
Why Scope 1 Emissions Matter Now
When we talk about corporate decarbonization, scope 2 and scope 3 emissions tend to take up the headlines, with a focus on renewable energy certificates (RECs) or challenges like complex supply chains. But scope 1 emissions, those produced directly from sources a company owns or controls, don’t get as much airtime. This is a missed opportunity.
As AI data center growth pushes companies towards on-site power, more organizations are confronting scope 1 boundaries for the first time. Scope 1 emissions enable companies to take immediate, tangible action to cut carbon, drive operational efficiencies, and get ahead of growing regulatory pressure.
What Are Scope 1 Emissions?
Scope 1 emissions are the direct greenhouse gas (GHG) emissions from sources that a company owns or controls. They mostly come from activities where fuels are combusted on-site within an organization’s operations. For industries that combust high amounts of fuels within their operations (e.g., oil and gas, chemicals, manufacturing), scope 1 can represent a significant share of the company’s emissions. For industries that outsource most of their production, scope 1 can be a smaller share of the overall footprint.
Scope 1 emissions typically fall into four categories:
- Stationary combustion: Emissions from burning fuels on-site for heating, manufacturing, or electricity generation. This includes boilers, furnaces, and turbines at company facilities.
- Mobile combustion: Emissions from company-owned or operated vehicles and equipment, such as cars, aircraft, delivery fleets, ships, or construction machinery.
- Fugitive emissions: Unintentional leaks or releases of gases, often from refrigeration and air conditioning systems. These can have an outsized impact because many refrigerants have global warming potentials (GWPs) hundreds or even thousands of times greater than carbon dioxide.
- Self-produced energy: Emissions from electricity, heat, or steam generated on-site, such as through natural gas-fired generators or cogeneration plants, even when the energy is used internally.
Identifying and categorizing scope 1 emissions correctly are the first steps toward uncovering potential operational improvements and carbon reduction approaches.
On-Site Power for AI Data Centers
As AI pushes data center operators toward on-site (“behind-the-meter”) power, a high-stakes accounting question follows: are those behind-the-meter emissions scope 1 or scope 2? The answer comes down to control, not location.
Under the GHG Protocol, emissions from on-site generation are scope 1 only when the reporting company owns or financially controls the generating asset (i.e., the self-produced energy category above). In most data center power deals, a third party owns and operates the generator and sells the electricity to the data center. In that structure, the company buying the power reports the emissions as scope 2, and the company generating the power reports the combustion as scope 1. Given the growth in emissions from the scale of AI infrastructure, getting the boundary right matters for corporate credibility.
Why Scope 1 Emissions Are a Strategic Priority
While scope 3 is often talked about as the largest source of emissions for corporations, that isn’t the case for all industries. For heavy sectors like oil and gas, chemicals, and manufacturing, scope 1 emissions aren't just significant - they are the bedrock of the emissions story. Other industries depend on these sectors' outputs to operate their own businesses, meaning that decarbonizing heavy industries’ scope 1 emissions can also drive reductions across other organizations’ scope 3 emissions.
Since scope 1 emissions are typically within a company’s direct operational control, they present a great starting point for decarbonization. Unlike scope 3 emissions, which require influencing suppliers, customers, or partners, companies can take immediate action on scope 1 sources. Even for industries with relatively small scope 1 footprints, reductions can often happen more quickly through internal decisions, such as equipment upgrades, process improvements, or fuel switching.
Regulatory momentum is also making scope 1 management increasingly urgent. Policies like the European Union’s Corporate Sustainability Reporting Directive (CSRD), California’s Climate Corporate Data Accountability Act (SB 253), and global ISSB-aligned frameworks are requiring companies to measure and publicly disclose their scope 1 emissions. Even within voluntary frameworks, reporting on scope 1 emissions is getting tighter. Within the Science-Based Targets Initiative (SBTi)’s new draft Net Zero Standard, scope 1 emissions must now have a separate target from scope 2 emissions, and the boundary must cover 100% of scope 1 emissions whereas previously the boundary was 95% of emissions. These market shifts highlight the importance of reducing scope 1 emissions.
Operationally, reducing scope 1 emissions offers business value. Many scope 1 reduction strategies, such as upgrading to more efficient equipment or reducing fuel waste can lower energy bills, improve asset performance, and reduce maintenance costs. For companies focused on both sustainability and profitability, targeting scope 1 emissions delivers a strong return on investment.
How to Calculate Scope 1 Emissions
To reduce scope 1 emissions, companies need to know exactly what and how much they are emitting. Calculating scope 1 emissions starts with gathering the right data at the facility level and understanding the activities that generate emissions.
What to Measure
Scope 1 emissions come from activities such as fuel combustion in boilers or vehicle fleets, refrigerant leaks from cooling systems, and on-site energy generation. Ideally, companies should collect activity data, like gallons of diesel used, cubic meters of natural gas consumed, or kilograms of refrigerant leaked and replaced. In cases where direct measurement isn’t possible, companies often rely on estimations, using financial spend data or industry intensity metrics as a proxy for fuel consumption.
Where to Find the Data
Facility-level data is the backbone of comprehensive and comparable scope 1 accounting. Much of the required data can be sourced from utility bills, fuel receipts, maintenance logs for HVAC and refrigeration systems, and reports from on-site equipment operators. Increasingly, companies are deploying sensors to capture real-time data on fuel consumption, refrigerant leaks, and on-site energy generation, improving both accuracy and responsiveness.
How to Calculate the Emissions
Emissions are calculated by applying the emissions factors (i.e., the amount of greenhouse gases emitted per the quantity of fuel or refrigerant) to the collected activity data. Many companies use carbon accounting software to automate calculations, track emissions over time, and ensure consistency with recognized standards like the GHG Protocol. Expert support is often critical, especially for sectors with complex operations. Carbon accounting experts help ensure the data is complete, auditable, and aligned with evolving regulatory requirements.
Accurate scope 1 data builds a strong foundation for compliance as well as for setting credible reduction targets and tracking long-term performance.
How to Reduce Scope 1 Emissions
With scope 1 emissions data in hand, companies can begin identifying and implementing reduction strategies. Because these emissions are within the organization’s operational control, companies often have multiple levers they can pull.
Operational Strategies
- Fuel switching: Replacing fossil fuels like natural gas or diesel with lower-carbon alternatives, like green hydrogen or renewable electricity, can significantly reduce direct emissions from stationary and mobile combustion. Depending on the switch, this could result in higher scope 2 emissions, but these can be more readily addressed through market-based instruments, thus lowering the overall footprint.
- Equipment upgrades: Modernizing boilers, generators, fleets, and other combustion-based equipment can improve energy efficiency and cut emissions. Newer technologies often perform better and emit less.
- Process innovation: In emissions-intensive industries like cement and steel production, rethinking industrial processes can yield dramatic reductions. Low-carbon production methods are increasingly becoming commercially viable.
- Leak detection and repair: Methane leaks from oil and gas operations and refrigerant leaks from cooling systems are major contributors to scope 1 emissions. Deploying monitoring technologies and maintaining rapid-response repair programs can fix leaks before they lead to large amounts of emissions.
Strategic Procurement
- Vendor selection: Companies can prioritize suppliers that offer lower-emissions alternatives for fuels, materials, and services.
- Fleet electrification: Procuring electric vehicles for delivery, service, and logistics fleets reduces both emissions and long-term fuel and maintenance costs.
- Equipment design: Working with suppliers to source modular, emissions-efficient machinery can reduce on-site fuel use and improve flexibility over time.
Driving Innovation Through R&D
- Low-carbon products: Research and development teams can design products and processes that inherently require less energy, or lower-carbon energy, to produce, lowering scope 1 emissions at the source.
- Material innovation: Developing new chemistries or alternative materials can avoid high-emission production methods, contributing to broader decarbonization goals.
- Closed-loop systems: Designing circular, waste-reducing systems can minimize both raw material use and the on-site emissions associated with production and disposal.
Reducing scope 1 emissions often requires up-front investment, whether it’s upgrading equipment, switching to alternative fuels, or embedding low-carbon principles into procurement and R&D strategies. While the initial costs can be substantial, they deliver long-term value through improved operational efficiency, reduced regulatory risk, lower energy expenses, and enhanced brand value in a marketplace that increasingly rewards climate leadership.
Frequently Asked Questions
What are the main categories of scope 1 emissions?
Scope 1 emissions fall into four categories: stationary combustion (fuels burned on-site in boilers, furnaces, or turbines), mobile combustion (company-owned or -operated vehicles and equipment), fugitive emissions (leaks of refrigerants or methane, which often carry outsized global warming potential), and self-produced energy (electricity, heat, or steam generated by equipment the company owns or controls).
Which regulations require companies to report scope 1 emissions, and when do they take effect?
The EU’s Corporate Sustainability Reporting Directive (CSRD) already requires scope 1 disclosure for companies in its first reporting waves. In the US, California’s SB 253 requires companies with over $1 billion in annual revenue doing business in California to report scope 1 and scope 2 emissions, with first reports due November 10, 2026. ISSB-aligned disclosure rules are extending similar requirements across other jurisdictions.
What’s the fastest way for a company to start reducing scope 1 emissions?
Start by measuring at the facility level, since this activity data shows where emissions concentrate. From there, the quickest wins are usually operational, such as repairing refrigerant and methane leaks, upgrading inefficient combustion equipment, and electrifying vehicle fleets, because they sit within the company’s direct control and often pay back through lower fuel and maintenance costs.
Is behind-the-meter power scope 1 or scope 2?
It depends on who controls the generating asset. If a company owns or financially controls its on-site generation, the emissions are scope 1. If a third party owns and operates the generator and sells the power- the structure behind most data center power deals- the buyer reports those emissions as scope 2 under the GHG Protocol’s Scope 2 Guidance.



